

Dow Jones outlook: CPI, oil and yields put the rally to the test
US index futures rebounded in the first half of Wednesday’s session, along with European indices ahead of the release of US CPI. Some slightly dovish remarks from the Fed’s Williams seem to have helped sentiment a little, but whether those comments will be backed by data remains to be seen. While slightly hotter than expected inflation data shouldn’t be enough for markets to price in an October Fed hike with more than a coin flip probability, it can nonetheless reinforce expectations of further tightening later in the year.
Share this:
US index futures rebounded in the first half of Wednesday’s session, along with European indices ahead of the release of US CPI. Some slightly dovish remarks from the Fed’s Williams seem to have helped sentiment a little, but whether those comments will be backed by data remains to be seen. While slightly hotter than expected inflation data shouldn’t be enough for markets to price in an October Fed hike with more than a coin flip probability, it can nonetheless reinforce expectations of further tightening later in the year. As well as boosting the dollar, it could undermine equities which are already having to come to terms with the recent upsurge in bond yields and elevated oil prices. We maintain a cautious Dow Jones outlook for now.
US indices have had mixed performances of late
The abovementioned macro factors are making life increasingly difficult for US equity bulls to justify continued dip buying near record levels.
The S&P 500 and Nasdaq have remained remarkably resilient until a few days ago, but much of that strength has been concentrated in a relatively small group of mega-cap technology and AI stocks. Elsewhere, the picture is less convincing.
The Dow Jones and Russell 2000 are particularly worth watching in this respect. Their recent weakness points to a broader deterioration in risk appetite that is becoming harder for investors to dismiss.
Crude oil continues to apply pressure
Oil is at the centre of the problem. Prices have now risen for the third consecutive week to near their range highs, with Brent now comfortably above $100 a barrel, at around $105-A$106 area.
Rising oil prices matter not just because of the direct hit to consumers and businesses, but because of what it means for inflation and interest rates. Higher energy prices risk keeping inflation elevated for longer, while Treasury yields have already moved sharply higher in recent weeks as markets reassessed the outlook for monetary policy.
The 10-year Treasury yield has recent highs reached its highest levels since the early 2000s. At these levels, bonds are also becoming a more credible alternative to equities, potentially making investors less willing to pay the high valuations that have supported the stock market.
That makes today’s US inflation report particularly important.
CPI takes centre stage
Markets expect core CPI to rise 0.2% month-on-month, taking the annual rate to 2.5%, while headline inflation is expected to accelerate to 3.6%.
The problem for anyone looking for a major market move is that expectations are already fairly well established. Unless the numbers deliver a meaningful surprise, the initial reaction could prove relatively muted. That said, with oil prices elevated and Treasury yields already putting pressure on equities, even a modest upside surprise could reinforce concerns about the inflation outlook.
For the Dow, the more interesting question is whether CPI provides the catalyst for the next decisive move.
Dow Jones outlook: technical analysis and key levels
The Dow’s recent price action suggests that the market is becoming less comfortable at these elevated levels.
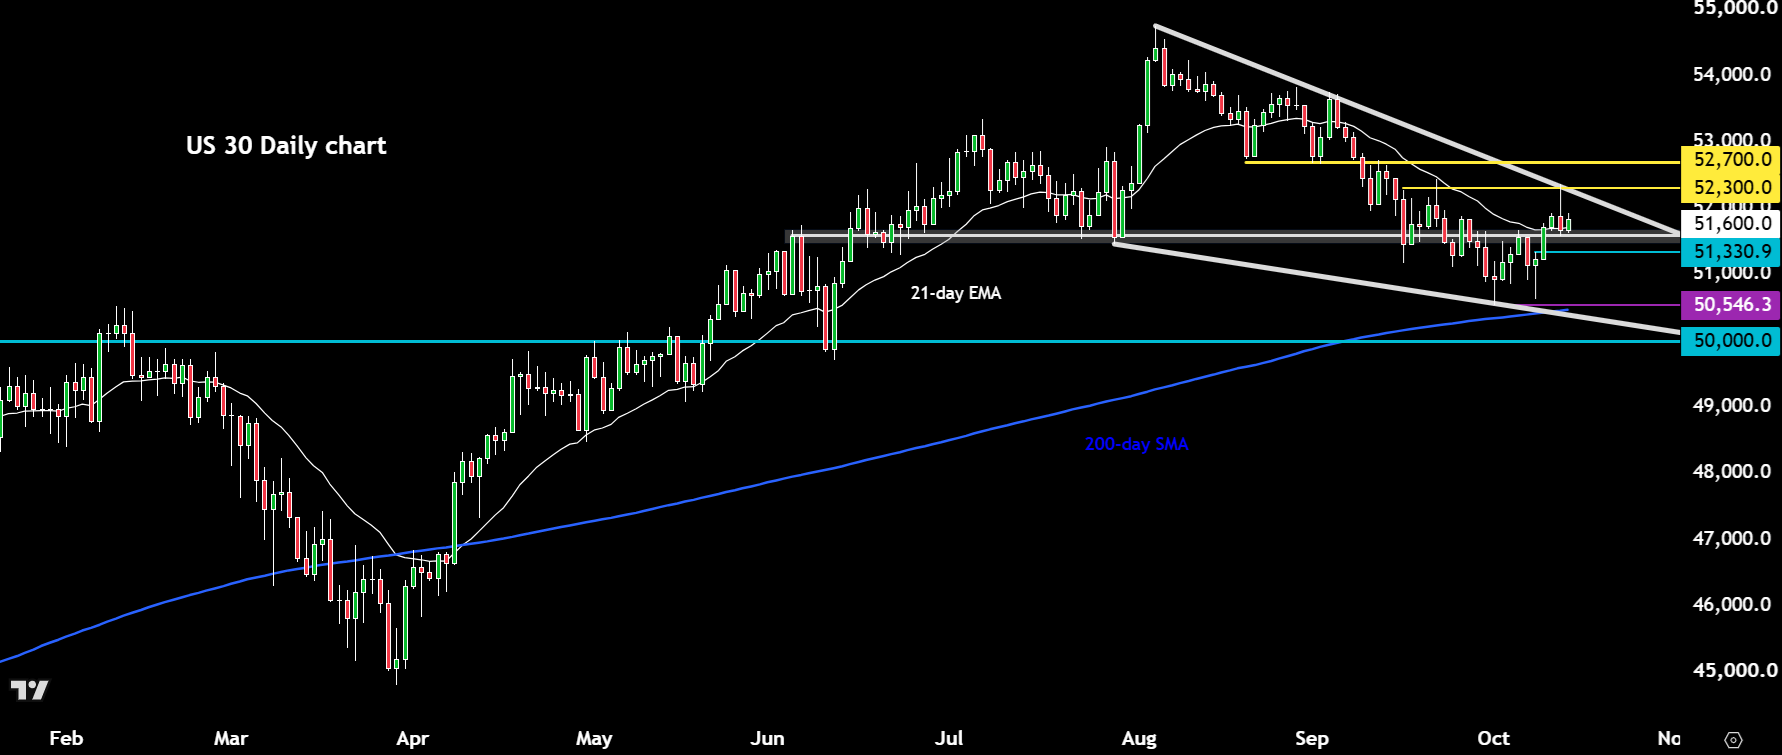
Tuesday’s session produced an inverted hammer after the Dow Jones index reversed sharply from the bearish trend line and resistance around 52,300 area. That is hardly an encouraging signal, particularly with CPI looming.
That said, we have not yet seen any meaningful downside follow-through. Key support around 51,600 has held firm for now.
But if that changes later, then the index could drop to test the next important support area around 51,330, below which there is nothing significant until the recent lows near 50,500 – 50,600 area.
On the upside, a potential move above 52,300 would improve the technical picture and potentially open the way towards 52,700 or even 53,000. But the risk is that Tuesday’s reversal proves to be the start of something more significant.
For now, the bulls are still hanging on. But with Brent oil back above $105+, Treasury yields remaining elevated and the Dow struggling to regain momentum, the technical picture is becoming increasingly fragile. Today’s CPI report could determine whether this is simply another pause in the broader rally or the beginning of a more meaningful correction.

Related tags:
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Dow Jones outlook: CPI, oil and yields put the rally to the test
US index futures rebounded in the first half of Wednesday’s session, along with European indices ahead of the release of US CPI. Some slightly dovish remarks from the Fed’s Williams seem to have helped sentiment a little, but whether those comments will be backed by data remains to be seen. While slightly hotter than expected inflation data shouldn’t be enough for markets to price in an October Fed hike with more than a coin flip probability, it can nonetheless reinforce expectations of further tightening later in the year.
EUR/USD Bounce Hits a Wall of Fed Hawks and French Finances
The EUR/USD forecast hinges on U.S. CPI after five straight weekly losses, with hawkish Fed bets and a fully priced ECB rate hike weighing on the euro.
EUR/USD Outlook: Can Hot CPI Sustain the Stretched US Dollar Rally?
EUR/USD looks oversold as the US dollar rally loses momentum. With hot CPI expectations potentially priced in, could inflation trigger a dollar pullback?

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.