

Event Risk Like NFPs and the FOMC Rate Decision Lost Serious Traction in 2025
There were plenty of surprises through 2025 – like the introduction of US ‘reciprocal tariffs’, a record-breaking shutdown from the US government and military strikes on Iran without a catastrophic oil reaction. Yet, the most remarkable development may be the lost traction in traditional data.
Share this:
Talking Points:
- The dramatic announcement of Liberation Day tariffs by the United States in April seemed to shake a lot of the complacent risk built up in the market to that point
- With a market bled of excessive premium in the first half of the year, the draw of complacency accompanied by convenient justifications - like ‘AI revolution’ - kept risk appetite buoyant
- A robust complacency drive helped the markets ride over key event risk and systemic themes like a steady decline in NFPs and a controversial FOMC course
There were plenty of surprises over the past year ranging from the avoidance of official recession despite a trade war, a fast levelling out of a dovish policy regime across the developed world and riding through amplified concerns around the growing fiscal issues in the global system. However, from a trader’s perspective, the bigger surprise was the drop in responsiveness from the markets relative to major event risk such as rate decisions, employment reports and news that tapped into key themes.
The reduced influence of the larger themes in dictating systemic market trends very likely cascades down to the effectiveness of the catalysts that would provoke greed or fear through ‘surprise’ in the event risk. Further, when the focus on major thematic topics rotates regularly, it will further reduce the traction that ‘feeder’ event risk would otherwise earn through its measured adjustment to expectations along those lines. While we expect fundamentals to dictate the tempo and camber of the markets, the reverse may actually be more accurate. A market that is more resilient to provocation and supportive of the complacency speculative bid, can moreso dictate its interests in interpreting the economic calendar or deeper fundamental currents.
Chart of the S&P 500 Index with 100-Day SMA, VIX Volatility Index and 20-Day ATR (Daily)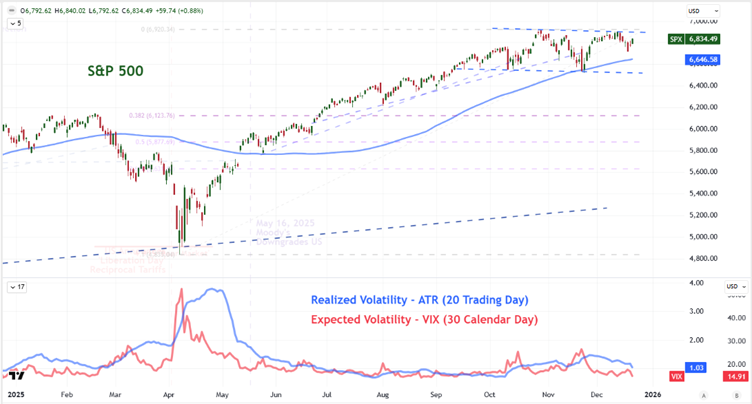
Source: TradingView, John Kicklighter
Looking to a particular venue of fundamentally-driven volatility, the US nonfarm payrolls (NFPs) have long proven among the most capable and reliable scheduled events when it comes to generating heat in the markets. For a backdrop, the heavy speculation around the economic impact of trade relations and fading consumer confidence alongside heavy debate over the Fed’s monetary policy course should have made this data release a strong candidate for volatility from the likes of the Dollar index far in excess of the daily activity norms.
However, meaningful volatility on the release day of the jobs report was the outlier. In 2025, there were a couple of instances where the volatility – measured by the daily range percentage – jumped significantly above the average with an NFPs release. That said, the April charge was in the context of Liberation Day volatility and therefore only the August release therefore stands out. This may be due to large revisions of the past payroll figures, questions over the data’s accuracy by the likes of the White House and disruptions when the theme mattered most (like with the government shutdown); but it is still very much out of the norm relative to history.
Chart of the DXY Dollar Index with Days of NFP Releases and 1-Day Range (Daily)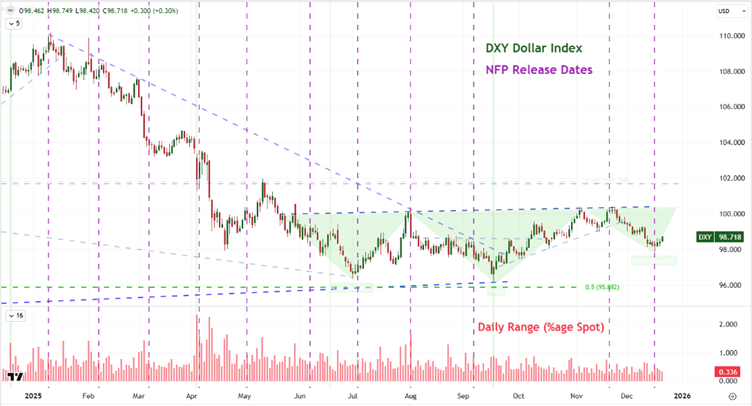
Source: TradingView, John Kicklighter
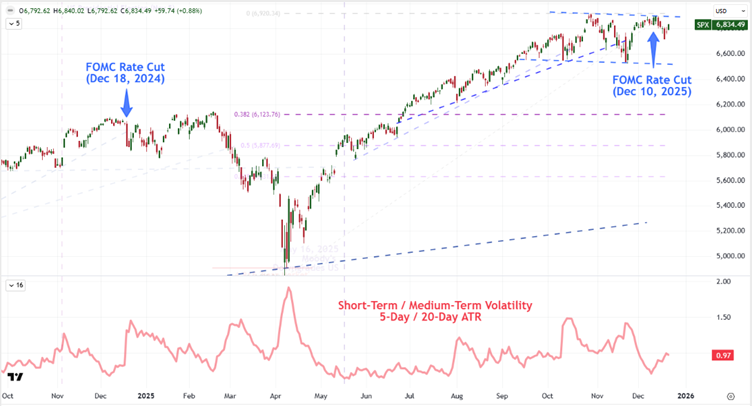
Perhaps an even more remarkable example of event risk losing its impact comes through the FOMC rate decision. Monetary policy is a deeper fundamental theme itself which makes the Fed updates as close a vehicle capable of striking a major nerve as there is through scheduled event risk. Now, the Fed - and other major central banks - endeavors to offer a reasonable outlook to the market, without guaranteeing an outcome, in order to reduce the volatility of surprises. However, the fine speculative setting and forecasting nature of the markets often overrides these efforts.
In 2025, the Fed delayed its return to a dovish policy regime despite aggressive calls from the markets, economists and the government to do so; but that didn’t curb the market’s climb with throttled implied volatility. Far more remarkable though was the lack of impact from the final FOMC rate decision of the year on December 10th. Amid heavy public debate over what course the central bank should be on and discussion around leadership change next year, the group delivered a conflicting update. They would cut rates by -25bps as expected but would also signal that it was only expecting one additional cut in 2026 (hawkish) while also announcing a restart of a smaller QE (dovish). That could have provided surprise for all in this event, yet the S&P 500 wouldn’t break its smallest running range in years.
Chart of the S&P 500 with 5-Day / 20-Day Relative ATR Volatility (Daily)
Source: TradingView, John Kicklighter
While we often focus our attention on technical patterns or the directional course of major fundamental themes or the limited impact potential of individual updates from the calendar; I believe it is far more important to look to the background of the markets themselves. If conditions are – as they have been in 2025 – such that event risk struggles to feed existing trends, forge breakouts or stand as catalyst for reversals; that can help us shape our trading approach and strategy. Given the December FOMC was a strong test of this market distortion through year’s end, it seems that we should retain a degree of skepticism over the impact potential of scheduled event risk into the start of 2026. However, this state is not the norm over a longer time frame; so it is important to keep tabs on the ‘event risk / impact’ scale to be ready to adjust when conditions swing back to normal.
-- Written by John Kicklighter, Global Head of Content
Related tags:
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/CAD reversal risk builds as central bank showdown looms
USD/CAD has delivered a bullish reversal signal from established support, just as traders prepare for Fed and BoC decisions. Aggressive Canadian rate hike expectations and conflicting momentum signals make the coming session important.

USD/JPY Weekly Outlook: AI earnings could overshadow the Fed and BoJ
AI sentiment has become a major driver of US Treasury yields and USD/JPY. With Microsoft, Alphabet and Amazon reporting this week, central bank decisions may have competition for traders' attention.
USD/JPY, Nikkei Break Lower as AI Meltdown Spreads
Thursday’s tech tantrum has become Friday’s fire sale. With Nikkei support giving way and the yen strengthening, could the selling start feeding on itself?
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.