


Markets 4x4: What caught our eye during Asian trade
Welcome to the inaugural edition of ‘Markets 4x4: What caught our eye during Asian trade, a post delivered daily by 4pm in Sydney detailing the key macro news and views from the Asian session.
Share this:
Welcome to the inaugural edition of ‘Markets 4x4: What caught our eye during Asian trade, a post delivered daily by 4pm in Sydney detailing four macro themes from the Asian session that caught our eye.
Here’s what you need to know for Monday, October 23.
Weekend geopolitical hedges unwound
With no major escalation in the conflict between Israel and Hamas over the weekend, hedges against downside in riskier asset classes were unwound in Asian trade. Gold and crude were off smalls while US stock futures, US Treasury yields and dollar were up smalls, although none were particularly convincing when it comes to their longevity. As anyone who was involved last Monday will note, risk squeezes don’t typically last long in risk-fuelled environments such as these. Nor are gold and crude likely to remain pressured for too long in the absence of an unlikely positive resolution in the near-term to the conflict in Gaza.
Industrial metals flashing red
There’s been some rare optimism towards China’s economic trajectory thanks to last week’s GDP and monthly indicator beats, sending Citi’s China economic surprise index into positive territory for the first time since June. But that looks to be driven by the data meeting extremely low expectations rather than delivering a compelling signal that activity in the world’s second-largest economy is improving meaningfully.
But don’t take my word for it; just have a glance at the industrial metals complex today to get the real sense as to what’s going on. Bullish iron ore and coking coal trades have been taken out the woodshed and chopped to smithereens, leading a broad push lower across most industrial commodities. Until China’s property sector woes are resolved, it’s hard to get excited about the prospects for activity, earnings or the outlook for the Chinese yuan.
US equity rally faces stern test
With four of the ‘Magnificent 7’ releasing third quarter earnings reports and the Fed’s preferred underlying inflation gauge out Friday, you get the sense this week could easily set the tone for the S&P 500 over the remainder of the year. Technically, the index looks vulnerable to further downside on the charts having broken channel support and 200-day moving average last week. With analyst expectations for earnings juiced by unproven artificial intelligence hype, any disappointment could see the index unravel given big tech remains one of the few financial assets yet to fully adjust to the starkly different interest rate environment. The near-term performance will prove crucial for US equities over the longer-term, you’d think.
No news is good news for bond market
There was so much Fed speak last week you’d be excused for thinking the committee had been expanded ten-fold. It was ridiculous watching FOMC members rush to provide as much information on anything before the start of their enforced blackout, resulting in what ended up being a muddled message for markets. But with the blackout now enforced, few major US data releases scheduled until the end of the week and no major Treasury auctions to speak off, I wonder whether the path of least resistance for yields may be lower in the near-term given stretched short positioning in futures.
Market of the day: AUD/USD
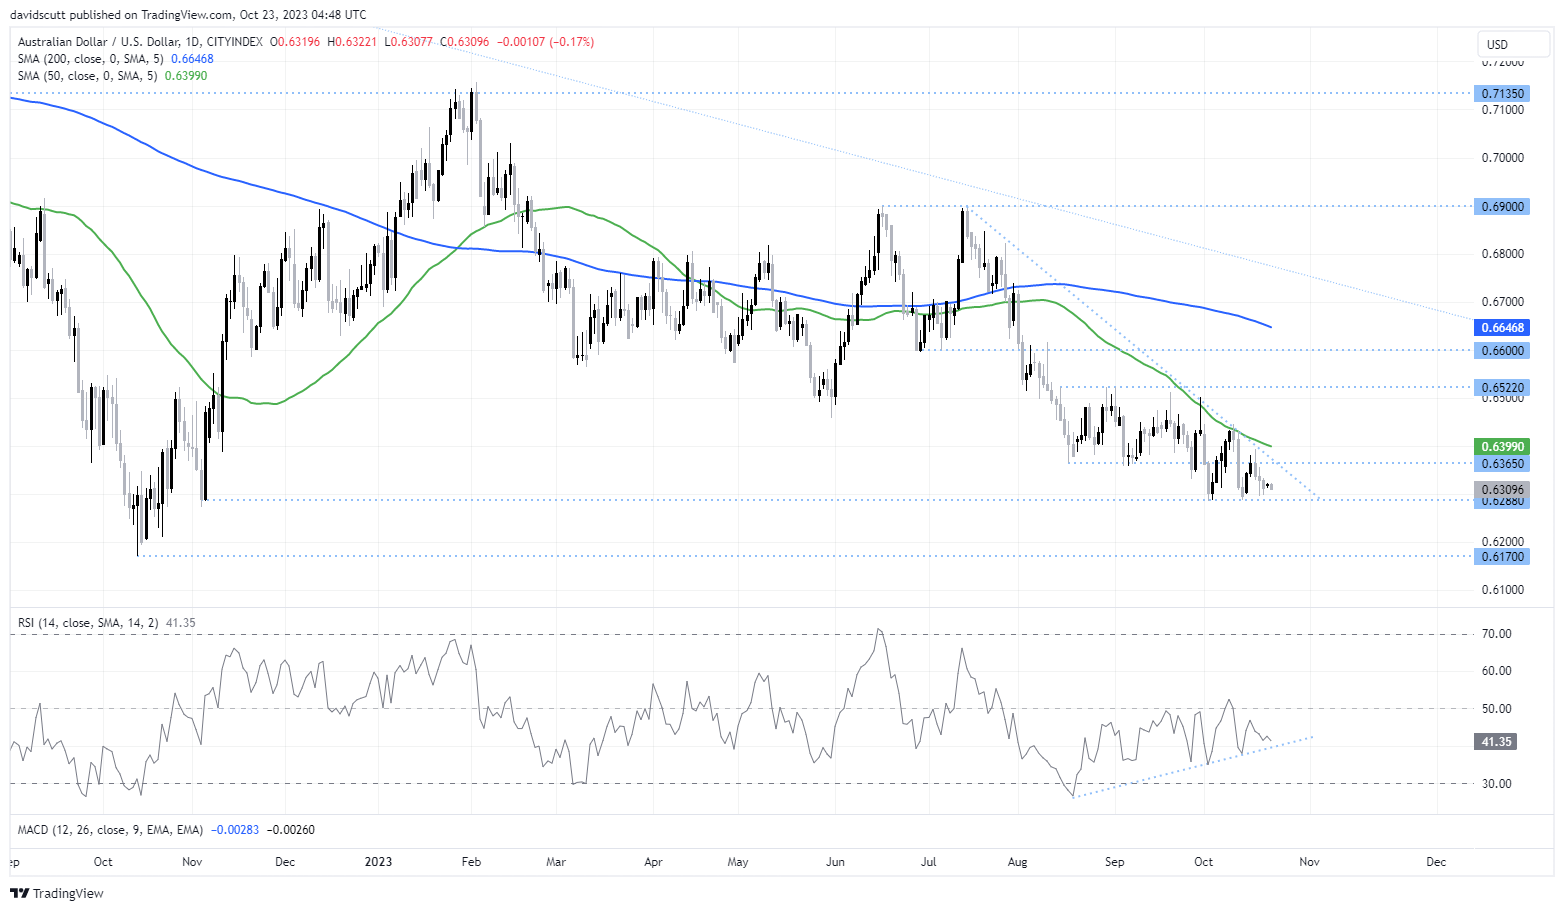
It’s going to be a big week for the AUD with Australia’s Q3 consumer price inflation report out Wednesday, surrounded either side by appearances from RBA governor Michele Bullock. Fundamentally, with concern about the global economic outlook bubbling away, interest rate differentials are one of the few positives left going for the Aussie right now.
Right now, a full 25 basis point rate hike is priced into the AUD overnight index swap curve by May with a move as soon as November deemed around 30%. But even with a full hiked factored in, market-based inflation expectations have hit the highest level since the early stages of the RBA’s tightening cycle last year, hinting traders want to see even more tightening priced in to feel confident inflationary forces are anchored.
For AUD/USD, without a hot underlying inflation figure or highly unlikely near-term improvement in the global macroeconomic backdrop, risks appear to remain biased lower right now. While RSI suggests downside is ebbing, having been rejected at downtrend resistance and 50-day MA on multiple occasions since September, the technicals suggest AUD/USD remains a sell-on-rallies play. On the topside, .6365 and .6520 are the horizontal resistance levels to watch.
-- Written by David Scutt
Follow David on Twitter @scutty
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/CHF Reverses as Swiss Franc Surges amid Bond Carnage
USD/CHF reverses from channel resistance as bond volatility surges and broad Swiss franc strength points to a possible carry-trade unwind.


USD/MXN Analysis: Is Super Peso Starting to Fade?
Over recent trading sessions, the Mexican peso has continued to show signs of weakness against the U.S. dollar. This can already be seen in USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting sustained buying pressure in favor of the dollar in the short term.


Canadian Dollar Analysis: USD/CAD Returns to July Highs Ahead of NFP
The Canadian dollar continues to face one of its most challenging environments in recent months when it comes to maintaining strength against the U.S. dollar. The weakness of the Canadian currency is clearly reflected in USD/CAD, which has now recorded nine consecutive bullish sessions and gained more than 1.7% during that period.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.