



NZD/USD Forecast: RBNZ rate track in focus as cut seen locked in
The RBNZ is almost certain to cut by 25bp this week, but the updated rate track and voting split will set the tone for NZD/USD. With economic data soft, inflation contained, and labour slack growing, its guidance may lean even more dovish than markets expect.
Share this:
- RBNZ 25bp cut to 3% deemed near certain in August
- Markets expect cycle low near 2.75%, risk of 2.5%
- Soft data and labour slack point to mildly dovish RBNZ bias
- NZD/USD support at .5913, resistance at .5985/.6000
RBNZ summary
In the absence of a shock decision to hold rates steady or deliver an unlikely supersized cut, Wednesday’s Reserve Bank of New Zealand (RBNZ) monetary policy decision will be all about the forward guidance it delivers, and how committee members vote, when it comes to financial markets. A 25 basis point cut, taking the cash rate to 3%, is deemed highly likely, lifting cumulative easing this cycle to 250 basis points if delivered. With markets pricing in an additional rate cut, most likely late this year or early next, the bank’s updated rate track will be extremely important for NZD/USD and other Kiwi pairs.
RBNZ Rate Track Update Key
When last issued in May, the RBNZ saw a faster and deeper easing cycle than three months earlier, with the risk of the cash rate being reduced below 3% seen from the December quarter. Previously, its forecasts implied the cash rate bottoming at either 3% or 3.25%, so the revisions were incrementally more dovish.

Source: RBNZ
Heading into the August policy meeting, markets have added another 25 basis point cut to the cycle, with swaps implying the cash rate will bottom at 2.75%, with a meaningful risk of that being delivered by November when the bank’s next monetary policy statement and updated forecasts are released. Around a two-in-three chance is priced, based on implied probabilities from swap markets. The focus on the rate outlook, not what may happen tomorrow, reflects traders’ confidence in the RBNZ delivering another 25 basis point cut at the August meeting, with pricing implying a 94.5% probability.

Source: Bloomberg
Put simply, if it doesn’t deliver a quarter-point reduction, the market impact will be immediate and large. But if it does, the rate track will likely set the tone for Kiwi rates and NZD.
Economic Data Remains Weak
Emboldening the view the RBNZ has more work to do to ensure inflation doesn’t undershoot on the downside over the medium to longer term, New Zealand economic data hasn’t exactly been shooting the lights out, even with 225 basis points worth of cuts this cycle. Citi’s economic surprise index, which tracks how data prints relative to economist expectations with more weight put on recent indicators, sits just above zero, implying roughly the same amount of beats as misses, with only a slight edge to the former.

Source: LSEG
Delving into individual data releases, evidence suggests the risk of a meaningful reacceleration in domestic inflationary pressures—heavily influenced by labour market conditions—appears low.
While headline consumer price inflation accelerated again on a year-ended basis in the June quarter, rising 2.7%—a tenth above the RBNZ forecast—the proportion of the CPI basket with price increases of 3% or less increased to 64.3%, the highest since Q3 2020. Non-tradable prices, which tend to reflect domestic demand and supply conditions and are heavily influenced by the labour market, rose 3.7% over the year, continuing the disinflationary trend that began in early 2023 when they peaked at 6.8%.

Source: TradingView
Importantly for the RBNZ rate outlook, its quarterly survey of professional forecasters saw inflation sitting at 2.28% looking two years ahead following the Q2 report, near the midpoint of the target band and a touch softer than what was seen after the prior update for Q1.
What’s also become clear since the RBNZ’s last forecasts is that labour market conditions have softened more than it anticipated. Yes, unemployment at 5.2% was in line with its forecasts, but only because of a continued decline in participation, which came in three tenths below expectations. Employment growth, too, declined 0.1% in Q2 versus the bank’s forecast for a 0.2% increase. It’s little wonder private sector wages grew just 2.2% in the year to June, again a tenth below forecast.
While the RBNZ doesn’t have a full employment mandate, the sheer amount of underutilised and unemployed workers points to excessive labour market slack. That creates downside risks for wages growth, which is influential on domestic price pressures.
Domestic disinflation tilts risks dovish
From a directional perspective, it’s more likely the updated RBNZ rate track will be lower rather than unchanged or higher than what was issued three months ago. It would not surprise if it at least matched market pricing, or even floated the risk of the cash rate bottoming at 2.5% this cycle. There is nothing in the data to suggest policy rates are stimulatory or that the economy requires no further support. The risk of importing inflation has also been reduced recently by the strengthening in the New Zealand dollar, giving the RBNZ more wriggle room to lean dovish if it chooses.
While the policy statement will be scoured for clues, my view is the information is always packaged up in the forecast track, making it the immediate reference point for traders. If the RBNZ does deliver a quarter-point reduction, the vote breakdown also matters. In May, there was one dissenter who wanted to keep the cash rate steady at 3.25%, with five voting for a cut. That turned out to be more influential on market moves than the rate track or the statement. Another dissenter or more this time could spark a decent rally in NZD/USD and Kiwi pairs.
NZD/USD Technical Analysis
Source: TradingView
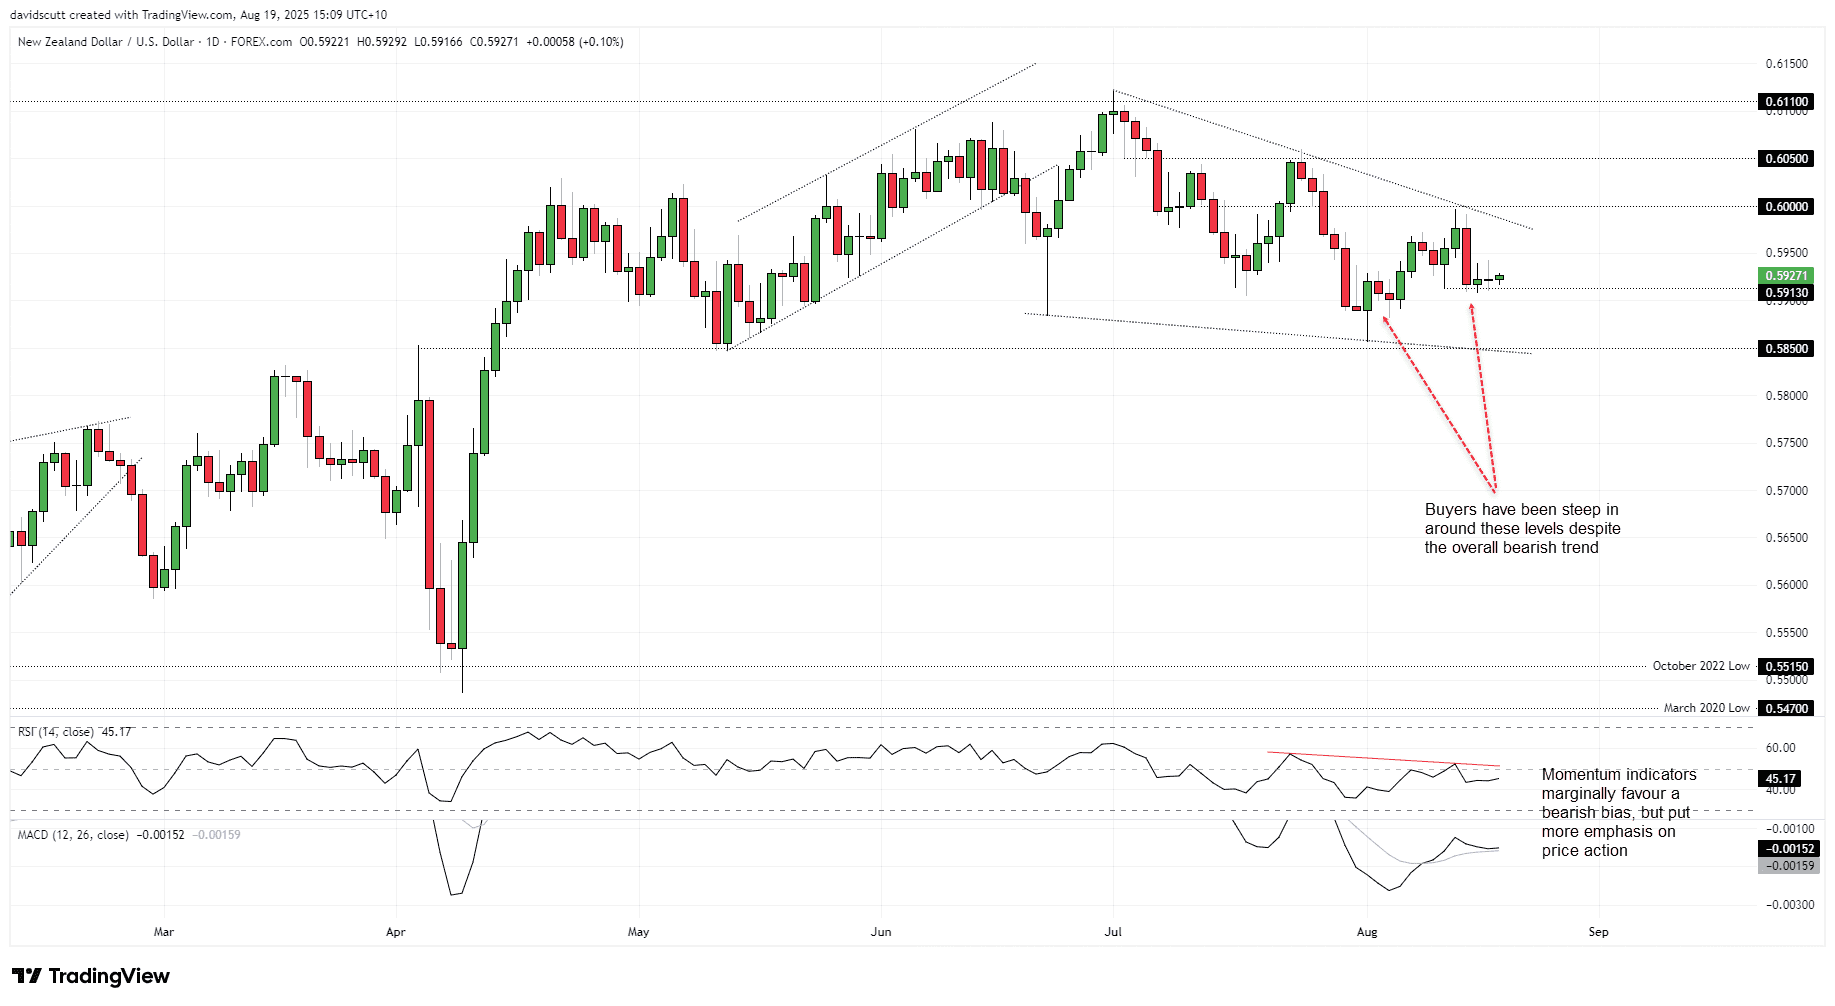
Looking at NZD/USD on the daily chart, the pair has been trending lower in what resembles a falling wedge since the start of July. While that points to the risk of an eventual resumption of the bullish trend from the Liberation Day lows in April, it remains rangebound for now.
Near-term support is found at .5913, where the price bounced on four separate occasions in the past six sessions. The lack of downside may be explained by the wall of bids beneath .5900, which absorbed offers for more than a week in late July and early August, stepping in before support at .5850.
On the topside, wedge resistance is found around .5985 today, with horizontal resistance just overhead at .6000. That’s the key zone to monitor around the RBNZ decision. If it were to give way, .6050 and .6110 are the levels to watch.
From a price momentum perspective, a marginal bearish bias is favoured with RSI (14) trending lower and now beneath 50, while MACD remains in negative territory despite recently crossing the signal line from below. It’s not a strong signal by any stretch, so price action should take precedence.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq volatility shock warns against buying too early
An extraordinary sell-off has left Nasdaq 100 futures deeply oversold, but history suggests further downside is common before a sustained recovery takes hold.
Canadian Dollar Short-term Outlook: USD/CAD Plunge Stalls at Pivotal Support—Range Break in Focus 11 5 2026
Friday’s U.S. and Canadian employment reports could trigger a decisive USD/CAD move as bulls and bears battle for control at critical support.


GBP/USD Forecast: BoE Caution Leaves the Pound Searching for Direction
Although GBP/USD has gained close to 0.5% over the last three trading sessions, reflecting a period of relative strength for the British pound, today's session has started to show a more neutral tone and the bullish momentum seen earlier in the week has begun to slow.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.