

S&P 500 weekly outlook: CPI, US-Iran Situation and Yields in focus
The S&P 500 fell on Friday to post a flat close on the week. Rising yields and elevated oil prices reminded investors that the macro backdrop is turning challenging. Friday’s US jobs report raised the pressure on the Fed to hike as the report was considerably stronger than expected. All the attention will be on inflation data in this shortened week for US investors, plus the usual suspects of oil and bond yields, ahead of the FOMC rate decision in the following week.
Share this:
The S&P 500 fell on Friday to post a flat close on the week. Rising yields and elevated oil prices reminded investors that the macro backdrop is turning challenging. Friday’s US jobs report raised the pressure on the Fed to hike as the report was considerably stronger than expected. All the attention will be on inflation data in this shortened week for US investors, plus the usual suspects of oil and bond yields, ahead of the FOMC rate decision in the following week. Tensions in the Middle East remained elevated during the weekend. We maintain a cautious S&P 500 outlook in the near-term.
NFP beat and now the focus is on CPI
The headline non-farm payrolls figure jumped to 162,000, well above the 56,000 expected. The previous month’s reading was also revised significantly higher, from a decline of 23,000 to an increase of 21,000, while the net revision for the prior two months stood at 55,000. Taken together, the figures point to a considerably stronger US labour market than recent data had suggested. That combination of stronger employment and relatively firm wage growth has raised concerns that inflation may prove stickier than hoped, increasing the likelihood that the Federal Reserve could raise rates and keep interest rates higher for longer.
Due to the Labor Day holiday in the US, this week’s key data releases will be pushed back a bit. The US CPI report is due on Friday as a result and is therefore likely to be crucial for the near-term S&P 500 outlook. We also have PPI on Thursday, a day when the ECB decides on interest rates (likely a hike).
As far as the Fed is concerned, well there is a bit of disparity between the Fed Chair Kevin Warsh and Governor Christopher Waller. While Warsh was hawkish at the Jackson Hole summit, Waller not nearly as hawkish and indicated that he wants to see the inflation data before deciding whether to support a rate hike or hold rates steady. That means the CPI release could move the needle and it represents the last major piece of economic data before the Fed’s next meeting.
If inflation comes in hotter than expected, markets could increasingly price in a September hike. That would probably put renewed pressure on the S&P 500, particularly if Treasury yields move sharply higher.
Conversely, a softer CPI reading could revive expectations of lower rates and provide another catalyst for equities to push higher.
US equity indices turned lower on Friday following the jobs report, as Treasury yields moved higher and expectations for a September Fed rate hike increased. Markets are now pricing in roughly a 59% probability of a hike, up from 49% before the jobs figures.
Technical S&P 500 outlook and levels to watch
The key question is whether the index can maintain its broader bullish structure while navigating the renewed pressure from interest rates in the coming days.
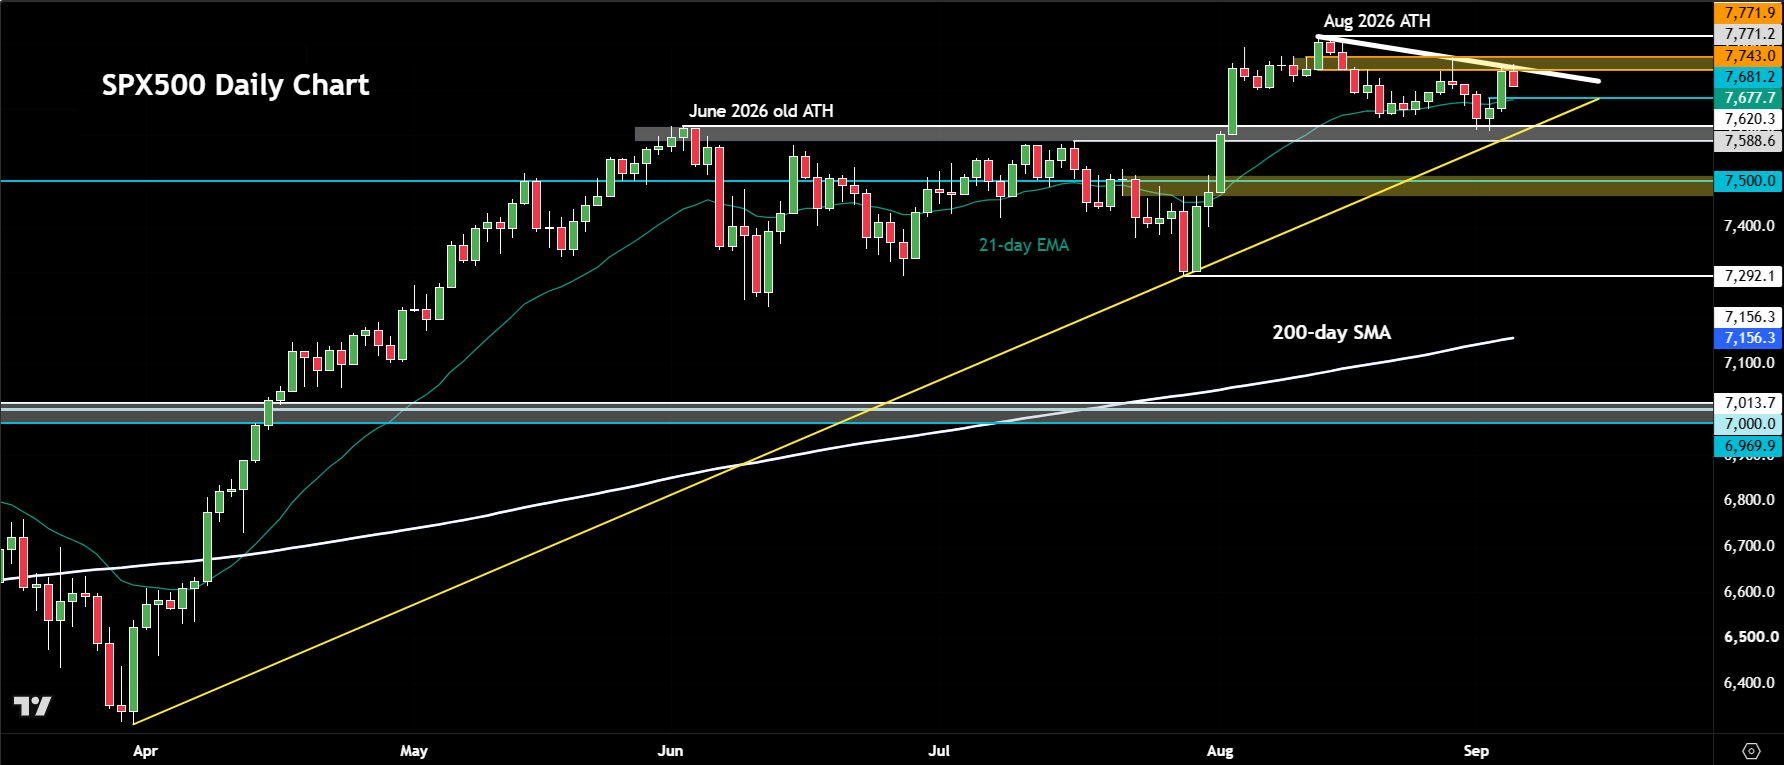
Last week, the S&P 500 found resistance around the 7,750 area, where it previously sold off from on August 28. This level sits inside the broader 7743 to 7772 area of resistance.
The short-term bearish trend line held last week. The index needs to move above that trend line to signal a resumption of the bullish trend following the lengthy consolidation phase that has been taking place on the S&P 500.
So, there is a risk that we could see a bit of a pullback, possibly even a correction, if macro risks persist while the bear trend remains intact.
Near-term support comes in around 7681, the highs from Wednesday which was taken out during Thursday’s sharpy rally. Below that the longer-term support zone between 7588 to 7620 area comes into focus next. It would be a bearish development if that area were to give way in the coming days.
The near-term risks to our S&P 500 outlook remain tilted to the downside following the stronger US jobs report, which raised the prospects of a rate hike from the Fed; continued hostilities in the Middle East, and the resulting rally in oil prices. A hotter-than-expected CPI reading could trigger a more meaningful sell-off, while softer inflation would likely provide some relief.


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 forecast: Democrats’ midterm victory rattled markets before dip buyers stepped in
Markets had a wild overnight session, with futures initially plunging before staging a sharp reversal and turning decisively higher. Global equity markets also bounced back, alongside gold and silver, while the US dollar has weakened. Oil prices fell on hopes of a deal between the US and Iran, providing another boost to market sentiment. The key question is why have markets rebounded so strongly and, more importantly, whether the recovery can last, given the prior assumption that a blue sweep would have been net negative for stocks?
AUD/USD Weekly Outlook: RBA Hike, US Midterms and NFP Collide
AUD/USD faces a pivotal week as an expected RBA hike, US midterm elections and nonfarm payrolls test the Australian dollar's recovery.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.