



US CPI Preview: Inflation Set to Rise – Why the Fed Won’t Care (Much)
This month’s CPI report is unlikely to lead to any seismic shifts in markets as traders remain focused on US-China trade developments and the lingering US Government shutdown
Share this:

US CPI KEY TAKEAWAYS:
- US CPI expectations: 3.1% y/y headline inflation, 3.1% y/y core inflation
- This month’s CPI report is unlikely to lead to any seismic shifts in markets as traders remain focused on US-China trade developments and the lingering US Government shutdown.
- The near-term bias on the US Dollar Index will remain to the topside as long as it holds above the mid-96.00 area, with the next resistance levels to watch at 99.50 and 100.00.
When is the US CPI report?
The US CPI report for September will be released at 8:30ET (12:30 GMT) on Friday, October 24.
What are the US CPI Report Expectations?
Traders and economists are projecting both headline and core (ex-food and -energy) CPI to come in at 3.1% y/y. This reading, if seen, would mark a rise in headline inflation from last month’s 2.9% reading and a steady core print relative to last month.
US CPI Forecast
The US government may be trending toward its longest shutdown in history, but the diligent employees of the Bureau of Labor Statistics are nonetheless working without pay to deliver the September CPI report – hats off to them!
While the effort of the BLS employees is admirable, this month’s CPI report is unlikely to lead to any seismic shifts in markets. In the current environment, traders are more focused on developments on the US-China trade front – US Treasury Secretary Scott Bessent and Chinese Vice Premier He Lifeng are poised to meet in Kuala Lumpur to set the stage for next week’s highly-anticipated meeting between Presidents Trump and Xi – and any progress on re-opening the US government.
If there was any doubt about what the Federal Reserve would do at its meeting next week (and in all likelihood, again at its meeting in December), the flare-up of trade tensions and lingering shutdown have FOMC members unanimously expecting to cut interest rates by 25bps, and its hard to see a single month’s inflation reading changing that meaningfully.
Broadly speaking, US consumer inflation has seen its decline toward the Fed’s 2% target stall for more than a year now, with headline CPI readings stuck between the 2.3% and 3.0% y/y range for that period. Meanwhile, Core CPI, which filters out more volatile food and energy prices to better show the underlying trend in prices, has turned higher in recent months after dropping as low as 2.8% y/y earlier this year.
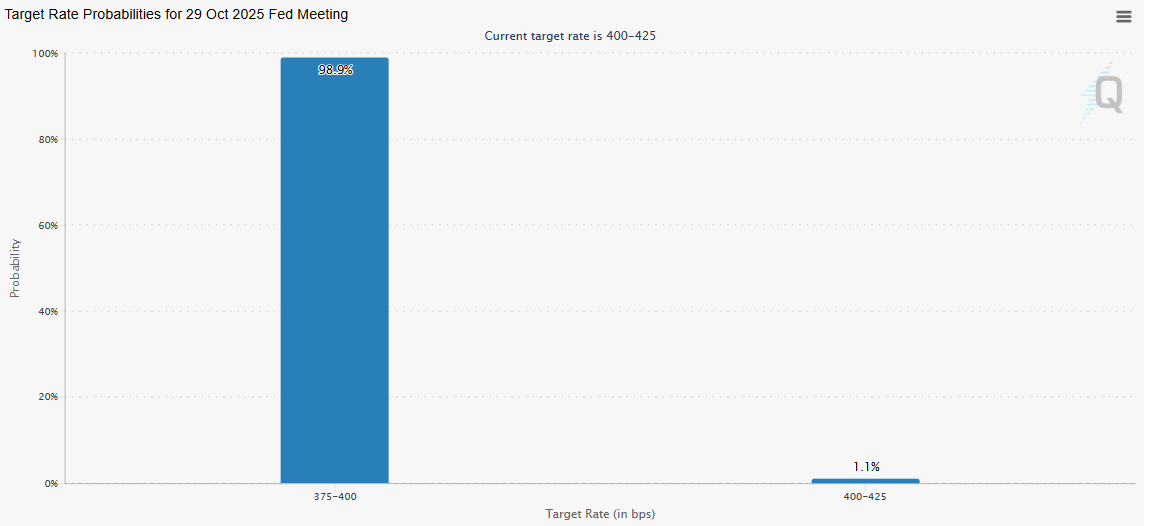
Despite a prolonged period of above-target inflation, the Fed’s concerns about the jobs market are more urgent, and as a result, traders have essentially fully discounted a 25bps rate cut to below 4.00% next week:
Source: CME FedWatch
As many readers know, the Fed technically focuses on a different measure of inflation, Core PCE, when setting its policy, but for traders, the CPI report is at least as significant because it’s released weeks earlier. As we noted above, CPI has generally ticked lower so far this year, but it remains stubbornly above the Fed’s 2% target:

Source: TradingView, StoneX
Looking at the chart above, the “Prices” components of the PMI reports have started to edge lower in recent months, but inflation nonetheless remains below where those readings would historically imply. Despite signs of slowing economic growth, firms are having to pay up for goods and services amidst the ongoing uncertainty around trade policy, potentially putting upward pressure on the CPI report in the coming months.

US Dollar Index Technical Analysis – DXY Daily Chart
Source: TradingView, StoneX
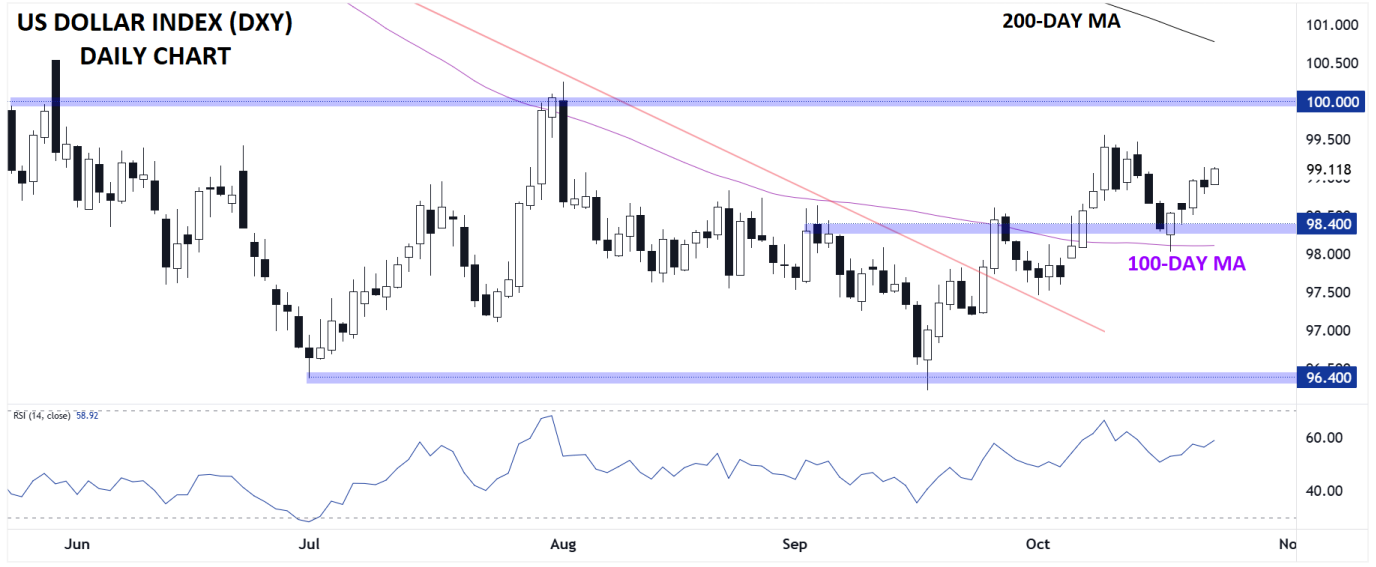
Even with traders increasing confidence that the Fed will continue to cut interest rates through at least the rest of the year, the US dollar is showing signs of turning higher. As the chart above shows, the US Dollar Index (DXY) has carved out a series of three “higher lows” since forming a potential double bottom near 96.40 midway through last month.
Moving forward, the near-term bias on the US Dollar Index will remain to the topside as long as it holds above previous-resistance-turned-support and the 100-day MA in the mid-96.00 area, with room to test the monthly and/or 4-month highs at 99.50 and 100.00 even next. A hotter-than-expected CPI report would help this bullish case at the margin, whereas a soft inflation reading could still be seen as a buying opportunity for the greenback as long as it holds the 100-day MA.
-- Written by Matt Weller, Global Head of Research
Check out Matt’s Daily Market Update videos on YouTube and be sure to follow Matt on Twitter: @MWellerFX



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/MXN Analysis: Is Super Peso Starting to Fade?
Over recent trading sessions, the Mexican peso has continued to show signs of weakness against the U.S. dollar. This can already be seen in USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting sustained buying pressure in favor of the dollar in the short term.


NFP Preview: Can the Jobs Report Overcome the Bond Market Meltdown Too?
Traders and economists expect the NFP report to show that the US created 90K net new jobs, with average hourly earnings rising 0.3% m/m (3.1% y/y) and the U3 unemployment rate at 4.1% - see what the leading indicators are suggesting!

Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.