



US dollar price action setups: EUR/USD, USD/JPY expose asymmetry as Hormuz deadline looms
Another TACO may be the base case, but with both the euro and yen under pressure, the downside risks look far larger if that view is wrong.
Share this:
- Markets leaning towards another TACO into Trump deadline
- EUR/USD, USD/JPY under pressure despite hikes priced
- Left tail risk large if escalation delivered
Summary
Markets are leaning heavily towards another TACO, and EUR/USD and USD/JPY sit at the centre of that view. Both the euro and yen are weakening despite multiple hikes being priced for the ECB and BOJ, reflecting their exposure to energy supply risks. If that’s tested again, both pairs look vulnerable to further downside, while another TACO would see that pressure unwind quickly.
TACO pricing vs left tail risk
The 8pm US EDT deadline for Iran to reopen the Strait of Hormuz is today’s defining risk event, yet markets are clearly priced for another TACO, an acronym for “Trump Always Chickens Out”, reflecting the pattern where aggressive rhetoric and hard deadlines give way to last-minute de-escalation.
That pricing isn’t coming from what Trump has said, it’s coming from what he’s done. Traders have been conditioned to expect de-escalation when rhetoric is at its most aggressive, with real escalation tending to arrive when there have been signs of apparent conciliatory efforts between the two sides, not outright ultimatums like this. That’s why, despite Trump warning Iran could be “taken out”, labelling Tuesday “Power Plant Day, and Bridge Day”, and threatening that “every power plant in Iran will be out of business, burning, exploding, and never to be used again” and “every bridge in Iran will be decimated”, risk isn’t getting walloped.
Instead, the base case is familiar. Another TACO, either via an apparent deal announced on Truth Social, with Iran often disputing the veracity of such announcements, or a further extension to negotiations, with timing risk skewed towards the Tokyo open where similar announcements have landed in recent weeks.
That leaves a binary outcome day with risks heavily skewed to the left tail. Another TACO is clearly the higher probability outcome, and if delivered, risk should rally, volatility should compress, and currencies hit by energy insecurity find relief, while the USD likely wilts as those supports unwind.
“Power Plant Day” sits at the other end, low probability but high impact. If it’s delivered, it’s all bets off. Risk assets get hammered, realised and implied volatility spike, the USD almost certainly surges, and energy prices rip higher as markets price in a meaningful increase in the probability of lasting supply disruption from the Gulf.
That’s the immediate event risk, but the inflation impulse is already building regardless of how this resolves.
Central banks boxed in
The US ISM services prices paid gauge jumped to 70.7 in March, the highest since October 2022 and the largest increase in over a decade, signalling energy is already feeding through into broader services inflation.
Source: TradingView
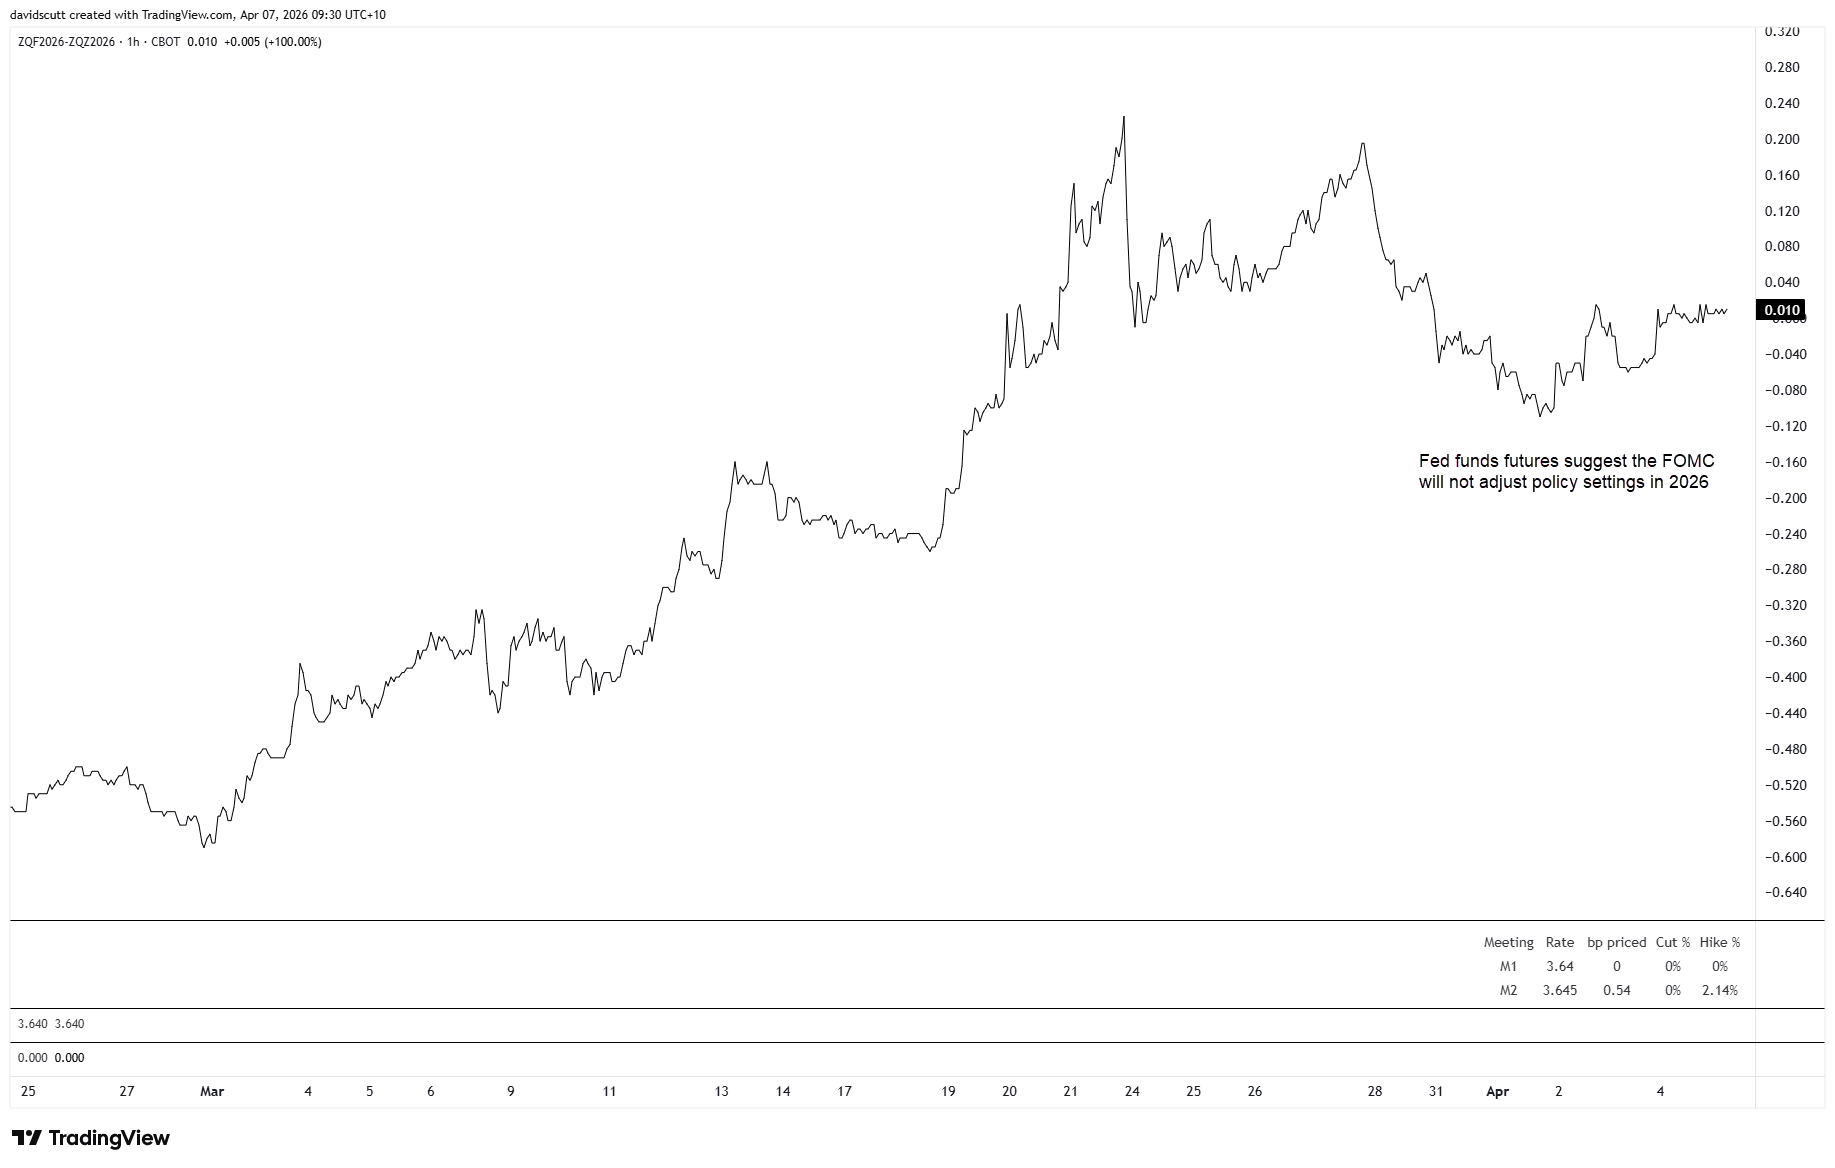
That’s the bind for central banks. Growth risks are rising, but inflation is reaccelerating, limiting their ability to respond with easier policy, helping explain why Fed funds futures price almost no chance of a move from the Fed through the remainder of 2026, while other developed market central banks are increasingly being priced to deliver hikes, not cuts.
And it’s showing up clearly in FX. Markets are pricing multiple hikes from both the ECB and BOJ this year, but it’s doing little to support either currency, with the euro and yen both under pressure as energy importers in this environment.
EUR/USD sell-on-rallies bias intact
Source: TradingView
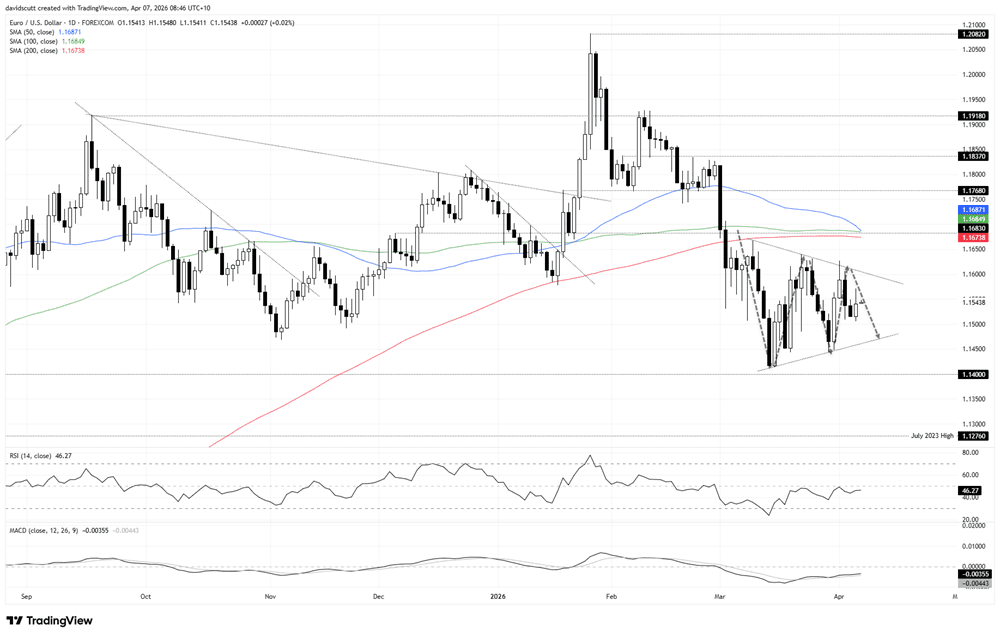
EUR/USD remains a sell-on-rallies play, having broken beneath each of the key medium and longer-term moving averages, setting a sequence of lower highs since peaking in late January. While RSI (14) and MACD point to diminishing downside pressure, the former remains sub-50 and the latter in negative territory despite crossing the signal line from below, keeping the broader bias intact but warning against chasing weakness.
More recently, the price has been coiling within a compression structure over the past month. Having entered from above, a downside break is favoured from a technical perspective, although the geopolitical situation in the Gulf will likely be the ultimate determinant.
Over the past two sessions, the price has run into sellers above 1.1550, making that the initial reference point overhead on Tuesday. Bids have been parked ahead of 1.1500, creating a tighter range within the broader compression structure.
If we see another TACO, offers above 1.1550 risk being overrun, opening a move towards downtrend resistance near 1.1600. A clean topside break of the structure would then run into a major hurdle, with the 200, 100 and 50DMAs clustered either side of 1.1683, a level that has acted as both support and resistance earlier this year.
If we instead get “Power Plant Day”, bids around 1.1500 would likely be cannon fodder, leaving uptrend support near 1.1470 vulnerable. A break there would expose 1.1450, 1.1410 and 1.1400 as the next downside levels to watch.
USD/JPY: 160 caps for now
Source: TradingView
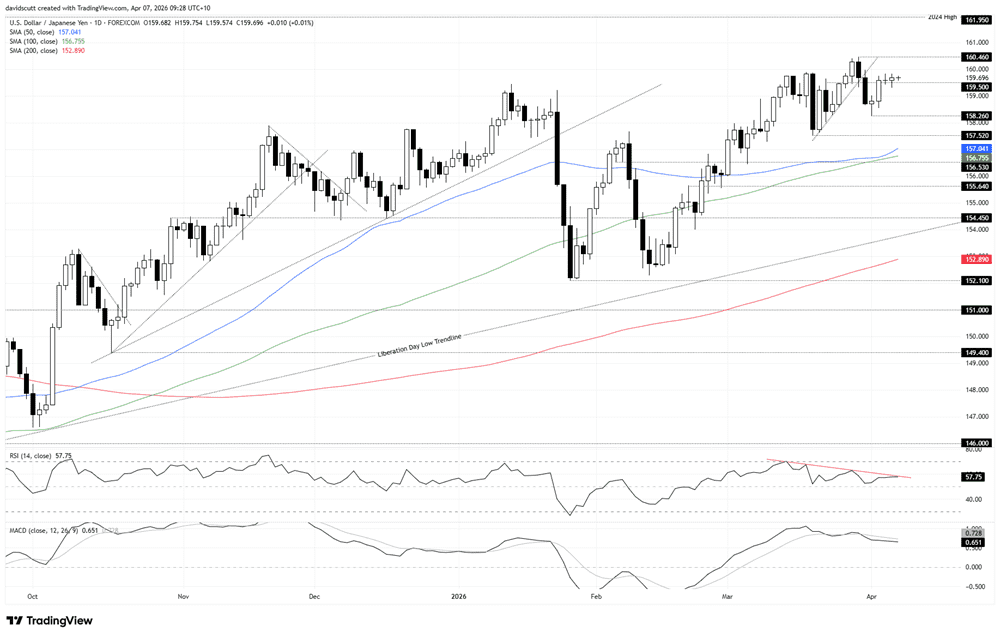
USD/JPY rallies continue to stall beneath 160, with the level acting as a soft cap given the risk of jawboning and/or outright intervention from the BOJ on behalf of the government. Intervention in this environment would likely prove ineffective beyond the very short term without a fundamental catalyst for USD weakness, but the threat alone has been enough to deter a clean bullish break, especially with TACO moments arriving thick and fast.
If we get another one on Tuesday, bids beneath 159.50 risk being overrun, putting 158.26 on the radar, the low from April 1. Below that, 157.52, the 50 and 100DMAs, and 156.53 are the downside levels to watch.
On the topside, the March 30 high at 160.46 is the immediate reference above 160. A clean break there would leave the price on a collision course for a retest of the 2024 high at 161.95. In an environment of actual escalation in the Middle East, the price may test that level even with intervention risk looming.
The signal from momentum is fading rather than reversing. RSI (14) and MACD are no longer pushing higher, aligning with the hesitation in the price around 160, but not yet pointing to a meaningful shift in direction, leaving the broader buy-on-dips structure intact for now.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Bears Lose Their Grip Ahead of NFP, USD/JPY Vols Elevated
US dollar selling pressure fades ahead of NFP as Fed hike bets retreat. USD/JPY stands out with a 141-pip implied move as FX volatility takes centre stage.
Nasdaq volatility shock warns against buying too early
An extraordinary sell-off has left Nasdaq 100 futures deeply oversold, but history suggests further downside is common before a sustained recovery takes hold.
ASX 200 Futures Hold Relatively Firm as Nikkei Plunges After Wall Street Rout
Wall Street's AI-led rout sends Nikkei futures plunging 9%, while ASX 200 futures hold relatively firm despite surging volatility and broader risk aversion.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.