



US jobs suffer sharp setback, but it is all about inflation – Forex Friday
Today’s US jobs report was the first of the four major releases before the Fed’s next meeting in September. As it turned out, this was a pretty bad report and as a result, the odds of a September rate hike fell to around 44% from north of 55% before the data was released.
Share this:
Today’s US jobs report was the first of the four major releases before the Fed’s next meeting in September. As it turned out, this was a pretty bad report and as a result, the odds of a September rate hike fell to around 44% from north of 55% before the data was released. The US dollar took a tumble, while gold and silver gained further ground. Still, the reaction in FX was not as significant as you would have expected. Markets’ focus will now turn to US CPI release next week, while oil prices are also in focus with the weekend approaching and still no sign of a deal. That could be a catalyst to help alleviate pressure on the US dollar heading deeper into the US session today.
NFP disappoints badly
The US labour market delivered another disappointing update, with non-farm payrolls rising by just 23,000 in July. That marked a sharp slowdown from June’s downwardly revised gain of 20,000, previously reported as 57,000, and represented the weakest reading since February’s 156,000 decline.
The picture was made considerably worse by substantial revisions to prior months. May payroll growth was cut to 63,000 from an initially reported 129,000, while June’s figure was lowered to 20,000 from 57,000. Taken together, the revisions removed a further 103,000 jobs from previously published estimates. This is reinforcing signs that hiring momentum has been fading for several months.
Despite the soft payroll numbers, the headline unemployment rate unexpectedly edged lower to 4.1% from 4.2%. This was because of another drop in the labour force participation rate, which fell to 61.4%, its lowest in more than five years.
Further evidence of cooling labour market conditions came from earnings data. Average hourly earnings increased by just 0.1% month-on-month, missing expectations for a 0.3% rise. On an annual basis, wage growth eased to 3.2%, well below the consensus forecast of 3.5%. The softer wage figures will provide some reassurance to policymakers concerned about persistent inflationary pressures, while also adding to evidence that labour demand is gradually losing steam.
How will data-dependant Fed react?
As today’s market reaction shows, economic data has become the predominant driver of US dollar moves of late, rather than just crude oil and geopolitical developments of the past. This is all because of Federal Reserve Chair Kevin Warsh’s decision to drop forward guidance. His recent mixed messages means that there is now more flexibility for markets to interpret incoming data from the Fed’s lens than in the past.
But until the FOMC’s September 16th meeting, we will have one more NFP report and two more CPI releases, including one next week. It is indeed inflation that the Fed is now trying to address and will react more forcefully to any surprises in CPI and employment. That’s why today’s weak jobs data hasn’t triggered a massive slide in the US dollar.
Focus turns to CPI
Undoubtedly US CPI report is next week’s key event. A stronger-than-expected inflation reading would reinforce expectations that the Fed may need to keep interest rates elevated for longer, supporting the dollar. Conversely, another soft inflation print could place renewed pressure on the US currency, especially in light of the recent data misses including today’s jobs report. In June, headline CPI fell more than expected to 3.5% compared a prior reading of 4.2%, while core CPI was also softer at 2.6%. Let’s see how prices evolved last month.
So, there are basically 3 really important data releases until the Fed’s next meeting which, along with oil prices, could help determine whether September hike expectations are reinforced or reduced.
USD/CHF best pair to play dollar on long side?
If the US dollar now manages to regain its poise heading deeper into the US session, its best bet would be against currencies where interest rates at low or zero. The Swiss franc comes to mind.
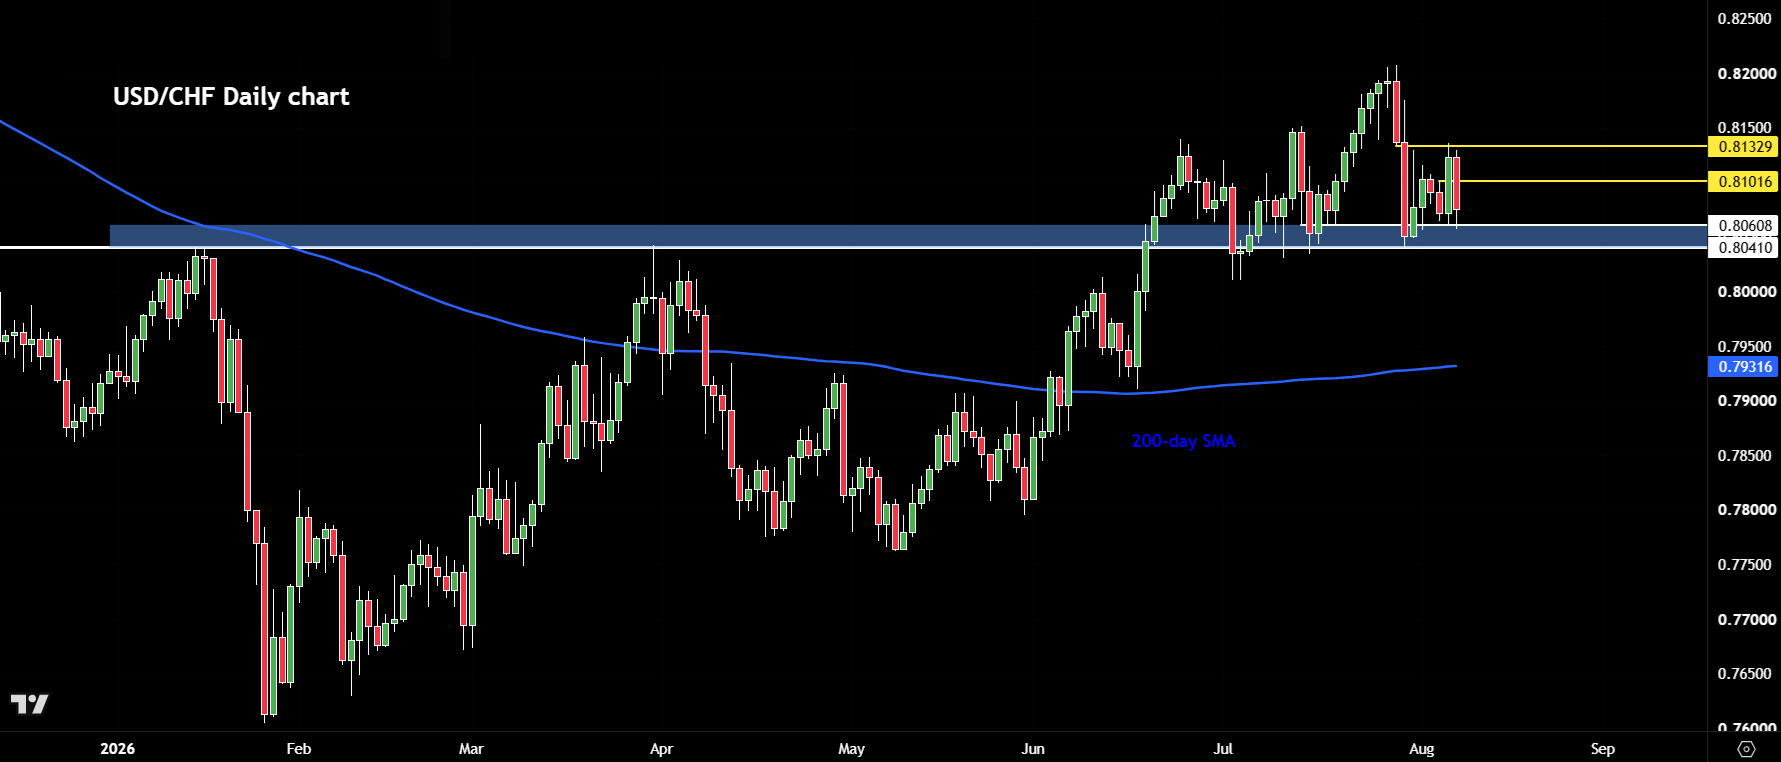
The USD/CHF pair has dropped to test key support in the 0.8040-0.8060 zone, which was previously major resistance. If it can hold its own above here, then we could see a recovery back towards short-term resistance levels such as 0.8100 and 0.8130 ahead of US CPI next week. Else, if the dollar selling continues, a bigger drop to 0.8000 cannot be ruled out. All told, I expect limited further downside in the US dollar owing to weekend risks of re-escalation in the US-Iran conflict and the potential for CPI to overshoot expectations next week.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD, GBP/AUD: Sterling Rally Faces a BoE Reality Check
Sterling faces a reality check as the BoE prepares to hike rates. GBP/USD and GBP/AUD approach resistance, leaving bulls vulnerable to dovish guidance.

Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.


USD/CAD Forecast: Canadian Dollar Gains Ground After U.S. Midterm Elections
The trading week continues to unfold and the recovery in the Canadian dollar has once again become a relevant theme in the short term. This can be clearly seen in the recent performance of USD/CAD, which is down nearly 0.4% during the session, reflecting a consistent recovery in the CAD against the U.S. dollar.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.