



US open: Positive tone on Wall Street ahead of a busy week
Market participants are feeling optimistic at the start of the week, with major indices in Europe rising and US stocks poised to open moderately higher and near record high territory
Share this:

US index futures
- Dow futures +0.0% at 35,891
- S&P futures +0.2% at 4713
- Nasdaq 100 futures +0.4% at 16,389
European indices
- FTSE -0.1% at 7,282
- DAX +0.9% at 15,771
- EURO STOXX +0.7% at 4227
Global risk appetite firms up heading into central bank bonanza
Market participants are feeling optimistic at the start of the week, with major indices in Europe rising and US stocks poised to open moderately higher and near record high territory, essentially erasing the turn-of-the-month drop on fears over a more aggressive Fed taper and the Omicron variant. Even news that the first UK patient died with the Omicron variant and that the country was preparing for a “tidal wave” of cases could not derail bulls’ sentiment. Yields on US Treasury bonds are also ticking lower, confirming the early strength in equity markets.
Looking ahead, this week’s market highlights will come from central bank pronouncements, with the most-watched gatherings taking place through the middle of the week, including monetary policy meetings from the Fed on Wednesday, as well as the BOE and ECB on Thursday.
See my colleague Joe Perry’s Week Ahead preview report for an overview of this week’s key events!
Where next for the S&P 500?
The widely-followed broad US index is set to open near record territory above 4,700, following a short-lived 4% pullback to end November. As any experienced trader will tell you, the trend is your friend when you’re trading using technical analysis, and in that vein, the path of least resistance remains to the topside for the S&P 500. If the index can confirm a close above 4,710 and ideally 4,740 this week, it would increase the odds of a year-end close above 4,800:
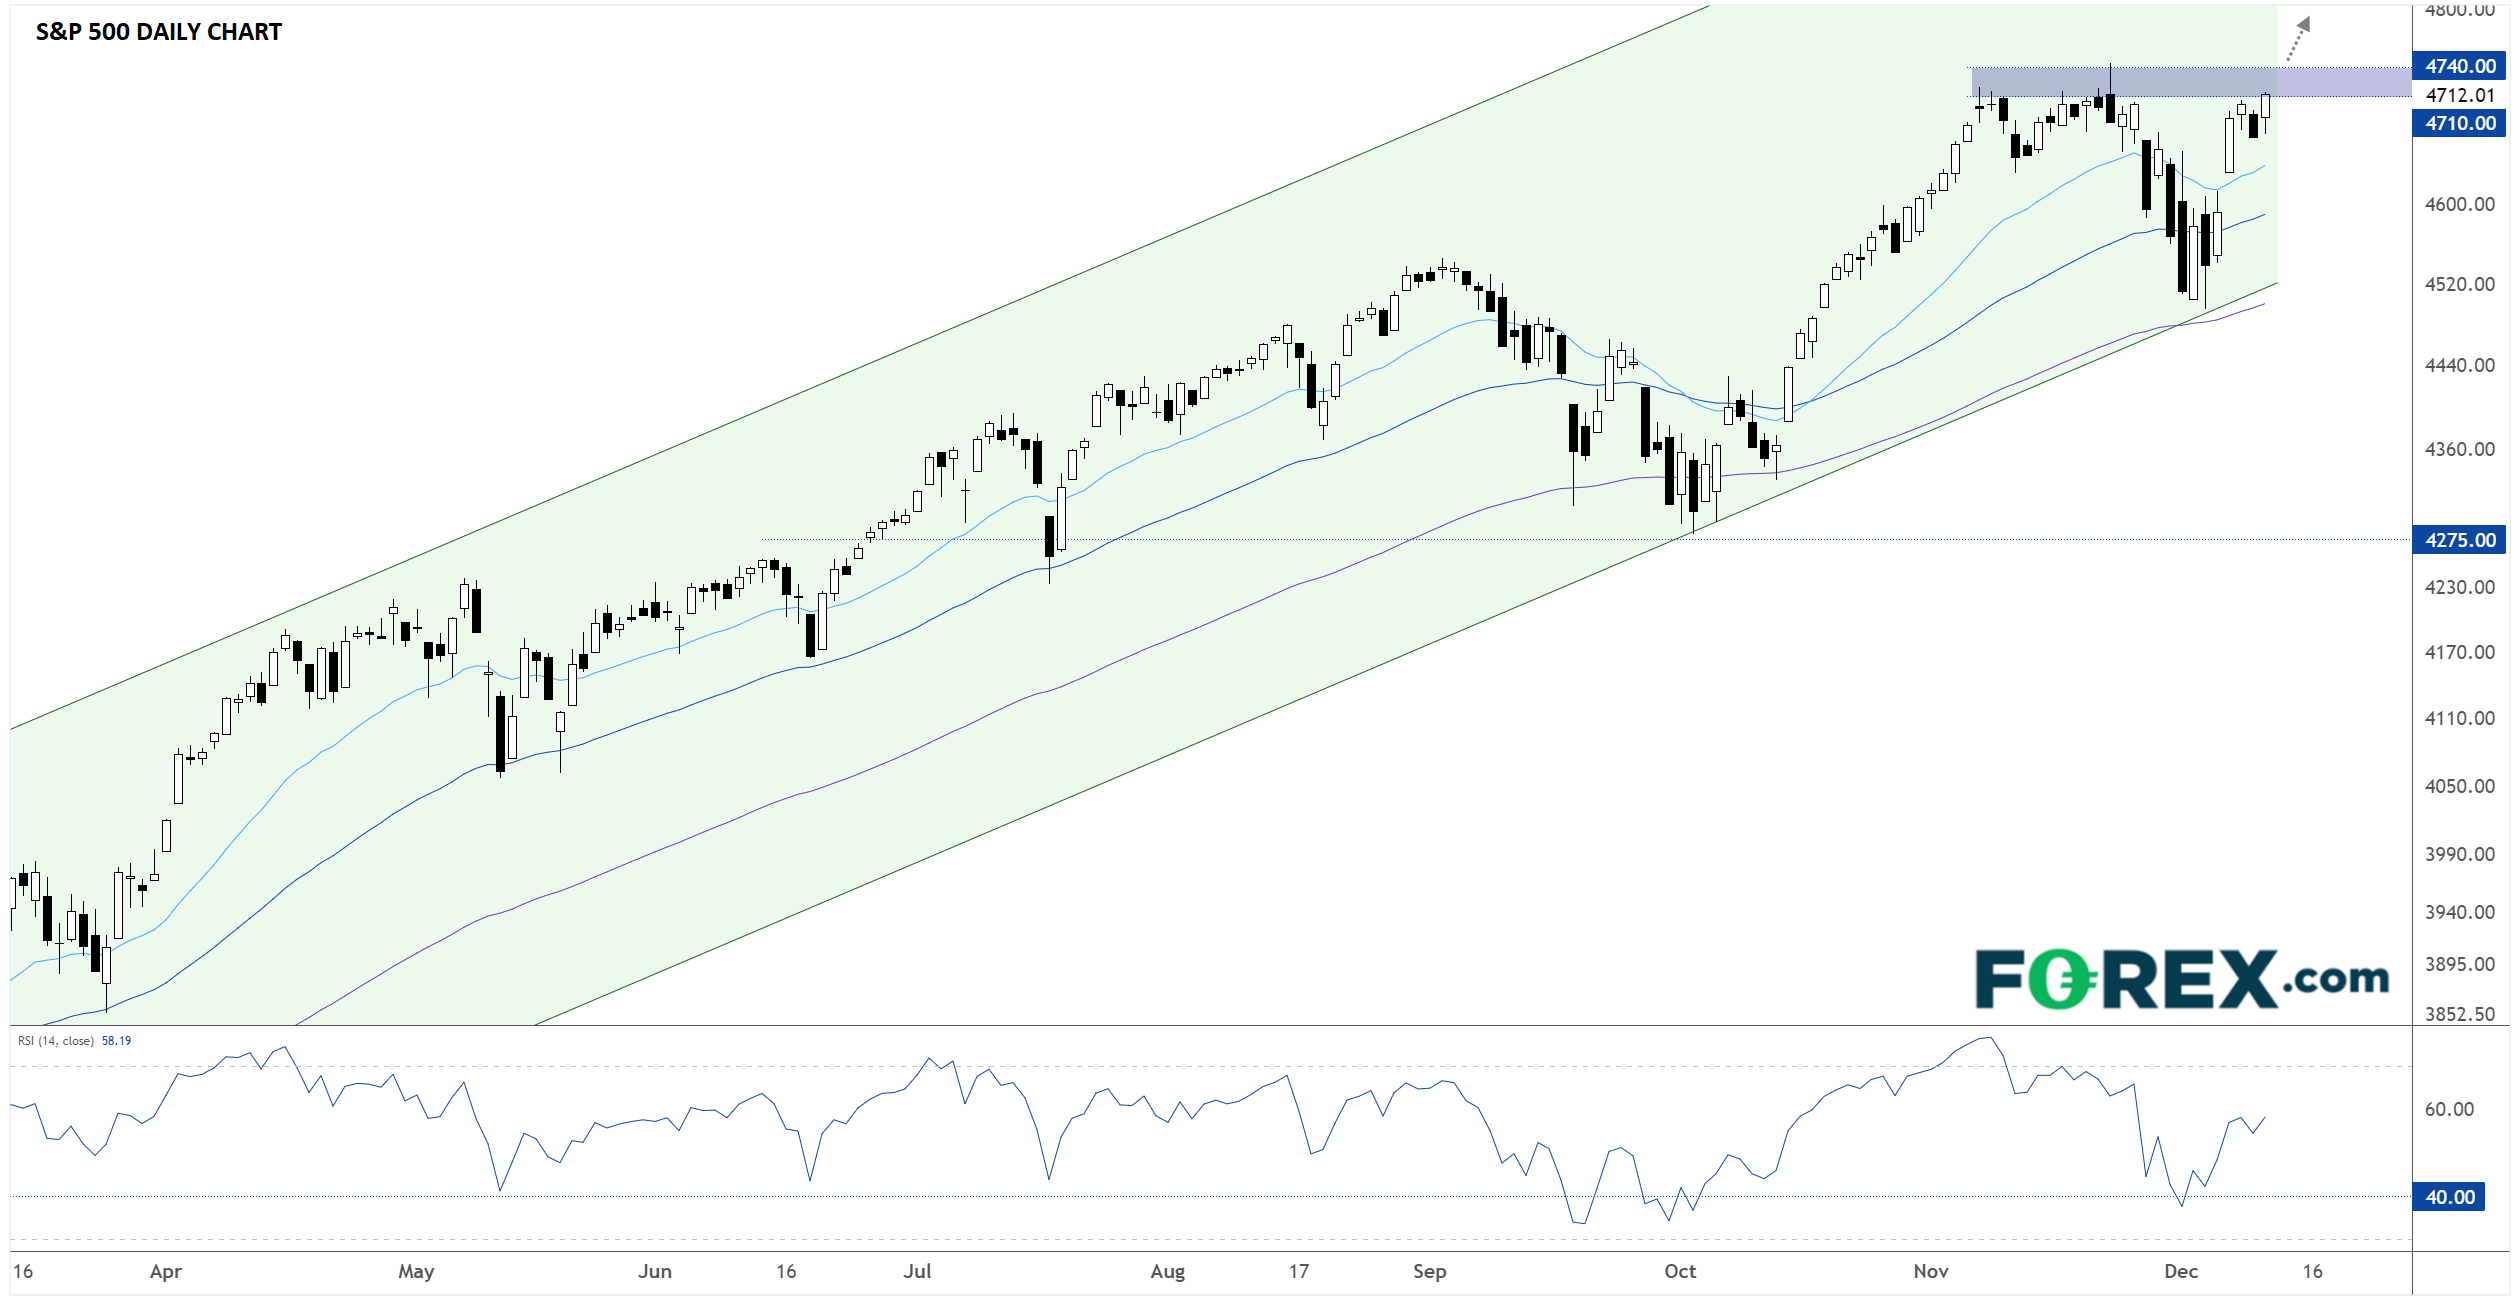
Source: TradingView, StoneX
FX: USD rises in otherwise quiet trade
The world’s reserve currency is the strongest of the majors heading into a US session with a barren economic calendar. After Friday’s relatively hot CPI report, most traders expect the Fed to accelerate its taper program later this week, a key step on the path to raising interest rates in the first half of next year. This, in turn, could underscore the widening monetary policy divergence between the US and Eurozone if the ECB hints at extending its asset purchases on Thursday.
- EUR/USD -0.25% at 1.1287
- GBP/USD -0.06% at 1.3259
Oil edges lower to start the week
Oil prices are ticking down nearly -1% to start the week after seeing its largest weekly gain since August last week on declining Omicron fears. Like most other major markets, oil is likely to take its cue from this week’s parade of central bank meetings before settling down as many traders leave their desks for the final two weeks of the year.
- WTI crude trades -0.8% at $71.35
- Brent trades -0.7% at $74.87
Looking ahead
- 17:30 GMT: BOE Governor Bailey speaks about the UK’s Financial Stability Report in London
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
US index futures
- Dow futures +0.0% at 35,891
- S&P futures +0.2% at 4713
- Nasdaq 100 futures +0.4% at 16,389
European indices
- FTSE -0.1% at 7,282
- DAX +0.9% at 15,771
- EURO STOXX +0.7% at 4227
Global risk appetite firms up heading into central bank bonanza
Market participants are feeling optimistic at the start of the week, with major indices in Europe rising and US stocks poised to open moderately higher and near record high territory, essentially erasing the turn-of-the-month drop on fears over a more aggressive Fed taper and the Omicron variant. Even news that the first UK patient died with the Omicron variant and that the country was preparing for a “tidal wave” of cases could not derail bulls’ sentiment. Yields on US Treasury bonds are also ticking lower, confirming the early strength in equity markets.
Looking ahead, this week’s market highlights will come from central bank pronouncements, with the most-watched gatherings taking place through the middle of the week, including monetary policy meetings from the Fed on Wednesday, as well as the BOE and ECB on Thursday.
See my colleague Joe Perry’s Week Ahead preview report for an overview of this week’s key events!
Where next for the S&P 500?
The widely-followed broad US index is set to open near record territory above 4,700, following a short-lived 4% pullback to end November. As any experienced trader will tell you, the trend is your friend when you’re trading using technical analysis, and in that vein, the path of least resistance remains to the topside for the S&P 500. If the index can confirm a close above 4,710 and ideally 4,740 this week, it would increase the odds of a year-end close above 4,800:

Source: TradingView, StoneX
FX: USD rises in otherwise quiet trade
The world’s reserve currency is the strongest of the majors heading into a US session with a barren economic calendar. After Friday’s relatively hot CPI report, most traders expect the Fed to accelerate its taper program later this week, a key step on the path to raising interest rates in the first half of next year. This, in turn, could underscore the widening monetary policy divergence between the US and Eurozone if the ECB hints at extending its asset purchases on Thursday.
- EUR/USD -0.25% at 1.1287
- GBP/USD -0.06% at 1.3259
Oil edges lower to start the week
Oil prices are ticking down nearly -1% to start the week after seeing its largest weekly gain since August last week on declining Omicron fears. Like most other major markets, oil is likely to take its cue from this week’s parade of central bank meetings before settling down as many traders leave their desks for the final two weeks of the year.
- WTI crude trades -0.8% at $71.35
- Brent trades -0.7% at $74.87
Looking ahead
- 17:30 GMT: BOE Governor Bailey speaks about the UK’s Financial Stability Report in London
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY forecast: US dollar strengths amid hawkish Fed despite recent oil weakness
The US dollar has extended its gains this morning, even if oil prices finished lower for the fifth consecutive day yesterday. Oil prices have bounced back in this first half of today’s session, causing a bit of pressure on currencies that rely on energy imports such as the euro, pound, Swiss franc, and Japanese yen. But it was the dollar that was exerting the most pressure, amid hawkish FedSpeak. Meanwhile, European indices and precious metals were also under a bit of pressure amid the strength of the dollar.

USD/JPY and USD/CHF Could Diverge as CHF/JPY Approaches Resistance
USD/JPY and USD/CHF retain bullish structures, but CHF/JPY resistance could expose a divergence between the two US dollar pairs.


EUR/AUD, GBP/AUD Outlook: Rates, risk and metals reinforce bearish technical case
EUR/AUD and GBP/AUD are coiling near support, with recent correlations suggesting the Aussie’s strength is being driven more by rates, risk and metals than energy.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.