



US open: Stocks rise and USD drops as core PCE cools
US stocks are rising, building on yesterday's strong gains after core PCE eased to 5% YoY, down from 5.2%.
Share this:

US futures
Dow futures +0.08% at 34590
S&P futures +0.23% at 4088
Nasdaq futures +0.23% at 12053
In Europe
FTSE -0.14% at 7579
Dax +0.7% at 14510
Personal spending rises, jobless claims fall
US stocks are set for a stronger start adding to impressive gains from the previous session. A less hawkish stance from Federal Reserve Chair Powell, combined with cooling core PCE has lifted stocks to significant levels.
The Dow Jones trades in a bull market, up 20% from its September low, while the S&P500 has pushed over the 200 sma moving average.
Yesterday Fed Chair Powell signaled that the US central bank would raise interest rates at a slower pace moving forwards, cementing expectations for a 50-basis point hike in December. Powell also said that the terminal rate would likely be above where it was forecast in September. The market didn’t pay much attention to this warning, it seems, as the Nasdaq soared 4%.
Today’s data is enough to keep the market happy that inflation is moving in the right direction. However, it is a small decline, highlighting that this is likely to be a long journey. Personal spending was also solid at 0.8%
Separately jobless claims were slightly lower than expected at 225k, down from 240k in the previous week.
Overall, the data is upbeat, showing that the economy is still holding up while inflation is cooling. If it continues like this, then a soft landing for the US economy could be likely.
US ISM manufacturing data is due shortly.
Elsewhere China is easing some lockdown restrictions, which is adding to the supportive mood towards equities.
Corporate news:
Kroger rises 3.2% pre-market after the supermarket chain raised the annual same-store sales forecast thanks to a steady demand for groceries and essentials.
Salesforce trades 7.1% lower pre-market after announcing that the co-chief executive would step down in January, raising uncertainty over future direction.
Where next for the Dow Jones?
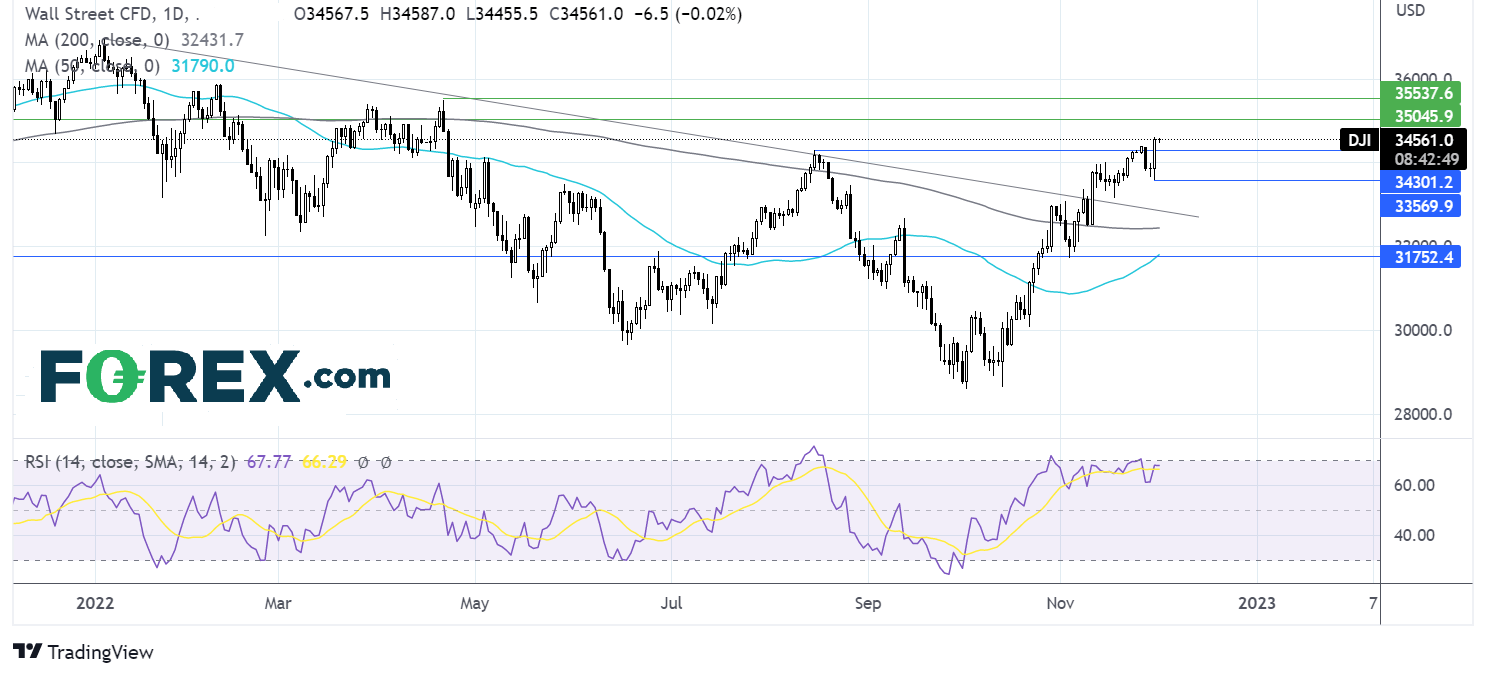
The Dow Jones rallied over 20% from its September low, rising above the 200 sma and resistance at 34300 the August high. The RSI supports further upside while it remains out of overbought territory. Buyers will be looking ahead to 35000 round number to extend gains to 35500 the April peak. On the downside, immediate support can be seen at 34300, with a break below here opening the door to 33570 the weekly low and 33000 round number.
FX markets – USD falls, EUR rises.
The USD is falling as inflation cools, supporting the Fed’s less hawkish stance.
EURUSD is rising, capitalizing on the weaker USD, despite disappointing data. German retail sales fell by more than forecast -2.8% MoM as surging energy costs reduce disposable income. Eurozone manufacturing PMI was also revised lower to 47.1.
GBP/USD is rallying hard across the board as it continues to stage an impressive recovery from the 1.0340 all time low in September. UK manufacturing OMI was upwardly revised to 46.5 in November. The pound trades at a 16-week high, boosted by Powell’s remarks, which appear to be driving flows out of the USD towards GBP. The pound his rising versus all its crosses
GBP/USD +1% at 1.2190
EUR/USD +0.39% at 1.0444
Oil rallies 7% so far this week
Oil prices are rising for a fourth straight day, trading up 7% so far this week. The latest leg higher comes as China eases lockdown restrictions in several major cities, raising the demand outlook, Fed Chair Powell talks down the US dollar, and as investors look ahead to the OPEC meeting this weekend.
There are some suggestions that as the OPEC meeting is now taking place virtually that another production cut is unlikely. “Sources “ also say that no cuts are expected. However, a further cut can’t be completely ruled out. OPEC+ has surprised the market in the past, and some of this recent rally could be explained by expectations of further cuts.
The prospect of a lower oil price cap is also supporting the market. The EU is slowly progressing towards a deal which is due to begin on Monday.
WTI crude trades +1.4% at $81.68
Brent trades at +1.3% at $88.05
Looking ahead
14:00 ISM Manufacturing PMI
15:45 ECB Lane speech
US futures
Dow futures +0.08% at 34590
S&P futures +0.23% at 4088
Nasdaq futures +0.23% at 12053
In Europe
FTSE -0.14% at 7579
Dax +0.7% at 14510
Learn more about trading indices
Personal spending rises, jobless claims fall
US stocks are set for a stronger start adding to impressive gains from the previous session. A less hawkish stance from Federal Reserve Chair Powell, combined with cooling core PCE has lifted stocks to significant levels.
The Dow Jones trades in a bull market, up 20% from its September low, while the S&P500 has pushed over the 200 sma moving average.
Yesterday Fed Chair Powell signaled that the US central bank would raise interest rates at a slower pace moving forwards, cementing expectations for a 50-basis point hike in December. Powell also said that the terminal rate would likely be above where it was forecast in September. The market didn’t pay much attention to this warning, it seems, as the Nasdaq soared 4%.
Today’s data is enough to keep the market happy that inflation is moving in the right direction. However, it is a small decline, highlighting that this is likely to be a long journey. Personal spending was also solid at 0.8%
Separately jobless claims were slightly lower than expected at 225k, down from 240k in the previous week.
Overall, the data is upbeat, showing that the economy is still holding up while inflation is cooling. If it continues like this, then a soft landing for the US economy could be likely.
US ISM manufacturing data is due shortly.
Elsewhere China is easing some lockdown restrictions, which is adding to the supportive mood towards equities.
Corporate news:
Kroger rises 3.2% pre-market after the supermarket chain raised the annual same-store sales forecast thanks to a steady demand for groceries and essentials.
Salesforce trades 7.1% lower pre-market after announcing that the co-chief executive would step down in January, raising uncertainty over future direction.
Where next for the Dow Jones?
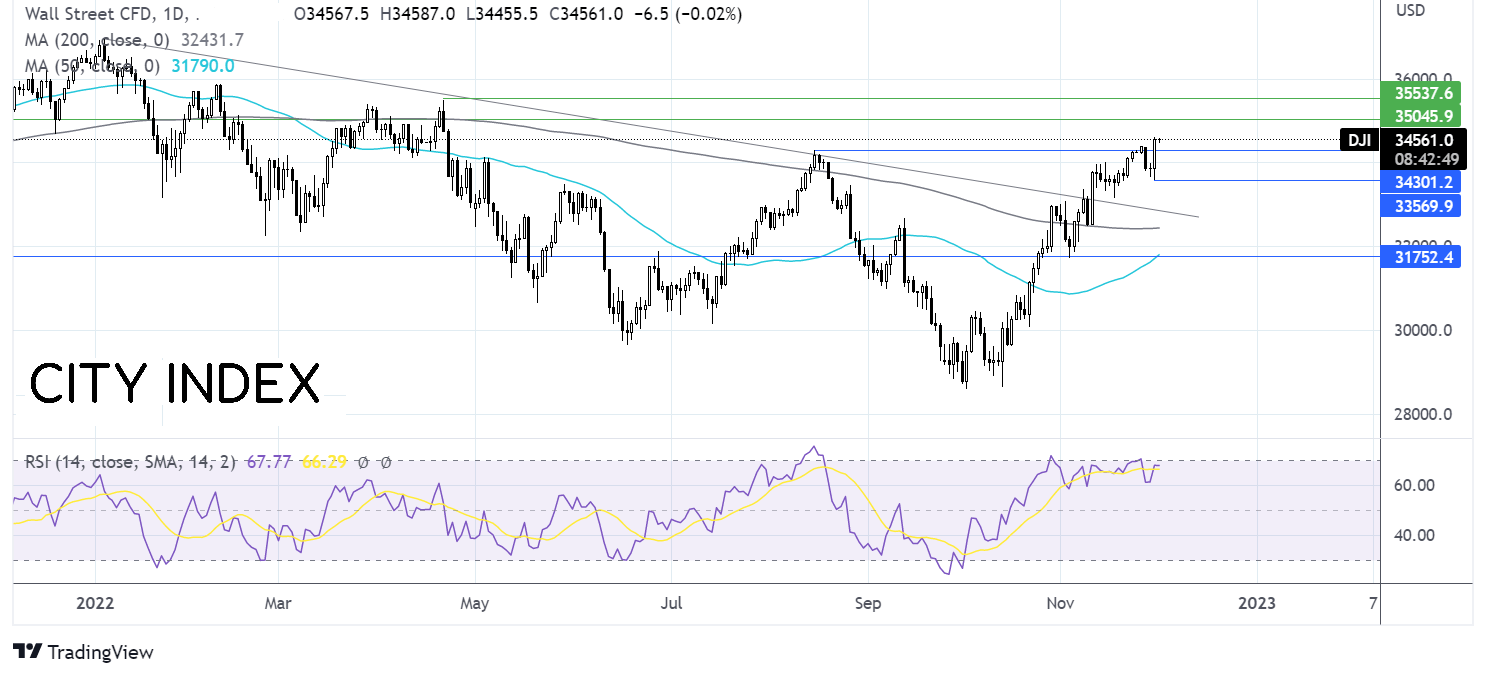
The Dow Jones rallied over 20% from its September low, rising above the 200 sma and resistance at 34300 the August high. The RSI supports further upside while it remains out of overbought territory. Buyers will be looking ahead to 35000 round number to extend gains to 35500 the April peak. On the downside, immediate support can be seen at 34300, with a break below here opening the door to 33570 the weekly low and 33000 round number.
FX markets – USD falls, EUR rises.
The USD is falling as inflation cools, supporting the Fed’s less hawkish stance.
EURUSD is rising, capitalizing on the weaker USD, despite disappointing data. German retail sales fell by more than forecast -2.8% MoM as surging energy costs reduce disposable income. Eurozone manufacturing PMI was also revised lower to 47.1.
GBP/USD is rallying hard across the board as it continues to stage an impressive recovery from the 1.0340 all time low in September. UK manufacturing OMI was upwardly revised to 46.5 in November. The pound trades at a 16-week high, boosted by Powell’s remarks, which appear to be driving flows out of the USD towards GBP. The pound his rising versus all its crosses
GBP/USD +1% at 1.2190
EUR/USD +0.39% at 1.0444
Oil rallies 7% so far this week
Oil prices are rising for a fourth straight day, trading up 7% so far this week. The latest leg higher comes as China eases lockdown restrictions in several major cities, raising the demand outlook, Fed Chair Powell talks down the US dollar, and as investors look ahead to the OPEC meeting this weekend.
There are some suggestions that as the OPEC meeting is now taking place virtually that another production cut is unlikely. “Sources “ also say that no cuts are expected. However, a further cut can’t be completely ruled out. OPEC+ has surprised the market in the past, and some of this recent rally could be explained by expectations of further cuts.
The prospect of a lower oil price cap is also supporting the market. The EU is slowly progressing towards a deal which is due to begin on Monday.
WTI crude trades +1.4% at $81.68
Brent trades at +1.3% at $88.05
Learn more about trading oil here.
Looking ahead
14:00 ISM Manufacturing PMI
15:45 ECB Lane speech
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Technical Outlook: DXY Bulls Meet Resistance at Yearly Highs 10 1 2026
The U.S. Dollar has held firm despite fading Fed hike bets, but Friday’s payrolls could test the rally’s staying power.


Dow Jones forecast: Stock markets under pressure from multiple sources
When looking at the major tech-heavy US indices like the S&P 500 or the Nasdaq 100, you wouldn’t think that the stock market is particularly weak. Yet, beneath the surface, the market is far from healthy right now. Investors are evidently just piling into the big tech and AI names, and as a result, market breadth is deteriorating. Other indices like the small cap Russell 2000 and the Dow Jones are starting to reflect that weakness.


Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.