



USD/JPY weekly forecast: Suspected rate check revives intervention threat
A hawkish Fed, a dovish BOJ hike and a suspected rate check have left USD/JPY caught between powerful rates support and renewed intervention risk.
Share this:
- USD/JPY posts its strongest weekly gain since October 2025
- Five-day correlation with US two-year yields surges to +0.98
- Suspected rate check near 158 revives intervention risk
- Five-day Japan holiday stretch leaves intervention risk elevated
- Yen positioning records its largest three-week reversal on record
A hawkish Federal Reserve and a tough hawkish bar for the Bank of Japan to clear helped USD/JPY post its largest weekly advance since October 2025, sending the pair more than five big figures off the lows tagged earlier this month.
However, the speed of the rebound leads us to the greatest risk traders may have to navigate in the week ahead. With a prolonged holiday period in Japan and a suspected rate check from Japanese authorities on Friday, the risk of renewed intervention activity will be elevated, particularly early in the week.
Outside of that threat, a thin economic calendar suggests Fed speak and gyrations in energy prices may be the biggest influences on the pair as we head towards month-end.
Rates correlation snaps back hard
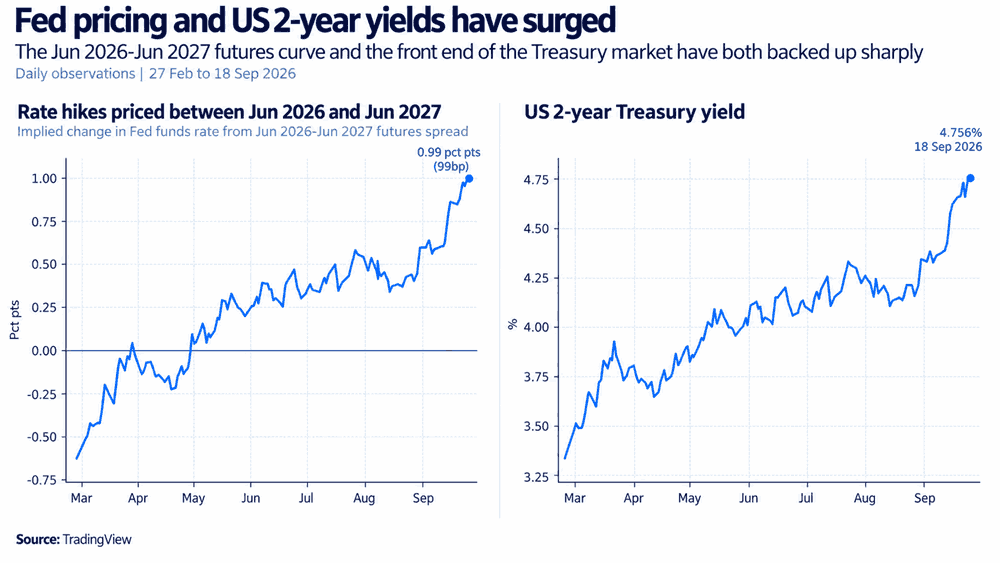
The story of last week was an abrupt hawkish shift in front-end US rates, which saw markets move to pricing the risk of another three rate increases from the Federal Reserve by June next year. That sent yields further out the curve sharply higher, with two-year yields hitting 4.76%, providing a powerful tailwind for the dollar.
Source: TradingView
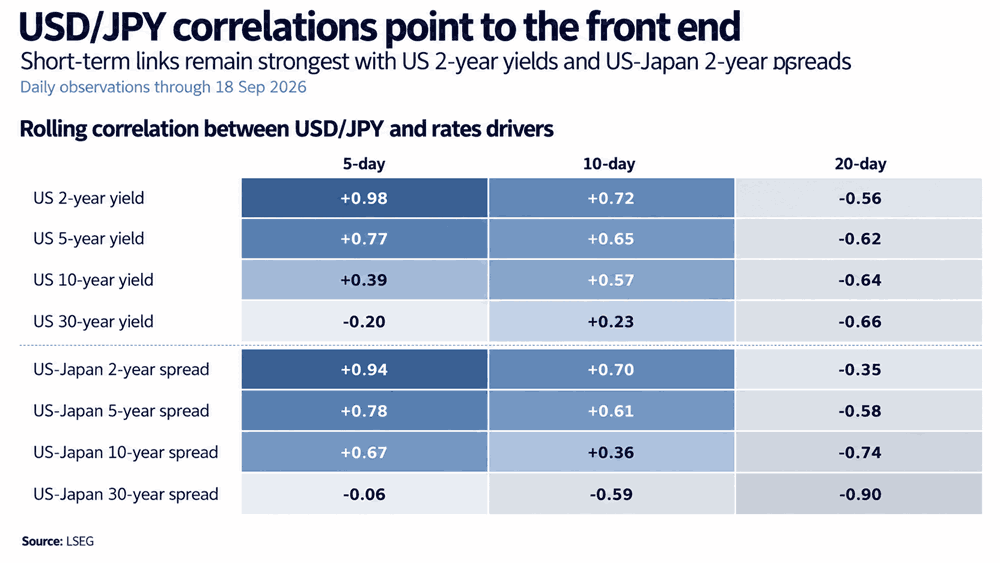
You can see how important that shift in front-end US rates was to USD/JPY last week by looking at the matrix below. Over the past five sessions, the correlation with US two-year yields has risen to +0.98, an extremely rare positive relationship going back decades. You can also see that relationship has been gradually strengthening again after the unusual disconnection with US rates seen during the intervention episodes of late July and early August.
Source: LSEG
However, as seen in the strong relationship between US-Japan two-year yield spreads and USD/JPY, Japanese-specific factors can and still do influence the pair, as witnessed firsthand on Friday.
While the Bank of Japan lifted overnight rates to 1.25%, the highest level in more than three decades, the hike was perceived to be a dovish one, with two dissenters in favour of holding rates steady and mixed messaging from Governor Ueda during his press conference sending the yen sharply lower against all major currency pairs.
Intervention risk returns to centre stage
But that move may have sown the seeds of what looms as potentially the biggest threat for traders to navigate in the week ahead: renewed intervention activity, either from the Bank of Japan or the US Treasury.
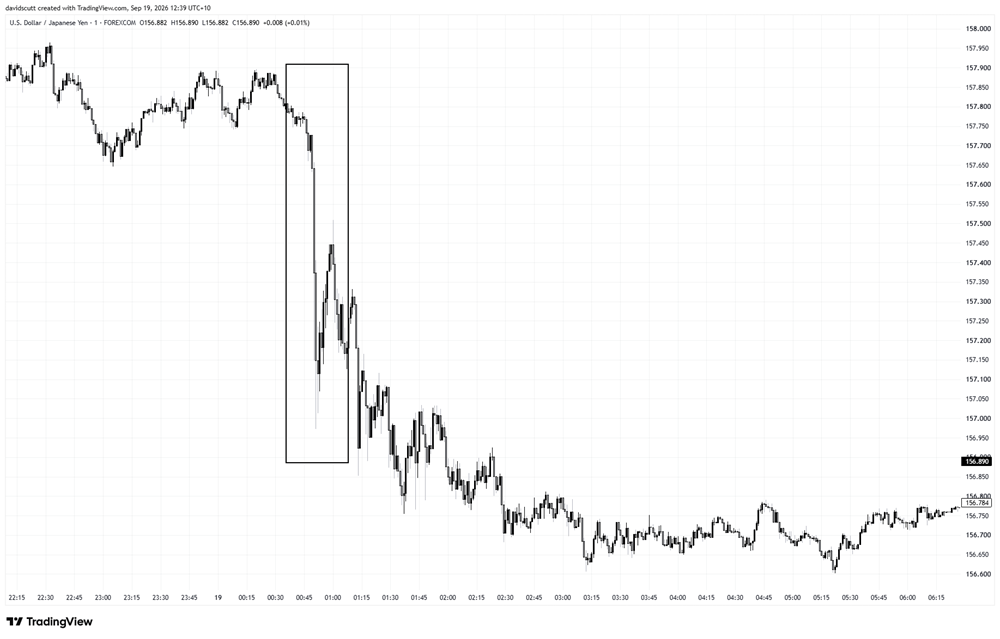
During the North American session on Friday, after USD/JPY had just tagged 158, the pair suddenly dropped by more than 75 pips in little more than a few minutes, reacting to what was a suspected rate check from Japanese authorities, something that is often used as a forewarning about imminent intervention.
Source: TradingView
The timing was telling, coming ahead of a five-day long weekend in Japan where market liquidity will be extremely thin, providing an ideal environment for either Japanese or US authorities to get more bang for their buck should they choose to intervene to support the yen.
While recent intervention episodes have not tended to arrive during Japanese holiday periods, that does not dismiss the risk, particularly in the wake of Friday’s move.
Light calendar leaves focus elsewhere
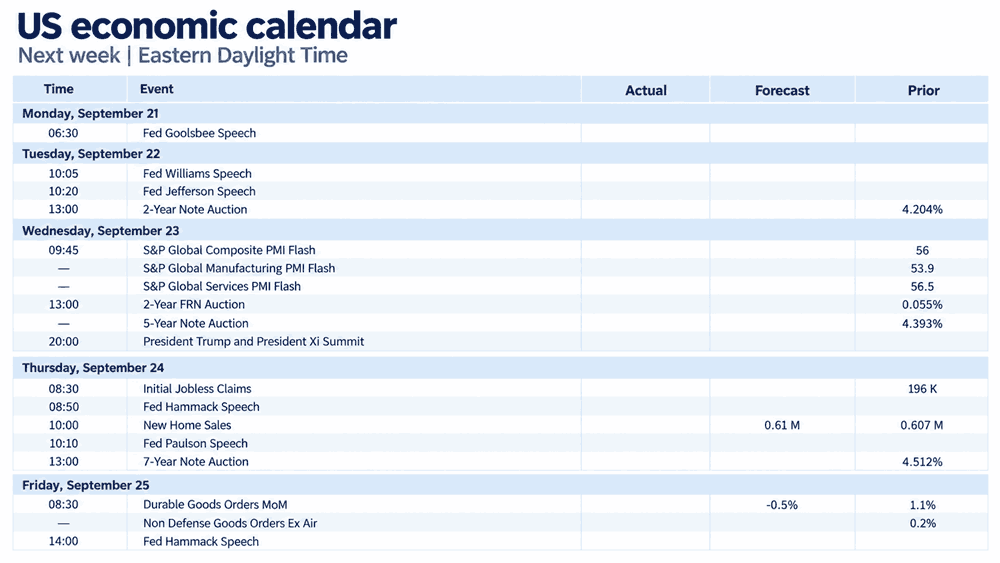
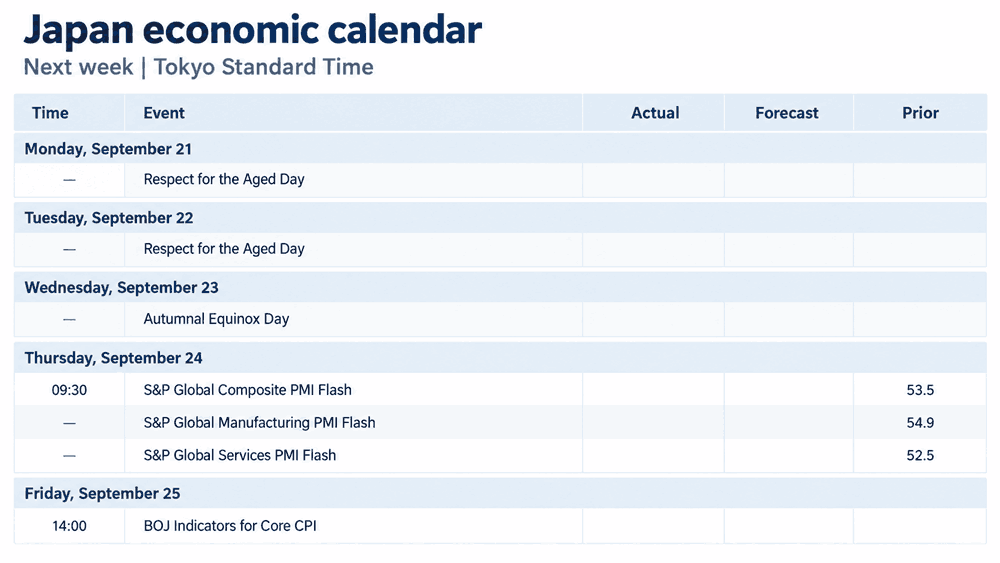
Beyond intervention risk, both the US and Japanese calendars are devoid of any market-moving top-tier releases, leaving Fed speak as the most likely candidate to shift both front-end US pricing and USD/JPY.
Source: TradingView
Of the Fed speakers scheduled, New York Fed President John Williams on Tuesday is the one I’m paying closest attention to. Williams often comes across as one of the more dovish members on the FOMC, and as a permanent voter and president of the New York Fed, his comments can move markets. Any pushback against the hawkish shift in market pricing may take some of the heat out of the US dollar.
The summit scheduled between Donald Trump and Chinese President Xi Jinping later in the week will dominate the headlines, although my experience with these events is that they rarely deliver meaningful market volatility. There’s always the risk of some unexpected geopolitical tension, particularly given some of the topics that will be discussed, but it’s far more likely to be a display of pageantry than anything meaningful for markets.
Source: TradingView
In Japan, the only release of note is the Bank of Japan’s inflation measure on Friday that strips out the influence of government subsidies. While the data is for August, making it slightly dated, it will give markets a cleaner view on underlying price pressures as they assess whether another three rate increases by the middle of next year is plausible.
Outside of known risk events, given the linkages we’ve seen recently between crude prices, US yields and the US dollar, movements in energy markets may also be influential on the pair at the margin.
Technical picture turns more balanced
Source: TradingView
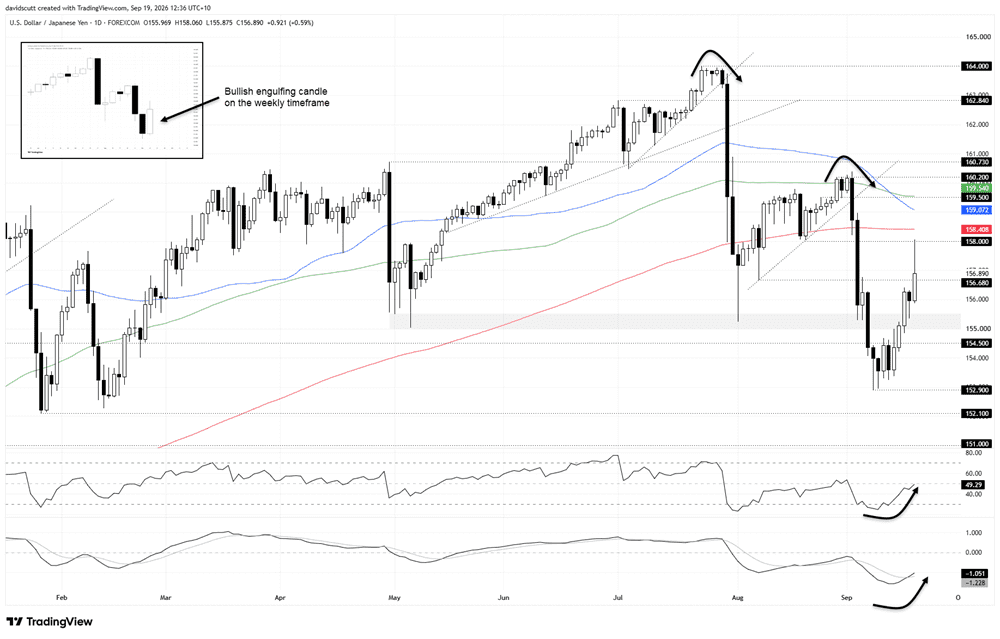
Turning to technicals, we saw a bullish engulfing candle print last week, warning of a potential turning point for USD/JPY, with the merits of the signal strengthened by its arrival after a prolonged downtrend.
However, the caveat on that view, and it is a very big caveat, is the ongoing threat of intervention early in the week. With thin conditions likely throughout Monday, Tuesday and Wednesday, I’ll be paying extra scrutiny to price action when assessing the merits of potential setups.
While directional risks look far more balanced at this stage, the broader trend is still one of lower highs and lower lows, suggesting the bears still marginally have the ascendancy. That view is backed up by the fact the pair remains beneath its key medium and long-term moving averages, with the 50 and 100-day averages now carrying a negative slope.
The oscillators suggest momentum is now neutral when it comes to directional risk, with RSI (14) nearing 50 and MACD staging a bullish crossover of the signal line, albeit in negative territory.
Given the mixed messages, price action around known levels may be more instructive on how to proceed. Key levels to watch above include 158, which previously acted as support before flipping to offering resistance on Friday, with the 200-day moving average and its 50-day equivalent found at 158.41 and 159.07 respectively.
As for downside levels, 156.68 was the low set on August 7, which then flipped to offering resistance earlier this month. Even though it’s only a minor level, it’s the first one of note underneath where the pair now trades.
Beneath that is a far more pronounced support zone running from 155.50 down to 155, where the pair bounced strongly on several occasions this year following intervention episodes. 154.50 and the September 8 swing low of 152.90 are other levels to watch.
Yen positioning undergoes historic reversal
Source: LSEG
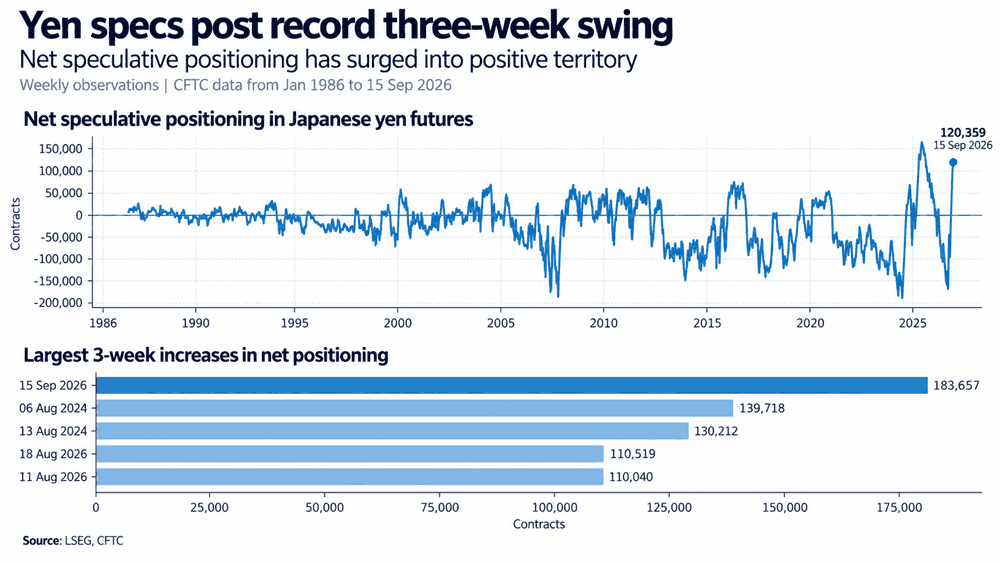
Perhaps contributing to the prior downswing in the pair seen in early September, latest data released by the CFTC in its COT report on Friday revealed another substantial increase in net speculative long Japanese yen positioning, with the three-week change now the largest on record going back to when the series was first published in the late 1980s.
At 183,657 contracts, the reversal dwarfed anything seen previously. While this is only futures positioning and not the broader market, it suggests widespread short covering likely drove a substantial part of the unwind in USD/JPY.
With net long yen positioning now elevated, the downside risks that were previously evident from sizeable short positioning may now have largely run their course, potentially leaving directional risks more balanced from a positioning perspective as well.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
AUD/USD enters Q4 with RBA and Fed hikes in focus as sticky inflation, rising unemployment and US dollar strength shape the Australian dollar.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.