




Vodafone returns to two bar growth
Rebounding service revenues justify giving Vodafone the benefit of the doubt, for now
Share this:

Rebounding service revenues and some turnarounds in Europe justify a medium-term benefit of the doubt
Organic rebound in context
Vodafone’s return to organic service revenue growth is the biggest relief in H1 results. The 0.7% year-on-year rise in the second quarter compares with 0.2% expected and more than erases Q1’s 0.2% decline. A sequential rebound leaves +0.3% on a half-year basis, pointing to a turnaround in Vodafone’s most important measure of revenues following two quarters of shrinking sales. Strengthening key sales on the back of improvements in some of Vodafone’s most troubled regions—South Africa, Spain and Italy—together with the best ever quarter for new UK customers have enabled a mild outlook upgrade.
Guidance signal
Adjusted Ebitda is now seen at €14.8bn-€15bn in the 2020 financial year compared with €13.8bn-€14.2bn before. Though the new forecast includes an €800m one-off boost from the purchase of some Liberty Global assets and the disposal of New Zealand operations, the midpoint of the new range is still €100m higher excluding those benefits. In effect, guidance is tightened with a slight shift to the higher end. It’s the most confident signal on guidance from Vodafone in the current financial year. CEO Nick Read duly confirmed that revenue growth is expected to continue through the remainder of the year in both Europe and Africa.
Tweak tempers relief
Investor relief has been evident in the stock’s rise of as much as 3.2%. As outlined in our preview, stabilisation of trouble spots like Spain, Italy and South Africa was necessary to safeguard underlying earnings goals, which were already lower than the year before. In turn, cash flow generation is critical for the dividend outlook after investors were forced to swallow a ‘rebase’ with an eye to lower debt and striking a better balance on spectrum costs and investments. Free cash flow guidance has been tweaked to “around” €5.4bn from “at least” €5.4bn. Although Vodafone shares pared their initial jump to a 2.3% gain by late morning, investors appear to have given Nick Read the benefit of the doubt on free cash flow goals. Greater clarity on earnings guidance helps.
Vodafone Idea still messy
The earnings guidance signal may even have encouraged the market to overlook persisting value destruction from Vodafone’s burdensome business in India. A €1.9bn loss was recorded for jointly owned Vodafone Idea with fierce competition exacerbated by a Supreme Court ruling. The UK group has struck some proceeds from the venture out from guidance whilst “financial relief” is sought from the government there. The update from India wasn’t as dire as feared by some investors, who suggested a write down of some €1bn was possible. Still, overall relief for the region remains some way off, providing ample room for critics who suspect Indian assets may eventually become worthless.
Germany, UK also stuck
Vodafone’s weak ‘coverage’ areas closer to home also remain evident, with a 1.4% H1 contraction in Europe, albeit that was still an improvement. Low margin wholesale businesses and stagnation in the mature markets of Germany and UK respectively look as intractable as ever. As such, some of Tuesday’s share fade is likely tied to medium-term prospects that may only have improved moderately, despite a relatively successful first half.
Stock price outlook
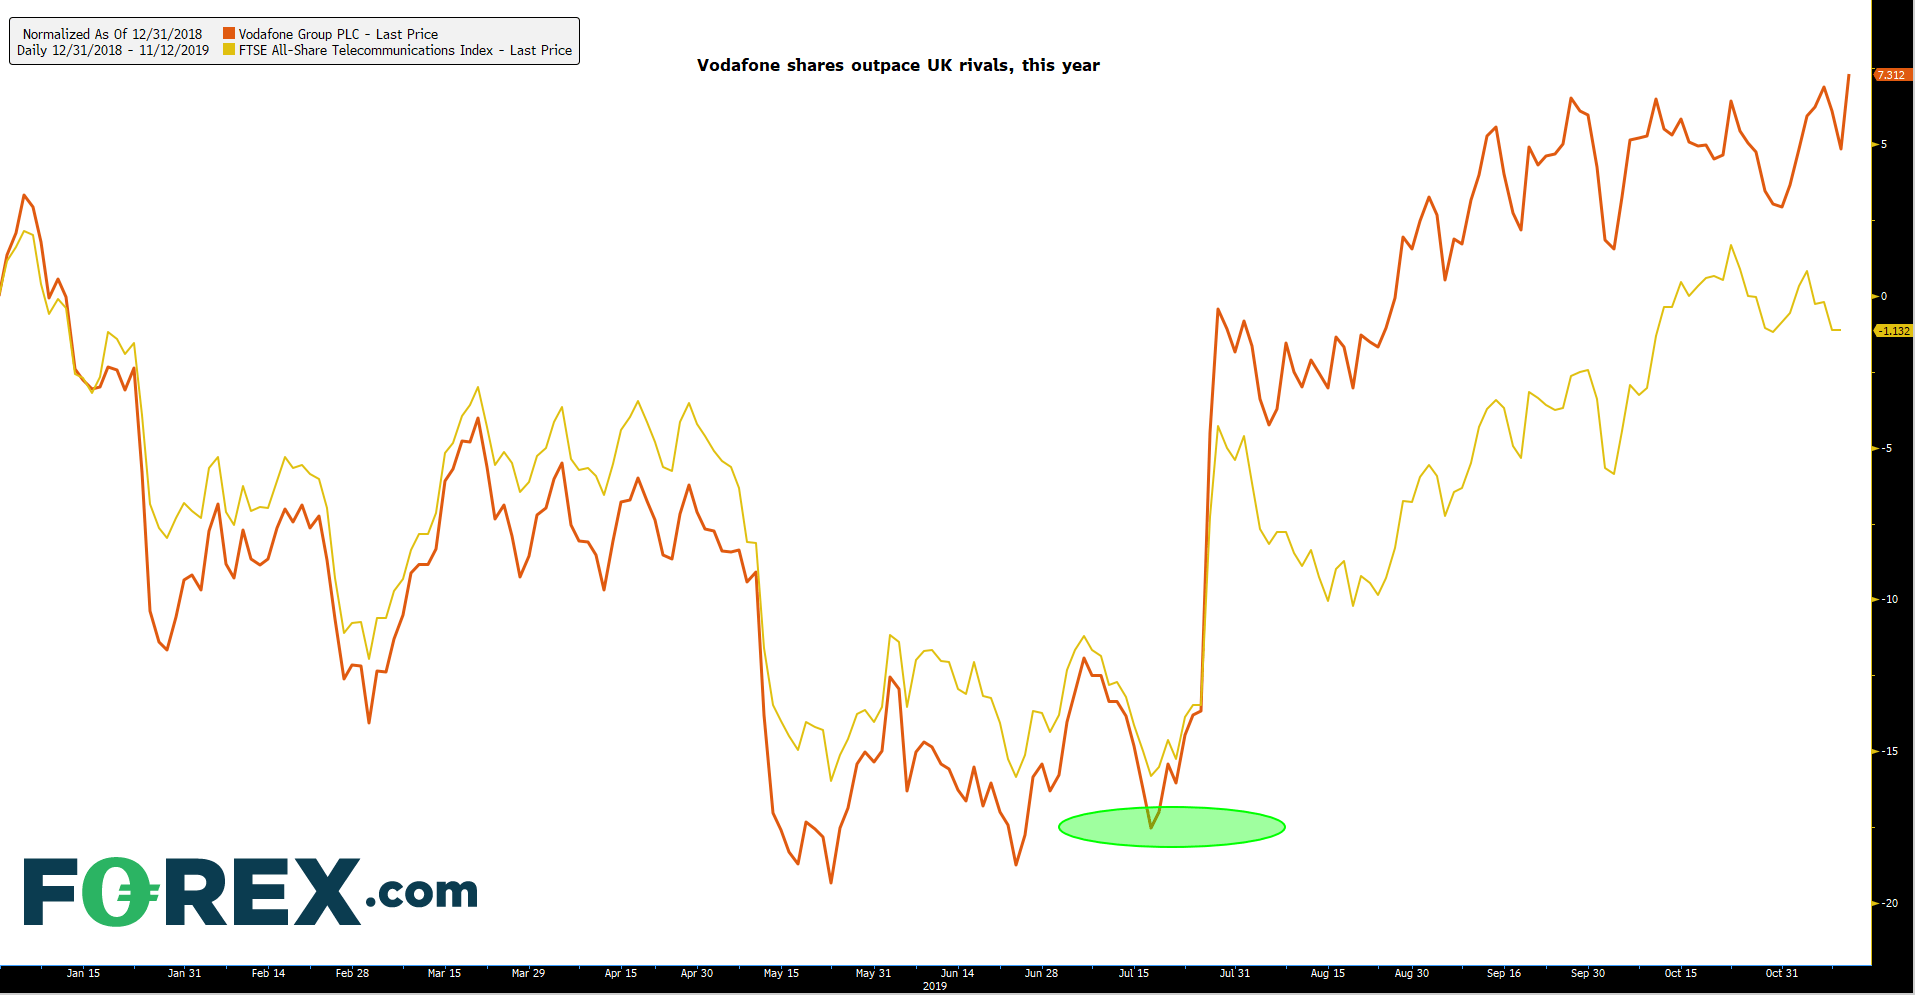
VOD shares have bounced from a 20% slump into the middle of the year to trade 7% higher so far in 2019. Latest results imply reduced impediments for the stock to recoup further into the year end. Still, the odds are better for steady rather than spectacular upside progress as VOD extends a mild outperformance of the UK sector. With shares now better underpinned, VOD’s total return of around 18.3 times now looks far more palatable relative to FTSE ALL-Share telecom peers’ trading on 18.4 x. Closing of the gap implies improved VOD stability ahead, so long as revenue, earnings and cash prospects remain on track.
Normalised: Vodafone Group Plc. / FTSE All-Share Telecommunications Index – year to date
Source: Bloomberg/FOREX.com
Rebounding service revenues and some turnarounds in Europe justify a medium-term benefit of the doubt
Organic rebound in context
Vodafone’s return to organic service revenue growth is the biggest relief in H1 results. The 0.7% year-on-year rise in the second quarter compares with 0.2% expected and more than erases Q1’s 0.2% decline. A sequential rebound leaves +0.3% on a half-year basis, pointing to a turnaround in Vodafone’s most important measure of revenues following two quarters of shrinking sales. Strengthening key sales on the back of improvements in some of Vodafone’s most troubled regions—South Africa, Spain and Italy—together with the best ever quarter for new UK customers have enabled a mild outlook upgrade.
Guidance signal
Adjusted Ebitda is now seen at €14.8bn-€15bn in the 2020 financial year compared with €13.8bn-€14.2bn before. Though the new forecast includes an €800m one-off boost from the purchase of some Liberty Global assets and the disposal of New Zealand operations, the midpoint of the new range is still €100m higher excluding those benefits. In effect, guidance is tightened with a slight shift to the higher end. It’s the most confident signal on guidance from Vodafone in the current financial year. CEO Nick Read duly confirmed that revenue growth is expected to continue through the remainder of the year in both Europe and Africa.
Tweak tempers relief
Investor relief has been evident in the stock’s rise of as much as 3.2%. As outlined in our preview, stabilisation of trouble spots like Spain, Italy and South Africa was necessary to safeguard underlying earnings goals, which were already lower than the year before. In turn, cash flow generation is critical for the dividend outlook after investors were forced to swallow a ‘rebase’ with an eye to lower debt and striking a better balance on spectrum costs and investments. Free cash flow guidance has been tweaked to “around” €5.4bn from “at least” €5.4bn. Although Vodafone shares pared their initial jump to a 2.3% gain by late morning, investors appear to have given Nick Read the benefit of the doubt on free cash flow goals. Greater clarity on earnings guidance helps.
Vodafone Idea still messy
The earnings guidance signal may even have encouraged the market to overlook persisting value destruction from Vodafone’s burdensome business in India. A €1.9bn loss was recorded for jointly owned Vodafone Idea with fierce competition exacerbated by a Supreme Court ruling. The UK group has struck some proceeds from the venture out from guidance whilst “financial relief” is sought from the government there. The update from India wasn’t as dire as feared by some investors, who suggested a write down of some €1bn was possible. Still, overall relief for the region remains some way off, providing ample room for critics who suspect Indian assets may eventually become worthless.
Germany, UK also stuck
Vodafone’s weak ‘coverage’ areas closer to home also remain evident, with a 1.4% H1 contraction in Europe, albeit that was still an improvement. Low margin wholesale businesses and stagnation in the mature markets of Germany and UK respectively look as intractable as ever. As such, some of Tuesday’s share fade is likely tied to medium-term prospects that may only have improved moderately, despite a relatively successful first half.
Stock price outlook
VOD shares have bounced from a 20% slump into the middle of the year to trade 7% higher so far in 2019. Latest results imply reduced impediments for the stock to recoup further into the year end. Still, the odds are better for steady rather than spectacular upside progress as VOD extends a mild outperformance of the UK sector. With shares now better underpinned, VOD’s total return of around 18.3 times now looks far more palatable relative to FTSE ALL-Share telecom peers’ trading on 18.4 x. Closing of the gap implies improved VOD stability ahead, so long as revenue, earnings and cash prospects remain on track.
Normalised: Vodafone Group Plc. / FTSE All-Share Telecommunications Index – year to date
Source: Bloomberg/City Index
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
GBP/USD, Dow Jones Forecast: Key Technical Scenarios to Watch
GBP/USD and the Dow Jones are approaching critical technical levels amid earning optimism, Fed rate hike expectations, US-Iran developments, and persistent geopolitical risks.

The U.S. Dollar Is Rising Again and Nasdaq Is Feeling It
Nasdaq, the U.S. Dollar Index and Federal Reserve expectations are driving market sentiment ahead of a pivotal FOMC meeting. Razan Hilal, StoneX Market Analyst, explains how rising expectations for a hawkish Federal Reserve, persistent U.S.-Iran tensions and key technical levels on the U.S. Dollar Index could influence currencies, equities and precious metals in the weeks ahead.
US Dollar and Nasdaq Forecast: Fed, Microsoft, Meta, and Iran Talks in Focus
The US Dollar Index (DXY) continues to hold above the 101.00 mark, reinforcing its bullish structure, while the Nasdaq remains capped below the 29,000 resistance and its June-July consolidation range, reflecting cautious risk appetite ahead of the Federal Reserve's policy decision and major earnings releases on Wednesday.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.