







weekly technical outlook on major stock indices 16 jan to 20 jan sp 500 is the potential last fort s
<p>S&P 500 –Potential last push up into major risk zone (Click to enlarge charts) Key Levels (1 to 3 weeks) Pivot (key support): 2257/54 Resistances: […]</p>
Share this:

S&P 500 –Potential last push up into major risk zone
Key Levels (1 to 3 weeks)
Pivot (key support): 2257/54
Resistances: 2303 & 2326/35
Next supports: 2214 & 2178
Medium-term (1 to 3 weeks) Outlook
Last week, the U.S. S&P 500 Index (proxy for the S&P 500 futures) has challenged the 2257 medium-term pivotal support (printed a low of 2254 on 13 January 2017) before it does an intraday upside revival towards the 2270 handle aided by the Financials, Technology and Consumer Discretionary sectors (click here for a recap on our prior weekly technical outlook).
Q4 2016 U.S. earnings session kick started on last Friday, 13 January 2016 with 2 major Financials; Bank of America (BAC) and JP Morgan (JPM) that had managed to beat expectations (0.40 EPS versus 0.38 EPS consensus for BAC and 1.71 EPS versus 1.42 EPS consensus for JPM). The better than expected earnings numbers of these Financials help the to put a “floor” on the S&P 500 as the whole Financial sector recorded a gain of 0.56% which surpassed the S&P 500’s return of 0.19% seen on last Friday, 13 January 2016.
This coming week, we will continue to see a bulk of major Financials Q4 earnings releases as follow:
- 17 January (Tues) – Morgan Stanley (MS), 0.65EPS consensus
- 18 January (Wed) – Citigroup (C), 1.12EPS consensus
- 18 January (Wed) – Goldman Sachs (GS), 4.80EPS consensus
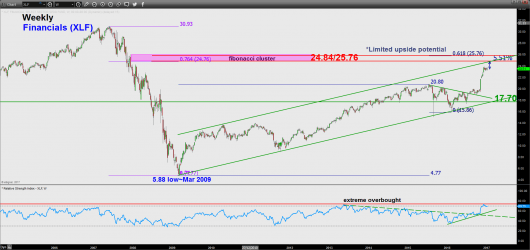
Technically, the Financials (XLF) ETF still shows room for a further potential upside of 5.6% from last Friday, 13 January 2017 close price of 23.51 towards its major key resistance zone of 24.84/25.76 (refer to the 3rd chart). Therefore, it is likely to provide the “ammunition” for a further potential push up on the S&P 500 towards the 2326/35 major key resistance as we head into Inauguration Day of the 45th U.S. President on Friday, 20 January 2017.
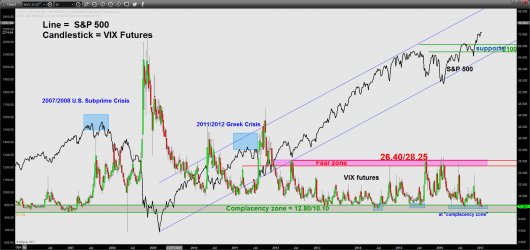
But do be cautious now as we are in the potential tail end of the “melt-up” phase that is in place since 11 February 2016 before a potential severe correction sets in where we have stressed in our recent Q1 2017 Global Markets Outlook. One of the ominous signs is the VIX futures where it has continued to trade downwards and headed into the complacency zone” of 12.80/10.10 which suggests that market participants are now in an overstretched “risk-on” mode where a slight negative “shock” can cause a potential disorderly unwinding of long positions in equities (refer to the 4th chart).
Therefore, we are maintaining our bullish bias for a potential last push up towards 2303 follow by the lower limit of the major key resistance/risk zone at 2326/35 holding above the 2257/54 medium-term pivotal key support.
However, failure to hold above 2257/54 may invalidate the preferred bullish scenario to see the start of the pronounced correction to test the next supports at 2214 and 2178 in the first step.
Nikkei 225 – Major top may have been formed

Key Levels (1 to 3 weeks)
Pivot (key resistance): 19520
Supports: 18930, 18600 & 18230
Next resistance: 19860/20000
Medium-term (1 to 3 weeks) Outlook
The Japan 225 Index (proxy for the Nikkei 225 futures) has broken below the 19330 medium-term pivotal support and invalidated the “last push up” scenario towards the key major resistance zone of 19860/20000 (click here for a recap on our prior weekly technical outlook).
In our previous reports since the start of 2017, we have cautioned that any potential push up in the Index is likely to be “residual” in nature as it is approaching a major resistance/risk zone of 19860/20000 where a potential correction can materialised. Last week’s price action of the Index has reinforced our longer-term bearish view with the latest negative elements as follow:
- The daily RSI oscillator has traced a bearish divergence signal (not seen in the last three months) and it is now challenging the significant trendline support in place since February 2016. These observations suggest that upside momentum has deteriorated and price action of the Index is likely to see a major bearish reversal.
- Price action of the Index has also traced out a bearish “Double Top” configuration with its neckline support at 18930.
- Intermarket analysis- the USD/JPY which has a direct correlation with the movement of the Nikkei 225 is now being capped by a long-term descending trendline in place since April 1990 which also confluences with the key long-term resistance at 119.80. Therefore, any potential up movement on the USD/JPY seems to be capped at this juncture which translates to limited upside potential in the Nikkei 225 (refer to the 3rd chart).
- Elliot Wave Principal and fractal analysis – The impulsive bullish up move in place since 24 June 2016 is likely to have seen a potential primary major top (wave 5/ of (C) B) with a Fibonacci cluster at the 19700 zone.
Therefore, as long as the 19520 medium-term pivotal resistance is not surpassed, the Index may see a bearish breakdown below 18930 (neckline of the “Double Top”) to target the next supports at 18600 before 18230 next.
On the other hand, a clearance above 19520 is likely to negate the preferred bearish view to revive the “squeeze up” scenario towards the 19860/20000 major key resistance zone.
Hang Seng Index - Failed to break above 23100 major key resistance for the 3rd time

Key Levels (1 to 3 weeks)
Pivot (key resistance): 22950/23100
Supports: 22460 & 22060/21920
Next resistance: 24100
Medium-term (1 to 3 weeks) Outlook
The Hong Kong 50 Index (proxy for Hang Seng Index futures) has staged the “last push up” as expected and hit the lower limit of our expected upside target zone of 22950/23100 (printed a high of 22977 on 12 January 2017) (click here for a recap on our prior weekly technical outlook).
We have also stressed that the 22950/23100 is the major key resistance which is defined by the descending trendline in place since 09 September 2016 high and a Fibonacci cluster zone. Negative elements have resurfaced where we expect the Index to stage the start of a potential correction.
- The daily RSI oscillator has just inched down from its overbought zone.
- The shorter-term 4 hour Stochastic oscillator has flashed a bearish divergence signal at its extreme overbought level. These observations coupled with the latest reading from daily RSI oscillator suggest that upside momentum has deteriorated and price action of the Index is likely to see a major bearish reversal.
As long as the 22950/23100 medium-term resistance is not surpassed, the Index is now likely to stage a potential multi-week decline to target the next supports at 22460 follow by 22060/21920 next (former swing low area of 09 November 2016 & the 61.8% Fibonacci retracement of the recent up move from 23 December 2016 low) in the first step.
However, a clearance above 23100 may invalidate the preferred bearish scenario to see a further squeeze up towards the next resistance at 24100.
ASX 200 – Bearish elements formed below 5830/850 key resistance

Key Levels (1 to 3 weeks)
Intermediate resistance: 5780
Pivot (key resistance): 5830/850
Supports: 5700 & 5580
Next resistance: 6000 (key long-term resistance)
Medium-term (1 to 3 weeks) Outlook
The Australia 200 Index (proxy for the ASX 200 futures) has traded sideways below the 5850 upper neutrality level as per highlighted in our prior weekly technical outlook report. Right now, bearish elements have emerged as follow:
- Price action has formed bearish daily candlestick patterns right below the 5850 resistance level, a “Shooting Star” on 09 January 2017 followed by a “Bearish Marubozu “on 12 January 2017.
- The daily RSI oscillator has just exited from its overbought zone after it recorded an extreme overbought level not seen since February 2015.
- The short-term Stochastic oscillator has flashed a prior bearish divergence signal.
All the observations suggest that the up move from 04 November 2016 low is losing upside momentum where at least a medium-term (1 to 3 weeks) bearish reversal is likely to occur at this juncture.
Therefore, we turn bearish at this juncture and as long as the 5830/850 medium-term pivotal resistance is not surpassed, the Index is likely to see a further potential decline to test the first support at 5700 (close to the lower boundary of the ascending channel in place since 04 November 2016 low) before targeting 5580 next.
On the other hand, a clearance above 5850 may invalidate the bearish scenario for a push up towards the key long-term resistance of 6000.
DAX – Mixed elements below 11800 major key resistance
(Click to enlarge charts)
Key Levels (1 to 3 weeks)
Resistances: 11800 & 12020
Supports: 11360 & 10810
Medium-term (1 to 3 weeks) Outlook
Last week, the Germany 30 Index (proxy for the DAX futures) has inched higher towards the first medium-term target/resistance of 11800 (printed a high of 11695 on 11 January 2016) before traded sideways in the later part of the week.
For a quick recap, the 11800 is the lower limit of a major key long-term resistance zone of 11800/12000 where a potential correction may materialise. The 11800/12000 is being defined by a confluence of elements; the exit potential of the recent bullish breakout from a three month range configuration in place since 15 August 2016 high triggered on 06 December 2016, the major swing high area of 26 May/20 July 2015 and a Fibonacci cluster zone.
Technical elements are mixed now such as the daily RSI oscillator has just exited from its overbought zone after it hit an extreme overbought level in the week of 03 January 2017.
Therefore, we have decided to turn neutral in the medium-term for now between 11800 and 11360.
Charts are from City Index Advantage TraderPro & eSignal
Disclaimer
The material provided herein is general in nature and does not take into account your objectives, financial situation or needs. While every care has been taken in preparing this material, we do not provide any representation or warranty (express or implied) with respect to its completeness or accuracy. This is not an invitation or an offer to invest nor is it a recommendation to buy or sell investments. City Index recommends you to seek independent financial and legal advice before making any financial investment decision. Trading CFDs and FX on margin carries a higher level of risk, and may not be suitable for all investors. The possibility exists that you could lose more than your initial investment further CFD investors do not own or have any rights to the underlying assets. It is important you consider our Financial Services Guide and Product Disclosure Statement (PDS) available at www.cityindex.com.au, before deciding to acquire or hold our products. As a part of our market risk management, we may take the opposite side of your trade. GAIN Capital Australia Pty Ltd (ACN 141 774 727, AFSL 345646) is the CFD issuer and our products are traded off exchange.
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.