



Stocks may have overacted to the downside on G20 news flow
Hang Seng Index has declined to key medium-term support with positive technical elements where a potential recovery may materialise.
Share this:

Yesterday, 25 Jun “sell-off” seen in U.S. stocks have saw losses within the range of -1.00% to -1.5% among the key U.S. benchmark stock indices, the 3rd day of consecutive decline with the higher beta tech heavy Nasdaq 100 being hit the hardest.
Primary triggers have been negative news flow from “Fed Speak” and G20 as reported yesterday;
- Fed official Bullard was quoted in a media report that he favoured a 25 bps cut on the Fed funds rate to act as “an insurance” to buffer slower economic growth rather than a 50 bps reduction. This news flow triggered a negative feedback loop into the markets as the Fed funds futures have priced in a 42% probability of a 50 bps cut a day ago on 24 Jun based on CME Fed Watch tool.
- U.S. administration has stated that plans have been made to suspend the next round of tariffs on an additional US$300 billion of China imports ahead of G20 summit. Also, U.S. will not accept any further conditions on tariffs as part of reopening trade negations with China and no detailed trade deal is expected from the Trump-Xi G20 meeting as quoted by media from a senior U.S. administration official.
Media reports have attributed the sell-off seen in U.S stocks from the probable “less rosy” outcome from Trump-Xi G20 meeting where a trade deal will not be struck between U.S. and China. Interestingly, a week ago where media had interviewed the investing and political analysts’ community and most of them have a bias that a trade deal will not materialise after the G20 summit.
Thus, yesterday’s G20 related news have already been priced into the markets. In fact, the U.S. administration’s latest plan to delay additional tariffs on China imports has shown a “toned down hawkish stance” and the willingness to restart trade negotiation talks with China is rather a positive catalyst. Click here for a recap on our G20 preview.
Therefore, the 3-days of consecutive decline seen in stocks may have been overdone and since now the media has spin “a less rosy” outcome from Trump-Xi meeting and if any encouraging trade related remarks from U.S. administration after the meeting can easily trigger a positive feedback loop back into stocks and risk assets.
Now, lets us review the technical structure on the Hang Seng Index, a key China related play that can be impacted from G20 news flows.
Short-term technical outlook on Hang Seng Index/Hong Kong 50 (Wed 26 Jun)
click to enlarge charts
Key technical elements
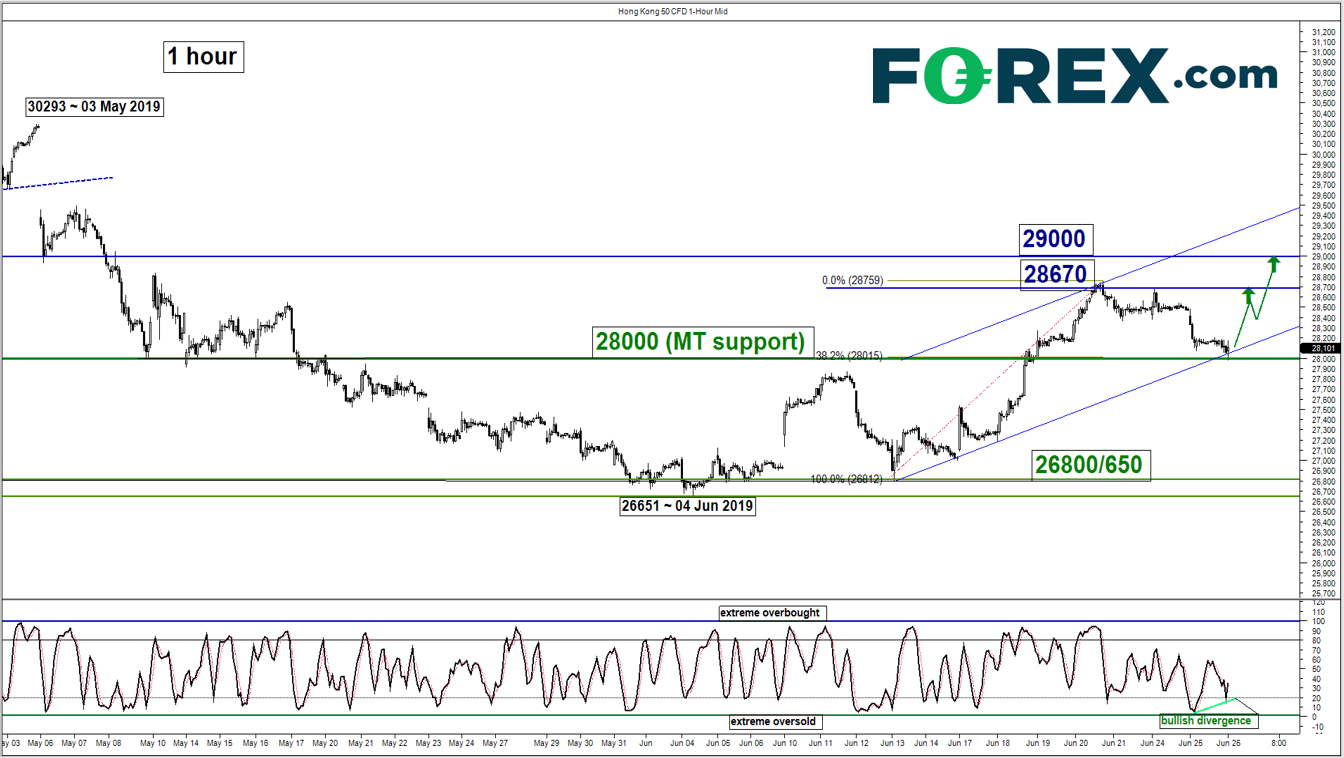
- Since its high of 28756 printed on 20 Jun 2019, the Hong Kong 50 Index (proxy for Hang Seng Index futures) has declined by -2.7% to print a current intraday low of 27982 as at today, 26 Jun Asian session.
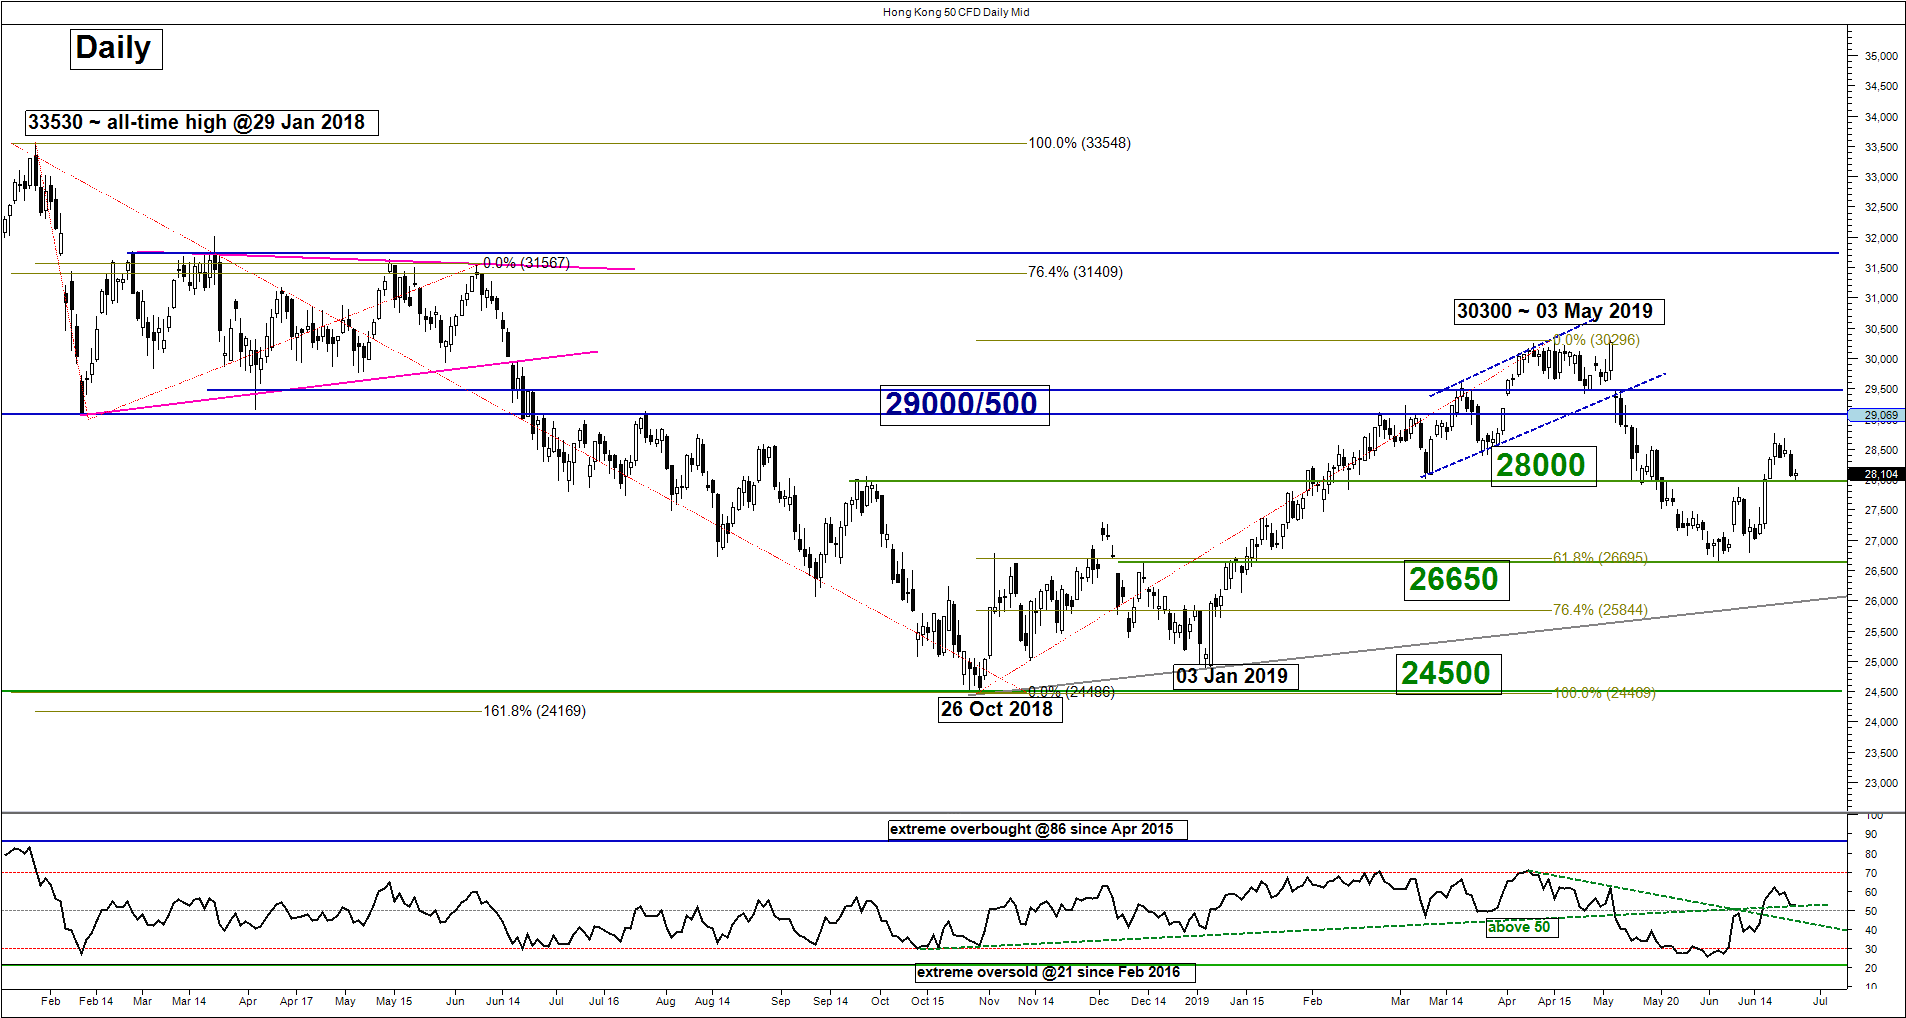
- Interestingly, the decline has led to a test on the predefined key medium-term pivotal at 28000 (click here for a recap on our weekly technical outlook report) with positive elements.
- The daily RSI oscillator is now resting on a significant corresponding support at the 50 level with a bullish divergence signal seen in the shorter-term hourly Stochastic oscillator at its extreme oversold level. These observations suggest that the recent downside momentum has started to ease.
- The 28000 key medium-term pivotal support also now confluences with the lower boundary of the minor ascending channel in place since 13 Jun 2019 low.
Key Levels (1 to 3 days)
Pivot (key support): 28000 (medium-term pivot)
Resistances: 28670 & 29000
Next support: 26800/650
Conclusion
If the 28000 key medium-term pivotal support holds, the Index is likely to see a potential recovery to retest the recent 20 Jun minor swing high area of 28670 before targeting the next resistance at 29000.
On the other hand, a daily close below 28000 invalidates the recovery scenario for a further decline towards the next support at 26800/650 (the aftermath of the recent local HK street protests over the China extradition bill).
Yesterday, 25 Jun “sell-off” seen in U.S. stocks have saw losses within the range of -1.00% to -1.5% among the key U.S. benchmark stock indices, the 3rd day of consecutive decline with the higher beta tech heavy Nasdaq 100 being hit the hardest.
Primary triggers have been negative news flow from “Fed Speak” and G20 as reported yesterday;
- Fed official Bullard was quoted in a media report that he favoured a 25 bps cut on the Fed funds rate to act as “an insurance” to buffer slower economic growth rather than a 50 bps reduction. This news flow triggered a negative feedback loop into the markets as the Fed funds futures have priced in a 42% probability of a 50 bps cut a day ago on 24 Jun based on CME Fed Watch tool.
- U.S. administration has stated that plans have been made to suspend the next round of tariffs on an additional US$300 billion of China imports ahead of G20 summit. Also, U.S. will not accept any further conditions on tariffs as part of reopening trade negations with China and no detailed trade deal is expected from the Trump-Xi G20 meeting as quoted by media from a senior U.S. administration official.
Media reports have attributed the sell-off seen in U.S stocks from the probable “less rosy” outcome from Trump-Xi G20 meeting where a trade deal will not be struck between U.S. and China. Interestingly, a week ago where media had interviewed the investing and political analysts’ community and most of them have a bias that a trade deal will not materialise after the G20 summit.
Thus, yesterday’s G20 related news have already been priced into the markets. In fact, the U.S. administration’s latest plan to delay additional tariffs on China imports has shown a “toned down hawkish stance” and the willingness to restart trade negotiation talks with China is rather a positive catalyst. Click here for a recap on our G20 preview.
Therefore, the 3-days of consecutive decline seen in stocks may have been overdone and since now the media has spin “a less rosy” outcome from Trump-Xi meeting and if any encouraging trade related remarks from U.S. administration after the meeting can easily trigger a positive feedback loop back into stocks and risk assets.
Now, lets us review the technical structure on the Hang Seng Index, a key China related play that can be impacted from G20 news flows.
Short-term technical outlook on Hang Seng Index/Hong Kong 50 (Wed 26 Jun)
click to enlarge charts
Key technical elements
- Since its high of 28756 printed on 20 Jun 2019, the Hong Kong 50 Index (proxy for Hang Seng Index futures) has declined by -2.7% to print a current intraday low of 27982 as at today, 26 Jun Asian session.
- Interestingly, the decline has led to a test on the predefined key medium-term pivotal at 28000 (click here for a recap on our weekly technical outlook report) with positive elements.
- The daily RSI oscillator is now resting on a significant corresponding support at the 50 level with a bullish divergence signal seen in the shorter-term hourly Stochastic oscillator at its extreme oversold level. These observations suggest that the recent downside momentum has started to ease.
- The 28000 key medium-term pivotal support also now confluences with the lower boundary of the minor ascending channel in place since 13 Jun 2019 low.
Key Levels (1 to 3 days)
Pivot (key support): 28000 (medium-term pivot)
Resistances: 28670 & 29000
Next support: 26800/650
Conclusion
If the 28000 key medium-term pivotal support holds, the Index is likely to see a potential recovery to retest the recent 20 Jun minor swing high area of 28670 before targeting the next resistance at 29000.
On the other hand, a daily close below 28000 invalidates the recovery scenario for a further decline towards the next support at 26800/650 (the aftermath of the recent local HK street protests over the China extradition bill).
Charts are from City Index Advantage TraderPro
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nikkei swings harder than Nasdaq as AI fears deepen
Nikkei 225 volatility is running well ahead of Nasdaq 100, with the index construction and Japan's heavy exposure to AI manufacturing potentially explaining the difference.

S&P 500, Nasdaq 100 Claw Back But NVDA Cloud Looms Overhead
Last week was green for both the Nasdaq and S&P 500 but given the sell-off that led into that bounce there’s still a very real question as to whether bears still have a statement to make. And the NVDA situation presents a very real threat.


Nasdaq 100 forecast: Nvidia troubles put AI recovery into question
The recovery for major indices this week has helped repair much of the technical damage inflicted by last week’s sell-off, but the latest developments with Nvidia suggest investors are not quite ready to put the underlying risks behind them. The Nasdaq 100 led other US index futures lower overnight, with falls of around 0.8%.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.