



ASX200 Afternoon Report July 20th 2022
The ASX200 trades 105 points higher at 6755 at 3.15 pm Sydney time with all sectors in the green.
Share this:
This content will only appear on City Index websites!
The ASX200 trades 105 points higher at 6755 at 3.15 pm Sydney time with all sectors in the green.
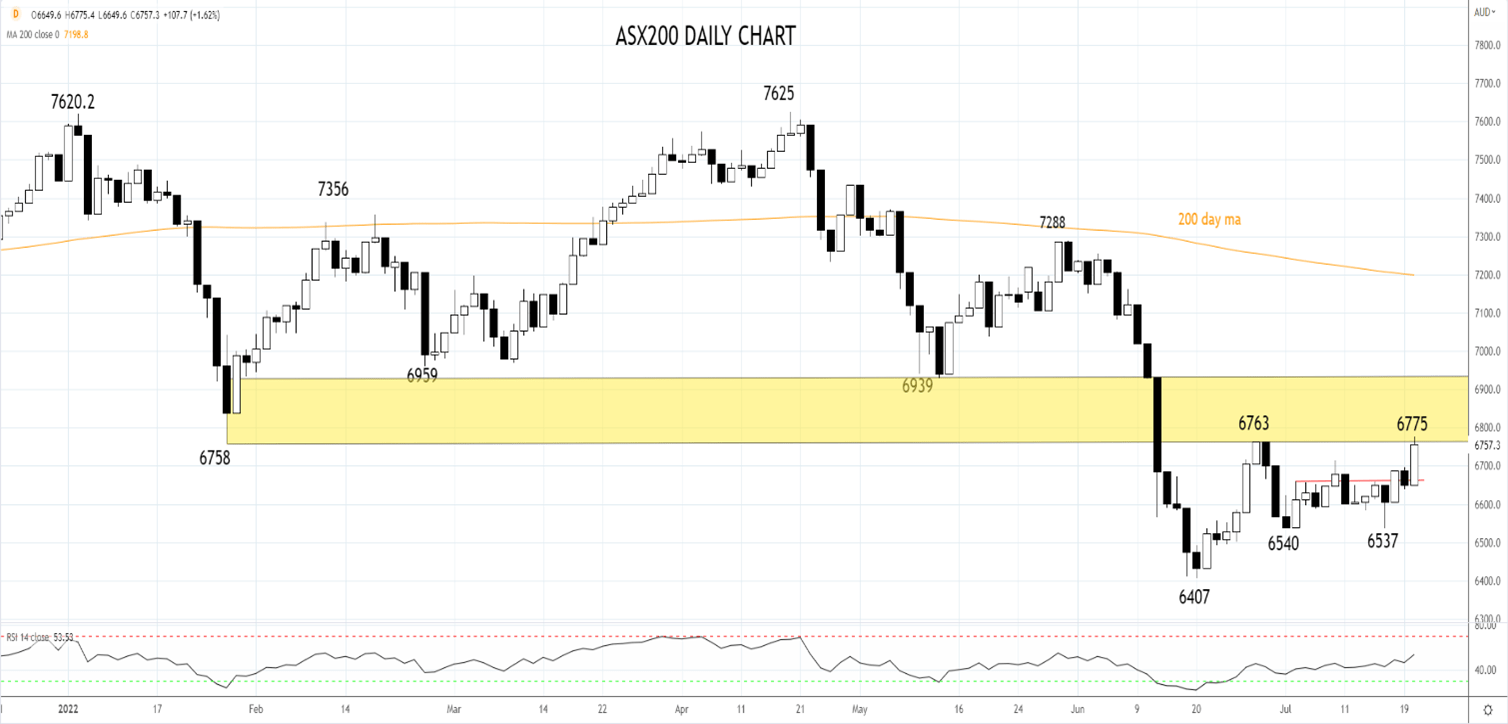
After a promising start to the new week ended in disappointment yesterday, the ASX200 has today traded to its highest level in five weeks at 6775.4, supported by a robust overnight session on Wallstreet.
The rally on Wallstreet follows apparent confirmation that gas supply to Europe via the Nord Stream 1 would soon resume. And better-than-expected U.S Q2 earnings reports that have (for now) eased concerns over an imminent slowdown.
The high beta tech sector has led the rampage higher, with Megaport the best on ground, adding 23% to $7.95 after the company reported EBITDA profit in Q4 for the first time. Elsewhere, ZIP added 11% to $0.66c, Tyro Payments added 7.5% to $0.71c. Appen added 6.6% to $6.28 and Wisetech Global added 5.5% to $44.43.
Looking to snap a six-week losing streak, the Materials Sector added 2.36%. Mineral Resources added 5.25% to $47.54, FMG added 4.76% to 4.64, South32 added 4.12% to $3.54 while index heavyweight BHP added 1.94% to $37.72
Gains also for Consumer Discretionary stocks following a bumper trading update from J.B. Hi-Fi yesterday. JB Hi-Fi added 4.5% to $43.64, Harvey Norman added 4.2% to $4.20. Flight Centre added 2.6% to $17.66, Wesfarmers added 1.7% to $46.92 and Webjet added 2% to $5.45.
Bank stocks have benefitted from a continued rebound in the U.S. banking sector and after Westpac bumped higher both its fixed and variable rates. Macquarie added 4.46% to $174.30, Westpac added 1.4% to $20.59, CBA added 1.2% to $96.07 and NAB added 0.7% to $29.26. The ANZ shares remain in a trading halt as it finalised its book build to buy Suncorp.
In the Lithium space, it was Liontown Resource's turn to notch double-digit gains as it climbed 10% to $1.12. Galan Resources added 8% to $1.07, Iluka Resources added 6.7% to $9.21, Core Lithium added 5.4% to $0.98, Pilbara added 4% to $2.46
Turning to the charts, the ASX200 has edged into the bottom of a resistance band between 6750/6950 that it needs to recover above to negate the technical damage caused by the breakdown in June. Until this occurs, the rally from the 6407 low is viewed as a bear market rally.
Source Tradingview. The figures stated are as of July 20th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The ASX200 trades 105 points higher at 6755 at 3.15 pm Sydney time with all sectors in the green.
After a promising start to the new week ended in disappointment yesterday, the ASX200 has today traded to its highest level in five weeks at 6775.4, supported by a robust overnight session on Wallstreet.
The rally on Wallstreet follows apparent confirmation that gas supply to Europe via the Nord Stream 1 would soon resume. And better-than-expected U.S Q2 earnings reports that have (for now) eased concerns over an imminent slowdown.
The high beta tech sector has led the rampage higher, with Megaport the best on ground, adding 23% to $7.95 after the company reported EBITDA profit in Q4 for the first time. Elsewhere, ZIP added 11% to $0.66c, Tyro Payments added 7.5% to $0.71c. Appen added 6.6% to $6.28 and Wisetech Global added 5.5% to $44.43.
Looking to snap a six-week losing streak, the Materials Sector added 2.36%. Mineral Resources added 5.25% to $47.54, FMG added 4.76% to 4.64, South32 added 4.12% to $3.54 while index heavyweight BHP added 1.94% to $37.72
Gains also for Consumer Discretionary stocks following a bumper trading update from J.B. Hi-Fi yesterday. JB Hi-Fi added 4.5% to $43.64, Harvey Norman added 4.2% to $4.20. Flight Centre added 2.6% to $17.66, Wesfarmers added 1.7% to $46.92 and Webjet added 2% to $5.45.
Bank stocks have benefitted from a continued rebound in the U.S. banking sector and after Westpac bumped higher both its fixed and variable rates. Macquarie added 4.46% to $174.30, Westpac added 1.4% to $20.59, CBA added 1.2% to $96.07 and NAB added 0.7% to $29.26. The ANZ shares remain in a trading halt as it finalised its book build to buy Suncorp.
In the Lithium space, it was Liontown Resource's turn to notch double-digit gains as it climbed 10% to $1.12. Galan Resources added 8% to $1.07, Iluka Resources added 6.7% to $9.21, Core Lithium added 5.4% to $0.98, Pilbara added 4% to $2.46
Turning to the charts, the ASX200 has edged into the bottom of a resistance band between 6750/6950 that it needs to recover above to negate the technical damage caused by the breakdown in June. Until this occurs, the rally from the 6407 low is viewed as a bear market rally.
Source Tradingview. The figures stated are as of July 20th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nikkei swings harder than Nasdaq as AI fears deepen
Nikkei 225 volatility is running well ahead of Nasdaq 100, with the index construction and Japan's heavy exposure to AI manufacturing potentially explaining the difference.

S&P 500, Nasdaq 100 Claw Back But NVDA Cloud Looms Overhead
Last week was green for both the Nasdaq and S&P 500 but given the sell-off that led into that bounce there’s still a very real question as to whether bears still have a statement to make. And the NVDA situation presents a very real threat.


Nvidia Earnings Preview: NVDA’s First Test of the Post Jenson Huang Era
Nvidia is expected to report $2.47 in EPS on $108.8B in revenue this quarter, but investors will be more interested in the company's guidance after the unexpected departure of founder and CEO Jenson Huang.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.