



ASX200 Afternoon Report June 21st 2022
The ASX200 is trading 94 points higher at 6527 at 3pm Sydney time and is set to snap a seven-session losing streak that has wiped over $200 billion off the local index.
Share this:
The ASX200 is trading 94 points higher at 6527 at 3pm Sydney time and is set to snap a seven-session losing streak that has wiped over $200 billion off the local index.
The rally on the ASX200 follows a long weekend in the U.S, which has acted as a circuit breaker of sorts, allowing investors to regroup and take stock after U.S equity markets plunged 10% over the past two weeks.
Also supporting, a speech today by RBA Governor Phillip Lowe, who pushed back on the interest rate markets aggressive pricing of RBA rate hikes and noted it would be unlikely that the cash rate gets anywhere near the 4% the market is currently pricing.
Finally, after a horrific run, the market will start to look at potential rebalancing flows for end of month, end of the quarter and end of financial year, which I would expect to be supportive of stock markets at the expense of fixed income.
Reversing a run of heavy falls, the Energy and the Materials Sectors have been the best on the ground today, supported by a rally in iron ore, coal and crude oil futures prices during the Asian time zone.
Beach Energy (BPT) added 3.87% to $1.61. Woodside (WDS) lifted by 3.97% to $31.57, Origin Energy (ORG) added 2.6% to $5.59, and Santos (STO) added 2.53% to $7.51.
Coal miner, Yancoal (YAL) added 6.36% to $5.35, Whitehaven Coal (WHC) added 4.19% to $4.73, New Hope Coal added 3.75% to $3.33 while Coronado Coal (CRN) added 0.91% to $1.66
Iron Ore heavy weight Fortescue Metals (FMG) added 2.53%% to $17.44, Rio Tinto (RIO) added 2.52% to $104.17, BHP Group (BHP) added 2.55% to $41.72. Elsewhere South32 (S32) added 2.46% to $4.16 while Lynas (LYC) added 4.17% to $8.74.
A rebound also for the financial stock’s supported by lower yields as the Aussie front end cratered following the more dovish tones from the RBA Governor this morning.
National Australia Bank (NAB) added 3.18% to $26.88. ANZ added 2.52% to $21.93, Westpac (WBC) added 2.34% to $19.64, Commonwealth Bank (CBA) added 1.84% to $89.16, and Macquarie (MQG) added 1.7% to $164.33.
A mixed session for the IT sector. Novonix (NVX) added 6.6% to $2.50, Life 360 (360) added 5.8% to $2.75, Afterpay owner Block (SQ2) added 2% to $86.01. Elsewhere, Megaport (MP1) fell 4% to $5.08, more pain for BNPL stock ZIP (ZIP) as it fell 0.94% to $0.53 and Wisetech Global (WTC) fell 0.9% to $35.77.
The roller-coaster ride in the Lithium space continues. Lake Resources (LKE) plunged 21% to $1.07; Core Lithium (CXO) fell 5.6% to $1.02. Elsewhere, Pilbara Minerals (PLS) added 3.43% to $2.11, Allkem (AKE) added 3% to $10.09, and Iluka Resources (ILU) added 2.75% to $8.97.
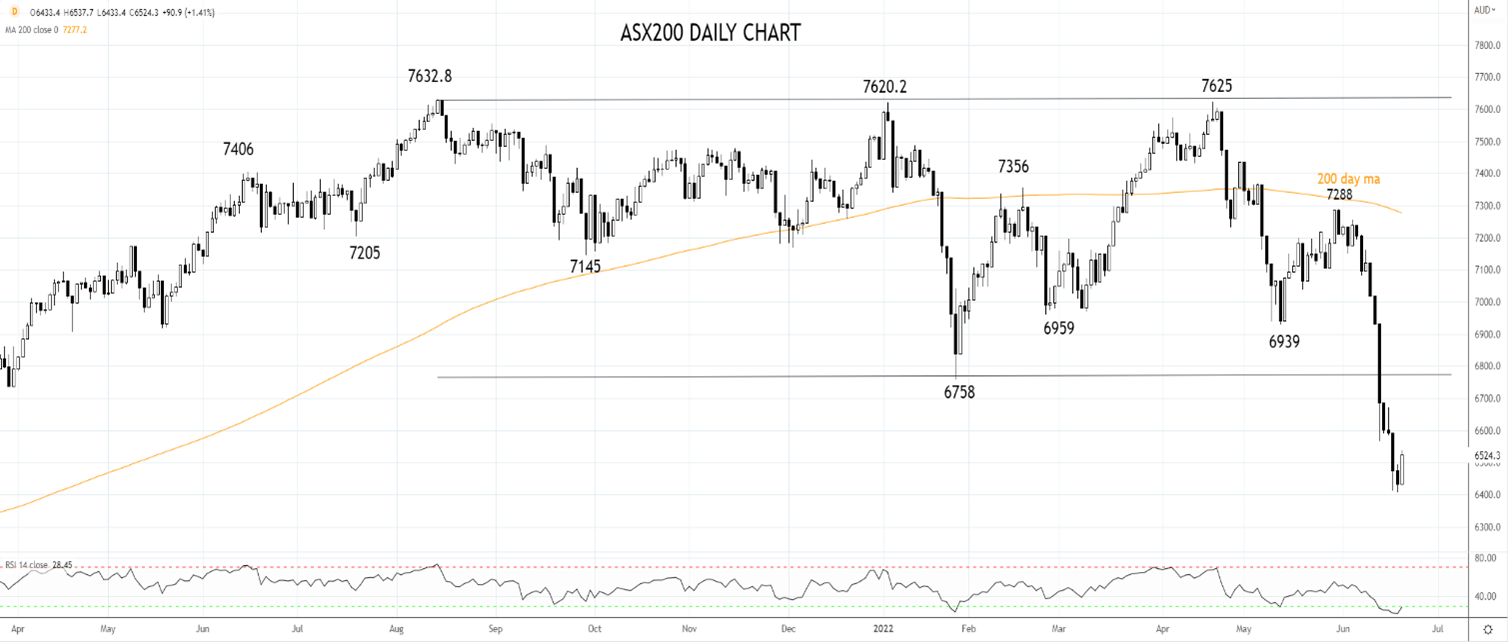
Until last week, the ASX200 appeared to be tracing out an orderly correction - trading just 10% below its all-time highs and within a well-defined nine-month range between 7630 and 6750ish. However, the decisive break from the bottom of the range 6850/6750 early last week created significant technical damage to the index.
The ASX200 must rebound above 6750/6850ish to restore some much-needed confidence in the market. Otherwise, the risks are for the ASX200 to continue lower towards 6000 with scope to 5750 once the expected end of month rally is complete.
Source Tradingview. The figures stated are as of June 21st, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The ASX200 is trading 94 points higher at 6527 at 3pm Sydney time and is set to snap a seven-session losing streak that has wiped over $200 billion off the local index.
The rally on the ASX200 follows a long weekend in the U.S, which has acted as a circuit breaker of sorts, allowing investors to regroup and take stock after U.S equity markets plunged 10% over the past two weeks.
Also supporting, a speech today by RBA Governor Phillip Lowe, who pushed back on the interest rate markets aggressive pricing of RBA rate hikes and noted it would be unlikely that the cash rate gets anywhere near the 4% the market is currently pricing.
Finally, after a horrific run, the market will start to look at potential rebalancing flows for end of month, end of the quarter and end of financial year, which I would expect to be supportive of stock markets at the expense of fixed income.
Reversing a run of heavy falls, the Energy and the Materials Sectors have been the best on the ground today, supported by a rally in iron ore, coal and crude oil futures prices during the Asian time zone.
Beach Energy (BPT) added 3.87% to $1.61. Woodside (WDS) lifted by 3.97% to $31.57, Origin Energy (ORG) added 2.6% to $5.59, and Santos (STO) added 2.53% to $7.51.
Coal miner, Yancoal (YAL) added 6.36% to $5.35, Whitehaven Coal (WHC) added 4.19% to $4.73, New Hope Coal added 3.75% to $3.33 while Coronado Coal (CRN) added 0.91% to $1.66
Iron Ore heavy weight Fortescue Metals (FMG) added 2.53%% to $17.44, Rio Tinto (RIO) added 2.52% to $104.17, BHP Group (BHP) added 2.55% to $41.72. Elsewhere South32 (S32) added 2.46% to $4.16 while Lynas (LYC) added 4.17% to $8.74.
A rebound also for the financial stock’s supported by lower yields as the Aussie front end cratered following the more dovish tones from the RBA Governor this morning.
National Australia Bank (NAB) added 3.18% to $26.88. ANZ added 2.52% to $21.93, Westpac (WBC) added 2.34% to $19.64, Commonwealth Bank (CBA) added 1.84% to $89.16, and Macquarie (MQG) added 1.7% to $164.33.
A mixed session for the IT sector. Novonix (NVX) added 6.6% to $2.50, Life 360 (360) added 5.8% to $2.75, Afterpay owner Block (SQ2) added 2% to $86.01. Elsewhere, Megaport (MP1) fell 4% to $5.08, more pain for BNPL stock ZIP (ZIP) as it fell 0.94% to $0.53 and Wisetech Global (WTC) fell 0.9% to $35.77.
The roller-coaster ride in the Lithium space continues. Lake Resources (LKE) plunged 21% to $1.07; Core Lithium (CXO) fell 5.6% to $1.02. Elsewhere, Pilbara Minerals (PLS) added 3.43% to $2.11, Allkem (AKE) added 3% to $10.09, and Iluka Resources (ILU) added 2.75% to $8.97.
Until last week, the ASX200 appeared to be tracing out an orderly correction - trading just 10% below its all-time highs and within a well-defined nine-month range between 7630 and 6750ish. However, the decisive break from the bottom of the range 6850/6750 early last week created significant technical damage to the index.
The ASX200 must rebound above 6750/6850ish to restore some much-needed confidence in the market. Otherwise, the risks are for the ASX200 to continue lower towards 6000 with scope to 5750 once the expected end of month rally is complete.
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nvidia Earnings Preview: NVDA’s First Test of the Post Jenson Huang Era
Nvidia is expected to report $2.47 in EPS on $108.8B in revenue this quarter, but investors will be more interested in the company's guidance after the unexpected departure of founder and CEO Jenson Huang.

Brazil Elections: Is Investor Confidence Beginning to Fade?
One of the most relevant events for emerging markets in recent sessions has been the outcome of Brazil’s presidential election. Following Lula da Silva’s victory in the second round, investor sentiment began to deteriorate noticeably. This can be observed in both the iShares MSCI Brazil ETF and the VanEck Brazil Small-Cap ETF, two important benchmarks for tracking the Brazilian equity market, both of which have posted declines of more than 15% at the start of the week.


Weekly Equities Outlook: Amazon, Alphabet and Lloyds
Big tech earnings ramp up, with Amazon, Alphabet and Microsoft updating the market as worries over heavy AI spending weigh on sentiment. UK banks are also in focus ahead of the Budget, with earnings from Lloyds, NatWest, Standard Chartered, and HSBC.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.