



ASX200 Afternoon Wrap 17th of March 2022
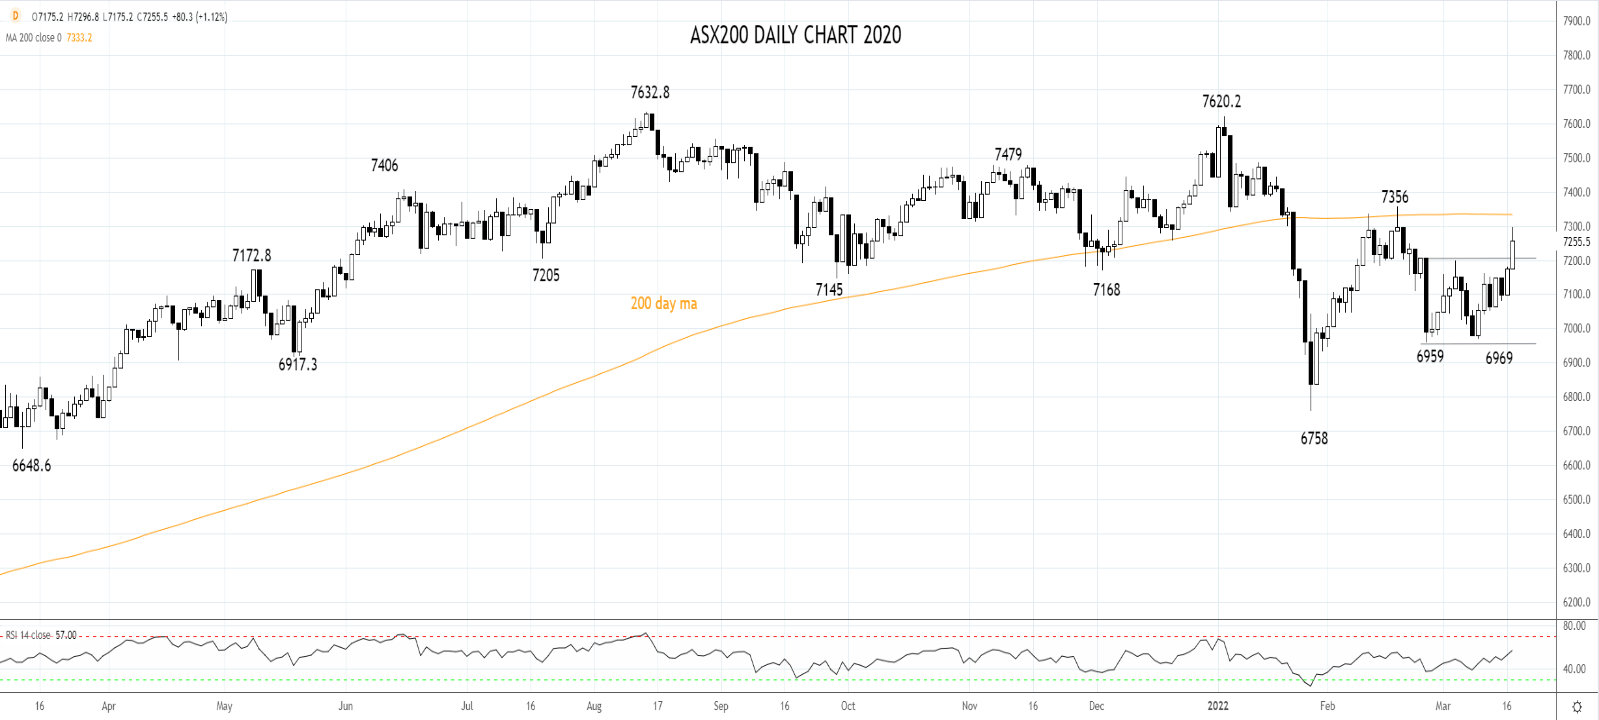
Following a strong lead from Wall Street and building on yesterday's 1.1% rally, the ASX200 closed 1.05% higher today at 7250.8, a 4-week closing high.
Share this:
The rally despite the ASX24 futures trading platform suffering a four-hour outage due to a "hardware-related" issue. A breakdown that prevented traders from Portfolio Managers at billion-dollar hedge funds to private traders accessing liquidity over today's Australian jobs data for February.
The ASX will undoubtedly receive a please explain from joint regulators ASIC and the RBA. The systems failure may force institutional traders to assess whether the ASX200's suite of futures products can remain part of their trading strategy, particularly if they cannot manage their risk over tier-one domestic data releases.
Turning to markets, the Federal Reserve followed the lead of the ECB last week this morning to deliver a hawkish surprise.
The Feds median dot in 2023 at 2.75% indicates an intention to take the terminal rate firmly above the neutral rate. An imminent start to quantitative tightening was also flagged. Despite this, equity markets ripped higher, contrary to what might have been expected, led by the tech-heavy Nasdaq.
A move that has flowed through into the local IT Sector, which followed up its 3.24% gain yesterday, adding another 3.83% today. Once again, the star of the show, Block (SQ2) added 10.71% to $158.32. Z1P Co (ZIP) added 9.44% to $1.57, Wisetech Global (WTC) added 3.44%, and Xero (XRO) chimed in with a 2.75% gain to $99.83.
Resource stocks have benefiting from China's State Council announcement yesterday, steps to restore confidence in the economy and capital markets. A new Covid treatment strategy was also revealed to balance Covid containment with economic activity. Fortescue Mining (FMG) is the best of the big three mining heavyweights, adding 3.76% to $18.05. BHP Group (BHP) has lifted by 0.95% to $45.61 and Rio Tinto (Rio) added 01.17% to $108.16. Also helped by a 4% rally in iron ore futures in Asia.
The ASX200 Financial Sector added another 1% to test levels not seen since the first week of 2022. ANZ again the best of the big four banks, adding 1.58% to $27.60. Commonwealth Bank (CBA) added 1.26% to $106.07, eyeing its all-time high at $110.19. National Australia Bank (NAB) added 1.41% to $31.19, while Macquarie Group (MQG) added 1.69% to $192.67.
Still relishing in the joy of the crude oil price trading 30% below last week's high and news that New Zealand will begin opening its borders next month, travel stocks have had another good day Qantas (QAN) shares lifted 1.78% to $5.14, Webjet (WEB) added 1.59% to $5.76, and Flight Centre (FLT) added 1.73% to $19.43.
Despite a rise in the gold price in Asia to $1936 (+0.50%), it’s been a disappointing day for Aussie goldies. Northern Star Resources (NST) fell by -0.56% to $10.48, while Evolution Mining (EVN) fell by 0.67% to $10.48. Newcrest Mining (NCM) traded flat on the day at $25.93.
On the data front Australians labour force data for February was very strong. Employment rose by 77k vs expectations of 40k. The unemployment rate dropped to 4%, its lowest level since 2008 despite the participation rate rising to 66.4%, it highest level on record.
Source Tradingview. The figures stated are as of March 17th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The rally despite the ASX24 futures trading platform suffering a four-hour outage due to a "hardware-related" issue. A breakdown that prevented traders from Portfolio Managers at billion-dollar hedge funds to private traders accessing liquidity over today's Australian jobs data for February.
The ASX will undoubtedly receive a please explain from joint regulators ASIC and the RBA. The systems failure may force institutional traders to assess whether the ASX200's suite of futures products can remain part of their trading strategy, particularly if they cannot manage their risk over tier-one domestic data releases.
Turning to markets, the Federal Reserve followed the lead of the ECB last week this morning to deliver a hawkish surprise.
The Feds median dot in 2023 at 2.75% indicates an intention to take the terminal rate firmly above the neutral rate. An imminent start to quantitative tightening was also flagged. Despite this, equity markets ripped higher, contrary to what might have been expected, led by the tech-heavy Nasdaq.
A move that has flowed through into the local IT Sector, which followed up its 3.24% gain yesterday, adding another 3.83% today. Once again, the star of the show, Block (SQ2) added 10.71% to $158.32. Z1P Co (ZIP) added 9.44% to $1.57, Wisetech Global (WTC) added 3.44%, and Xero (XRO) chimed in with a 2.75% gain to $99.83.
Resource stocks benefiting from China's State Council announcement yesterday, steps to restore confidence in the economy and capital markets. A new Covid treatment strategy was also revealed to balance Covid containment with economic activity. Fortescue Mining (FMG) is the best of the big three mining heavyweights, adding 3.76% to $18.05. BHP Group (BHP) has lifted by 0.95% to $45.61 and Rio Tinto (Rio) added 01.17% to $108.16. Also helped by a 4% rally in iron ore futures in Asia.
The ASX200 Financial Sector added another 1% to test levels not seen since the first week of 2022. ANZ again the best of the big four banks, adding 1.58% to $27.60. Commonwealth Bank (CBA) added 1.26% to $106.07, eyeing its all-time high at $110.19. National Australia Bank (NAB) added 1.41% to $31.19, while Macquarie Group (MQG) added 1.69% to $192.67.
Still relishing in the joy of the crude oil price trading 30% below last week's high and news that New Zealand will begin opening its borders next month, travel stocks have had another good day Qantas (QAN) shares lifted 1.78% to $5.14, Webjet (WEB) added 1.59% to $5.76, and Flight Centre (FLT) added 1.73% to $19.43.
Despite a rise in the gold price in Asia to $1936 (+0.50%), it’s been a disappointing day for Aussie goldies. Northern Star Resources (NST) fell by -0.56% to $10.48, while Evolution Mining (EVN) fell by 0.67% to $10.48. Newcrest Mining (NCM) trading flat on the day at $25.93.
On the data front Australians labour force data for February was very strong. Employment rose by 77k vs expectations of 40k. The unemployment rate dropped to 4%, its lowest level since 2008 despite the participation rate rising to 66.4%, it highest level on record.
Source Tradingview. The figures stated are as of March 17th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Brazil Elections: Is Investor Confidence Beginning to Fade?
One of the most relevant events for emerging markets in recent sessions has been the outcome of Brazil’s presidential election. Following Lula da Silva’s victory in the second round, investor sentiment began to deteriorate noticeably. This can be observed in both the iShares MSCI Brazil ETF and the VanEck Brazil Small-Cap ETF, two important benchmarks for tracking the Brazilian equity market, both of which have posted declines of more than 15% at the start of the week.


ASX 200 Outlook: A Rates Trade Disguised as a Stock Market?
Australian bond futures have exhibited a far stronger relationship with the ASX 200 than Wall Street over recent months. Now both markets are displaying remarkably similar price structures.
Dow Jones Analysis: Is the DJIA Making a Comeback?
Recent trading sessions have become increasingly relevant for the Dow Jones, as the index has started to regain bullish momentum heading into the end of the week. Over the last three sessions, the DJIA has advanced by more than 0.6%, allowing buying pressure to regain prominence and raising the possibility of a more consistent short-term recovery.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.