




Barratt turns cautious after another strong year
The stock has dropped like a brick on another Brexit crunch day
Share this:

The stock has dropped like a brick on the latest Brexit crunch day
Barratt Developments’ biggest one-day stock price drop of the year has raised the question of whether its mix of robust margins, advantageous strategic partnerships and market share can continue to shield it from the worst Brexit blow-back.
Shares in the group that builds most residential homes in large swathes of Britain have ground 73% higher since a post-referendum day bottom in July 2016. With the FTSE up a measly 12% since then, it is clear Barratt rode the housing market’s resilience to the kind of impacts widely feared in the wake of the Brexit vote.
Now, the group sees volume growth “towards the lower end” of its medium-term target range in the current financial year, causing the stock to lose as much as 5% at one point on Wednesday. Operating and revenue results for the 2018/19 year also suggest estimates have got somewhat ahead of current Barratt capacity, despite efficiency continuing to improve.
- Revenue: £4.76bn, up 2.3% year-on-year vs. average estimate of £4.82bn
- FY operating profit £901.1m, up 4.5% year-on-year vs. average estimate of £908.8m
- Operating margin 18.9% vs. 17.7% in 2018/19 full-year
(Consensus forecasts compiled by Bloomberg)
Barratt’s proven ability to withstand housing market volatility has rested on stable margins, and a dominant sector position garnered from decades of above-average volume gains that reaped strong market share growth. Britain’s historically robust residential property market has also played a part in providing the group with a leading cash-generation profile and rising net income each year since 2012.
Yet Barratt’s key multiples against itself and close rivals are mostly tracking near medium-to-long-term highs. Guidance towards the lower end of forecast ranges might well turn out to be strategic caution, particularly as “housing market fundamentals remain attractive, with a long-term undersupply”, according to the group. The more immediate investor worry then is sentiment. This year alone, the stock crushes the Bloomberg UK Homebuilder Index’s 11.6% gain, rising 29%. As fears of a potential Brexit chill gain immediacy, Barratt shares could be more vulnerable to reduction than more modestly performing rivals. And if Brexit’s bite matches its bark after all, an enriched valuation will have a similar, longer-lasting effect.
Chart thoughts
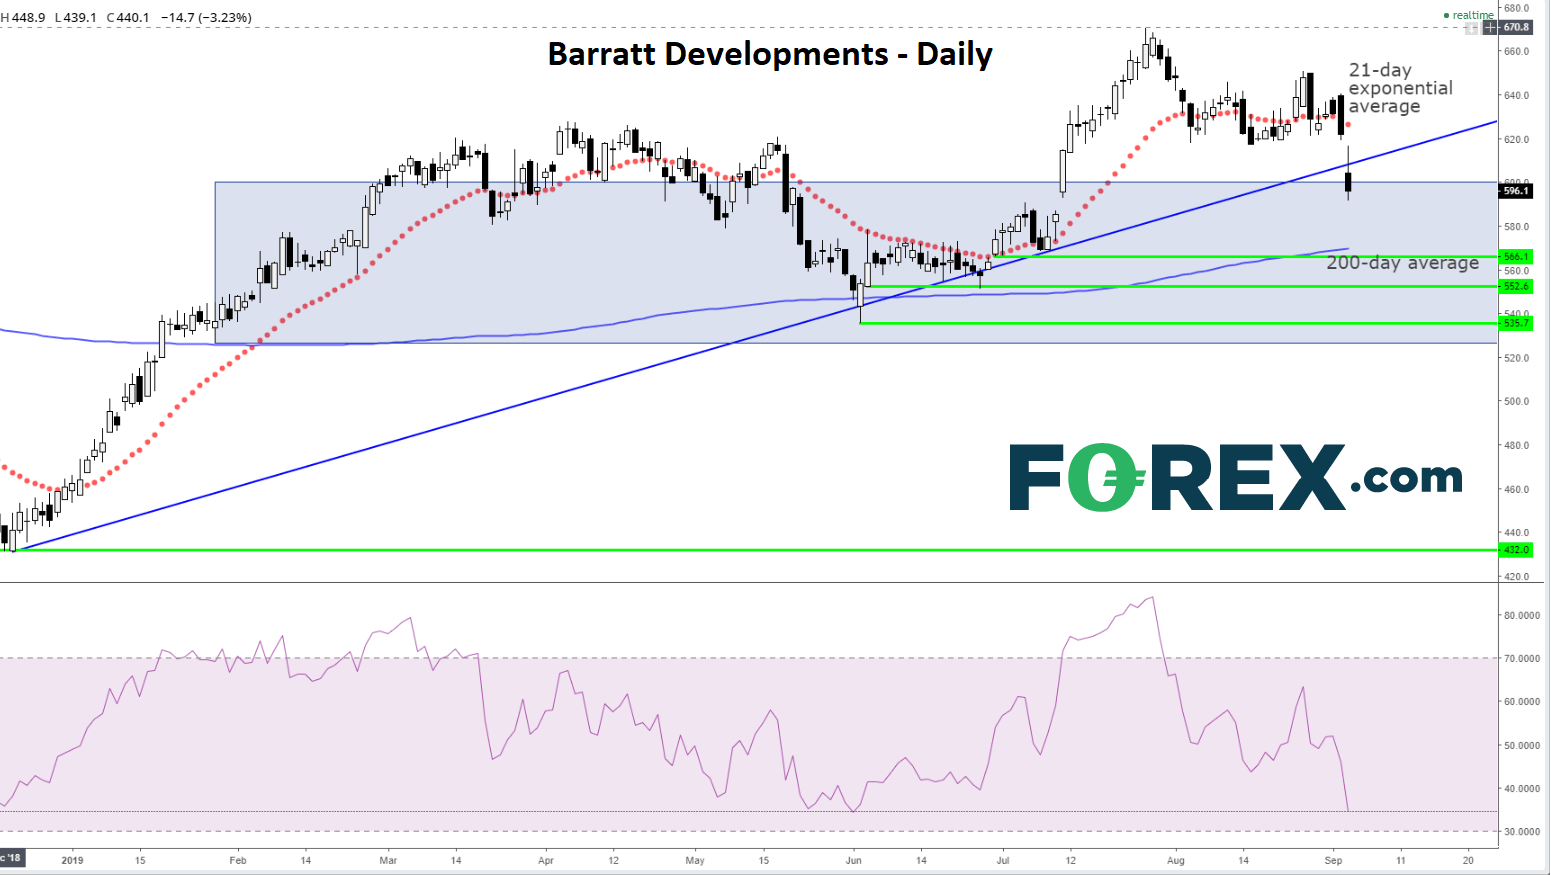
BDEV sellers’ ‘warning shot’ is the broken 2019 uptrend. The most immediate question buyers now need to assess concerns the sturdiness of the region that mostly encapsulated the stock between January and July. It’s an almost binary case of fight vs. flight. Above sure-footed kick-back lows of 535.7p, 552.6p and 566p (note the confluence of closest support with the 200-day average) defence would be holding. But the zone would appear hollower if those levels proved to be fragile, opening the way for a look back at the base of the year’s vault, 432p.
Barratt Developments CFD
Source: FOREX.com
The stock has dropped like a brick on the latest Brexit crunch day
Barratt Developments’ biggest one-day stock price drop of the year has raised the question of whether its mix of robust margins, advantageous strategic partnerships and market share can continue to shield it from the worst Brexit blow-back.
Shares in the group that builds most residential homes in large swathes of Britain have ground 73% higher since a post-referendum day bottom in July 2016. With the FTSE up a measly 12% since then, it is clear Barratt rode the housing market’s resilience to the kind of impacts widely feared in the wake of the Brexit vote.
Now, the group sees volume growth “towards the lower end” of its medium-term target range in the current financial year, causing the stock to lose as much as 5% at one point on Wednesday. Operating and revenue results for the 2018/19 year also suggest estimates have got somewhat ahead of current Barratt capacity, despite efficiency continuing to improve.
- Revenue: £4.76bn, up 2.3% year-on-year vs. average estimate of £4.82bn
- FY operating profit £901.1m, up 4.5% year-on-year vs. average estimate of £908.8m
- Operating margin 18.9% vs. 17.7% in 2018/19 full-year
(Consensus forecasts compiled by Bloomberg)
Barratt’s proven ability to withstand housing market volatility has rested on stable margins, and a dominant sector position garnered from decades of above-average volume gains that reaped strong market share growth. Britain’s historically robust residential property market has also played a part in providing the group with a leading cash-generation profile and rising net income each year since 2012.
Yet Barratt’s key multiples against itself and close rivals are mostly tracking near medium-to-long-term highs. Guidance towards the lower end of forecast ranges might well turn out to be strategic caution, particularly as “housing market fundamentals remain attractive, with a long-term undersupply”, according to the group. The more immediate investor worry then is sentiment. This year alone, the stock crushes the Bloomberg UK Homebuilder Index’s 11.6% gain, rising 29%. As fears of a potential Brexit chill gain immediacy, Barratt shares could be more vulnerable to reduction than more modestly performing rivals. And if Brexit’s bite matches its bark after all, an enriched valuation will have a similar, longer-lasting effect.
Chart thoughts
BDEV sellers’ ‘warning shot’ is the broken 2019 uptrend. The most immediate question buyers now need to assess concerns the sturdiness of the region that mostly encapsulated the stock between January and July. It’s an almost binary case of fight vs. flight. Above sure-footed kick-back lows of 535.7p, 552.6p and 566p (note the confluence of closest support with the 200-day average) defence would be holding. But the zone would appear hollower if those levels proved to be fragile, opening the way for a look back at the base of the year’s vault, 432p.
Barratt Developments CFD
Source: City Index
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nvidia Earnings Preview: NVDA’s First Test of the Post Jenson Huang Era
Nvidia is expected to report $2.47 in EPS on $108.8B in revenue this quarter, but investors will be more interested in the company's guidance after the unexpected departure of founder and CEO Jenson Huang.

Nvidia Holds Support Ahead of Earnings as Nasdaq 100 Rebounds
Nvidia shares approach major support as selling pressure eases, while the Nasdaq 100 rebounds. Could upcoming earnings fuel a broader recovery?
Nasdaq 100 Slides as Meta Posts Strong Results and Drops 6%
The Nasdaq 100 sell-off is being driven by doubts over AI spending, as investors punish strong earnings that fail to justify stretched valuations.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.