



Crude Oil Weekly Outlook: Back to the 62 Support
Crude Oil Weekly Outlook: Market risk sentiment continues to swing between geopolitical tensions, supply disruption risks, and oversupply concerns. However, key levels continue to define the main trends despite the volatility.
Share this:
Key Events
• International Energy Week leaned more bearish on supply expectations, reinforcing downside pressure toward the 62 zone.
• US crude inventories rose by 8.5 million barrels, marking the highest levels since February 2025 and confirming short-term surplus conditions.
• While macro sentiment fluctuates, structural technical levels continue to define directional bias.
International Energy Week emphasized growing output expectations rather than demand deterioration. The shift in tone reinforced supply-side pressure at a time when price remains technically vulnerable.
Bearish Structure Remains Dominant Since 2022
The latest inventory data confirmed a surplus of 8.5 million barrels, the first material build of this scale since February 2025. This aligns with the broader structure: crude oil remains within a primary bearish trend established from the 2022 highs.
While counter-trend rebounds have emerged throughout 2023–2025, the dominant descending channel structure has not been invalidated. Every rally continues to face structural resistance.
Crude Oil Inventories 
Source: Forex factory
Price action is now compressing near the 62 support zone, a pivotal level that separates tactical recovery from structural continuation lower.
A sustained hold above 62 maintains a neutral-to-bullish tactical bias. However, confirmation of upside momentum requires a decisive reclaim of 66 — the first structural pivot needed to challenge the broader downtrend.
Technical Analysis: Quantifying Uncertainties
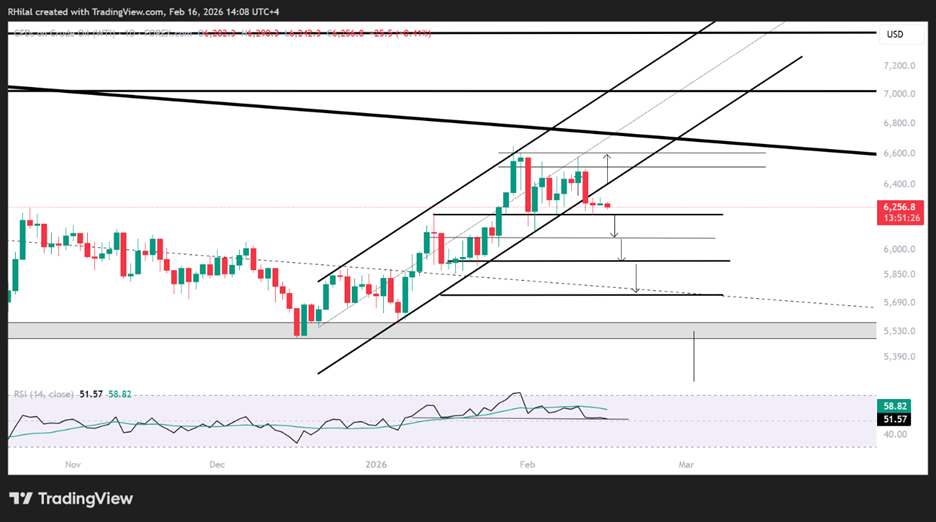
Crude Oil Outlook: Daily Time Frame – Log Scale
Source: Trading view
On the daily chart, price is testing the lower boundary of an ascending channel that has been developing since the 2025 lows. This counter-trend structure was supported by geopolitical hedging flows and weather-related demand strength earlier in the year. However, with tensions easing and inventories rising, WTI is now pressuring both the channel support and the 62 horizontal level.
Bearish Scenario
- A sustained break below 62 exposes 60 immediately.
- A confirmed close below 60 opens the path toward 57, the mid-zone of the ascending channel.
- Failure to stabilize there would shift focus toward 55, and in an accelerated downside extension, 49 — the lower boundary of the broader descending channel originating from the 2023 highs.
Bullish Scenario
- If 62 holds and price reclaims 66, upside momentum may build toward 70.50 — the upper boundary of the recent range.
- A sustained breakout above 70.50 would begin challenging the multi-year descending channel resistance, opening the door toward 74.50 and potentially 80, provided momentum indicators maintain constructive structure.
The 66–70.50 zone remains the technical gateway between counter-trend rebound and structural reversal attempt.
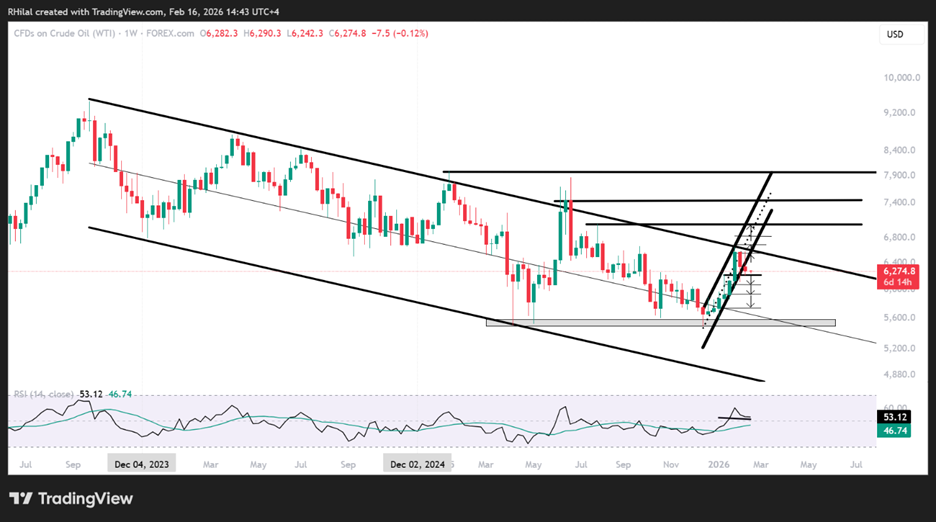
Crude Oil Outlook: Weekly Time Frame – Log Scale
Source: Trading view
From a weekly perspective, crude oil continues to trade within a descending channel in place since 2023. This remains the defining primary trend, regardless of short-term headline volatility.
The 60–62 zone represents the lower boundary of the recent consolidation range within this broader structure.
Below 60 and 59: The descending channel reasserts dominance, exposing 57, 55, and ultimately 49.
Until a decisive breakout occurs on the weekly timeframe, crude oil remains technically constrained within a multi-year bearish framework.
Written by Razan Hilal, CMT
Follow on X: @Rh_waves
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.


Crude Oil Weekly Outlook: Geopolitics vs Oversupply Risks
Crude Oil Weekly Outlook: The IEA has flagged the risk of an oil supply surplus since the Iran war began. Yet WTI and Brent have held onto bullish rebounds from key support near 84 and 89, respectively, as geopolitical risks persist.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.