- US Treasury yields surge in historic repricing
- Dollar's relationship with yields strengthens sharply
- EUR/USD tracks widening US–eurozone interest rate spreads
- Gold's shellacking far exceeds historical rate-shock norms
There's been a massive hawkish recalibration at the front end of the US interest rate curve this week, with a combination of persistently sticky consumer price inflation and hawkish commentary from Federal Reserve officials sending Treasury yields surging. With positioning potentially stretched following the substantial rally in bonds beforehand, the reversal has been extraordinary, producing one of the largest four-session increases in front-end yields seen in decades.
The move has propelled the US dollar to levels not seen since President Trump's Liberation Day tariff announcement in April last year, dragging both EUR/USD and gold to fresh 2026 lows in the process. But while the euro's decline has been broadly consistent with the repricing in relative interest rates, gold has been absolutely hammered, suffering one of its most severe sell-offs during a comparable Treasury market shock in modern history.
With New York Fed President John Williams set to speak shortly and US producer price inflation due on Friday, these loom as the two key known catalysts that could amplify or dampen the near-unprecedented move seen this week.
Treasury bloodbath ranks among the largest
With cash trading resuming on Thursday following the Veterans Day holiday, US Treasuries suffered yet another brutal sell-off, adding to what has already been a mammoth hawkish adjustment in interest rate expectations this week.
Source: LSEG
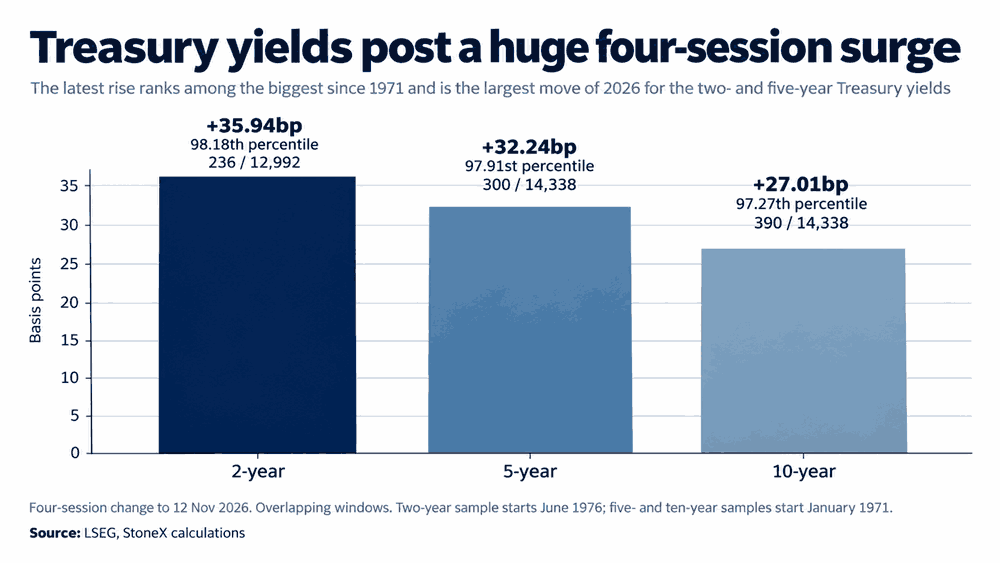
Over the four trading sessions to Thursday, two-year Treasury yields have now surged 35.94 basis points, with five-year yields up 32.24 basis points and ten-year yields climbing 27.01 basis points. For those who don't follow bonds closely, these moves are extraordinary, especially at the front end of the curve, where expectations for the Fed interest rate outlook are highly influential.
Looking at historical data, the increase in two-year yields ranks among the largest 1.8% of comparable four-session moves since 1976, with the five- and ten-year increases similarly rare in data stretching back to 1971. Zooming in on the period since 2000, when yields have generally been far lower than in preceding decades, the two-year move sits at the 99.7th percentile, a magnitude almost never seen over the past quarter-century.
US dollar takes its cues from Treasury yields
The hammering at the front end of the US Treasury curve has helped fuel an equally impressive rally in the US dollar, with the relationship between the two strengthening noticeably.
Source: LSEG
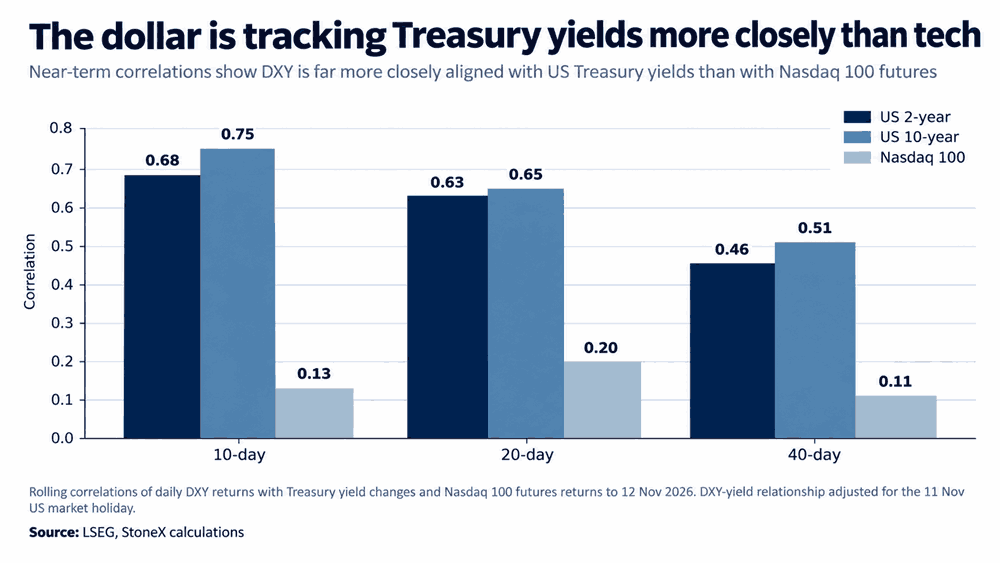
Over the past ten sessions, DXY's correlation with changes in two- and ten-year Treasury yields stands at +0.68 and +0.75, respectively, compared with just +0.13 against Nasdaq 100 futures. It suggests the curious relationship between the dollar and tech stocks, which pointed to markets using the latter as a proxy for the US nominal growth outlook, has lost much of its punch, with the increasingly hawkish Fed outlook now exerting greater influence.
Widening rate spreads hammer EUR/USD
The dramatic repricing at the front end of the US curve has also seen yield differentials move sharply against the euro, pushing EUR/USD to fresh 2026 lows. The six-month US–eurozone OIS spread, which tracks the difference in market expectations for average overnight interest rates over that period, has widened 14.23 basis points since last Friday, coinciding with a 0.80% decline in EUR/USD.
Based on the pair's sensitivity to changes in the spread over the preceding 20 sessions, the move is almost bang in line with the implied decline of 0.77%. In other words, the euro has fallen almost exactly as much as the shift in relative interest rates would suggest, reinforcing the importance of the Fed and ECB interest rate outlooks when assessing the pair's near-term directional risks.
EUR/USD breakdown puts 1.0900 in focus
Source: TradingView
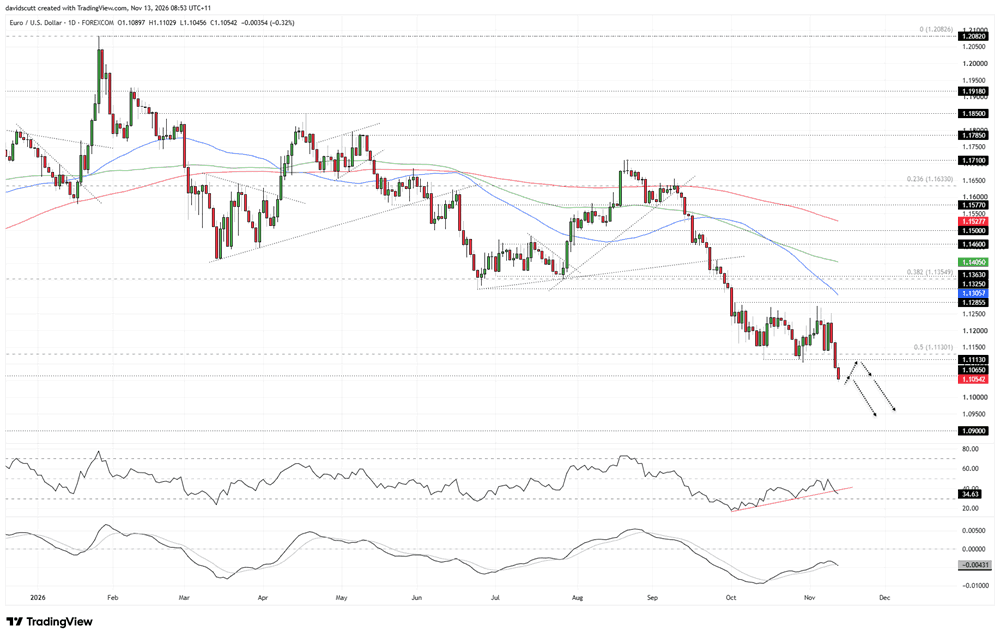
On the daily chart, the dramatic repricing in US interest rate expectations this week has seen EUR/USD once again fail to push meaningfully above resistance at 1.1250, triggering a sharp reversal that has taken out the 50% Fibonacci retracement of the January 2025 to January 2026 bull move, along with 1.1113, a swing low established on October 13 that subsequently acted as support in late October.
The price has since broken beneath 1.1065, a swing low established in May 2025, leaving both that level and 1.1113 as potential resistance overhead given their former roles as support. A push back towards either level that fails could present an opportunity to enter shorts in line with the prevailing trend, allowing for a tight stop to be placed above the respective level for protection.
Having broken beneath 1.1065, there's something of a vacuum in terms of known support levels, with little evident on the chart until 1.0900, suggesting the breakdown may have room to run.
Along with the pair trading beneath all its key medium- and long-term moving averages, all of which carry a negative slope, the bearish bias is backed up by the oscillators. RSI (14) has broken the uptrend in place since early October, setting a lower low and sitting just above oversold territory. MACD is confirming, having staged a bearish crossover while remaining in negative territory. With downside momentum rebuilding, the technical picture continues to favour short setups over longs.
Gold's shellacking stands out against history
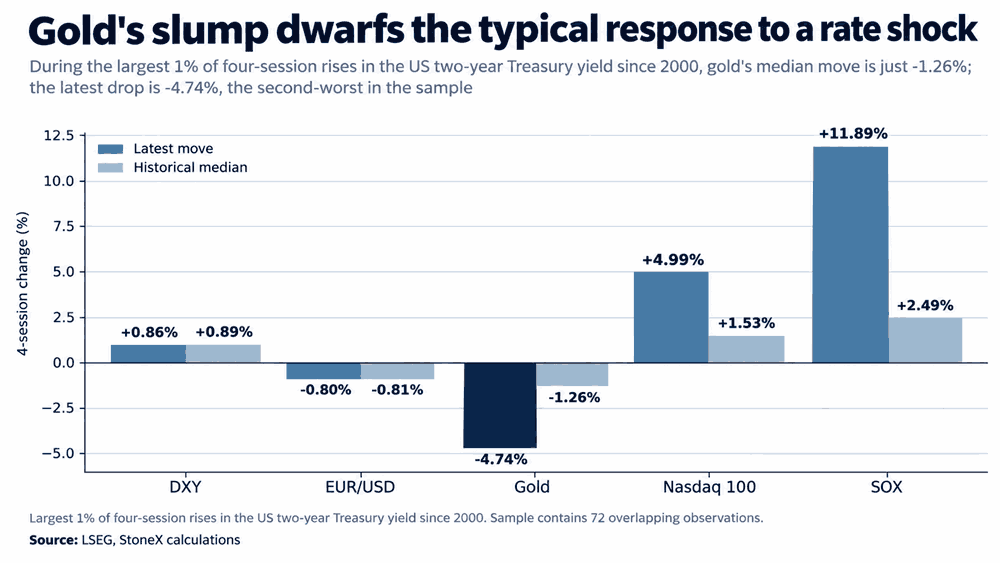
While the move in EUR/USD has been much as you'd expect given the shift in relative interest rate outlooks, the shellacking in gold has been one for the ages, with the decline far larger than typically seen during comparable hawkish yield shocks in the past.
Source: LSEG
Looking at the largest 1% of four-session increases in US two-year Treasury yields since 2000, gold has typically fallen around 1.26%, which makes sense given its inverse relationship with interest rates and the fact it offers no yield. But this week, it's plunged 4.74%, the second-largest decline among 72 overlapping observations over the same period, far larger than what you'd normally expect during a move of this magnitude.
Nor can the dollar's rally explain all the weakness. DXY has risen 0.85% over the same period, which, based on gold's sensitivity to dollar movements before the sell-off, as covered in separate analysis yesterday, would imply a decline of around 2%. Instead, gold has fallen more than twice as much, suggesting other influences may be compounding the selling pressure.
Gold's bearish trend remains intact
Source: TradingView
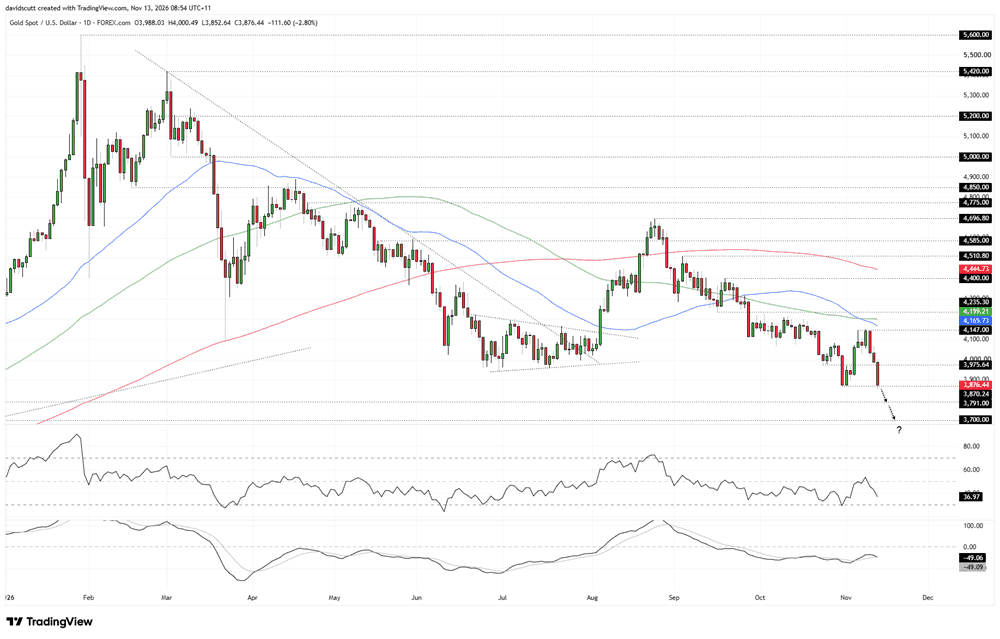
As flagged in Thursday's research piece, support at $3,975 eventually buckled heading into the European session, seeing gold trade down to and briefly beneath the previous 2026 low at $3,870.24. The price has since managed to reclaim that level, making it the immediate focal point underneath where it now trades, with $3,975 the level to watch overhead given its previous role as both support and resistance.
While gold has managed to reclaim $3,870.24, the prevailing bearish trend, with the price sitting beneath all its key medium- and long-term moving averages, all of which carry a negative slope, along with the signals from the momentum oscillators, suggests directional risks remain skewed to the downside, favouring short setups over longs.
If $3,870.24 breaks cleanly, levels to watch include $3,791 and $3,700. Neither is significant, having only acted as breakout zones during gold's rally in the second half of last year.
Alternatively, if gold continues to hold above $3,870.24, the option is to look for a counter-trend squeeze back towards $3,975 or even $4,147, where the price stalled on several occasions earlier this month. But for that trade to pay off, we'd likely need to see a decent unwind in the upward thrust in US Treasury yields and the dollar seen this week.
Williams, PPI pose the next major risks
As for what could spark such a move from a fundamental perspective, attention now shifts to New York Fed President John Williams, who is scheduled to speak shortly during a panel discussion, followed by the release of the US producer price inflation report for October later on Friday.
Williams has generally been towards the more dovish end of the Fed spectrum until recently, so any pushback against the aggressive tightening now priced into markets could help take some heat out of Treasury yields and the dollar. However, with Fed funds futures already pricing 29.1 basis points of tightening in December and a cumulative 47.1 basis points by January, it would likely take a shockingly weak PPI report to seriously challenge expectations for a December hike.
Conversely, should Williams join the hawkish chorus or PPI deliver another hot inflation print, it could stir the pot further, raising the risk of a 50 basis point hike in December, something markets currently assign a probability of around 16%.