



Market Brief Looking Vulnerable For Another Round Of Risk Off
A summary of news and snapshot of moves from today’s Asia session.
Share this:

Equity Brief:
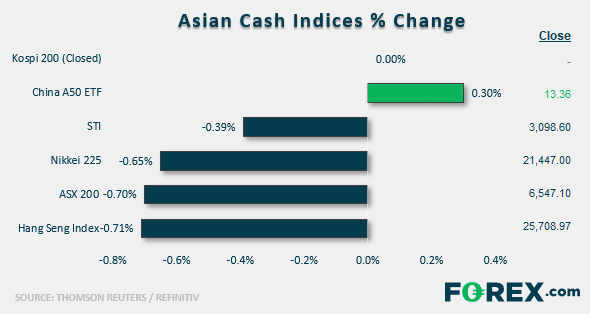
- Key Asian stock markets have almost given up the gains accumulated since the start of the week; taking the cue from the sell-off seen in U.S. stocks overnight. Right now, the U.S. administration has upped its hawkish stance towards China where visa bans have been imposed on Chinese officials linked to violation of human rights over Muslims in the Xinjiang region on top of the recent blacklist of eight Chinese technology firms over similar human rights violation.
- The mood has turn sombre for a positive break through on the upcoming two days of high-level U.S-China trade negotiation talks in Washington that will kickstart on Thurs, 10 Oct. Also, SCMP have reported that the highest ranking official from the Chinese delegation, Vice Premier Lui He will not carry the title of “special envoy” for the upcoming trade talks, an early indication that Lui He has received no particular instructions from China President Xi and a source has told SCMP that the Chinese delegation may cut short its stay in Washington.
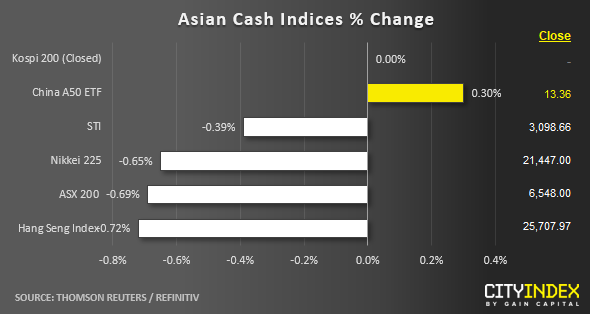
- Hong Kong’s Hang Seng Index has continued to slide where it recorded a slide of -0.71% as at today’s Asia mid-session towards its 10-day low of 25600. Financials, properties and technology related stocks are the worst performers where Hang Seng Bank, AAC Technologies and CK Asset Holdings have declined by -3.39%, 3.26% and -2.20 % respectively.
- South Korea’s Kospi 200 is closed today for a public holiday. The S&P 500 E-mini futures has managed to shape a bounce of 0.20% to print a current intraday high of 2903 in today’s Asian session after a decline of -1.56% seen in the U.S. session. However, the current bounce does not look like a potential bullish reversal from a technical analysis perspective.
FX Brief:
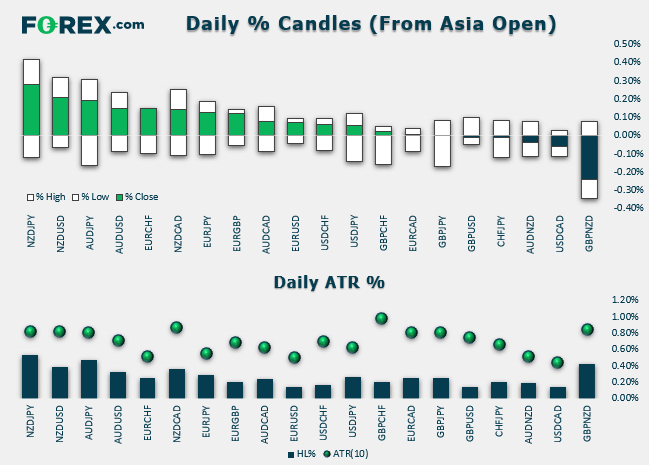
- After a sell-off in the GBP seen yesterday (the weakest currency in the overnight U.S. session) reinforced by the dim prospect of getting EU approval on U.K PM Boris Johnson’s latest Brexit proposal, the GBPUSD has traded in a tight range of 13 pips in today’s Asian session.
- The antipodean currencies are the best performers so far where the NZD/JPY AUD/JPY, NZD/USD and AUD/USD have recorded modest gains between 0.15% to 0.28% but these gains are questionable in the backdrop of an escalation in political tension between U.S and China where it may derail any positive outcome on the upcoming high-level U.S-China trade talk.
Up Next
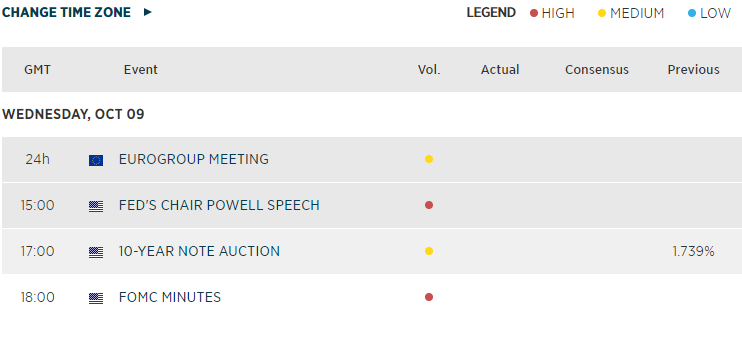
- Fed Chair’s Powell speech (the third & last for this week) and FOMC minutes on the Sep meeting. In yesterday’s speech at the National Association for Business Economics Annual Meeting, Fed Chair Powell has indicated that Fed will start to grow its balance sheet soon to counter the recent turmoil seen in the repo market and open the door for another interest rate cut in the upcoming Oct FOMC meeting.
Economic Calendar
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
Equity Brief:
- Key Asian stock markets have almost given up the gains accumulated since the start of the week; taking the cue from the sell-off seen in U.S. stocks overnight. Right now, the U.S. administration has upped its hawkish stance towards China where visa bans have been imposed on Chinese officials linked to violation of human rights over Muslims in the Xinjiang region on top of the recent blacklist of eight Chinese technology firms over similar human rights violation.
- The mood has turn sombre for a positive break through on the upcoming two days of high-level U.S-China trade negotiation talks in Washington that will kickstart on Thurs, 10 Oct. Also, SCMP have reported that the highest ranking official from the Chinese delegation, Vice Premier Lui He will not carry the title of “special envoy” for the upcoming trade talks, an early indication that Lui He has received no particular instructions from China President Xi and a source has told SCMP that the Chinese delegation may cut short its stay in Washington.
- Hong Kong’s Hang Seng Index has continued to slide where it recorded a slide of -0.71% as at today’s Asia mid-session towards its 10-day low of 25600. Financials, properties and technology related stocks are the worst performers where Hang Seng Bank, AAC Technologies and CK Asset Holdings have declined by -3.39%, 3.26% and -2.20 % respectively.
- South Korea’s Kospi 200 is closed today for a public holiday. The S&P 500 E-mini futures has managed to shape a bounce of 0.20% to print a current intraday high of 2903 in today’s Asian session after a decline of -1.56% seen in the U.S. session. However, the current bounce does not look like a potential bullish reversal from a technical analysis perspective.
FX Brief:
- After a sell-off in the GBP seen yesterday (the weakest currency in the overnight U.S. session) reinforced by the dim prospect of getting EU approval on U.K PM Boris Johnson’s latest Brexit proposal, the GBPUSD has traded in a tight range of 13 pips in today’s Asian session.
- The antipodean currencies are the best performers so far where the NZD/JPY AUD/JPY, NZD/USD and AUD/USD have recorded modest gains between 0.15% to 0.28% but these gains are questionable in the backdrop of an escalation in political tension between U.S and China where it may derail any positive outcome on the upcoming high-level U.S-China trade talk.
Up Next
- Fed Chair’s Powell speech (the third & last for this week) and FOMC minutes on the Sep meeting. In yesterday’s speech at the National Association for Business Economics Annual Meeting, Fed Chair Powell has indicated that Fed will start to grow its balance sheet soon to counter the recent turmoil seen in the repo market and open the door for another interest rate cut in the upcoming Oct FOMC meeting.
Economic Calendar
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
ASX 200 Outlook: Potential to Bounce Sits on a Knife Edge
ASX 200 bounce prospects remain on a knife edge as oversold technicals clash with weak financials, commodity pressures and global risk aversion.

GBP/USD, GBP/JPY, GBP/AUD: Sterling Eyes UK Inflation Catalyst
Sterling faces a pivotal UK inflation test as traders weigh BoE tightening, Fed minutes and Australian employment data across GBP/USD, GBP/JPY and GBP/AUD.

USD/MXN Forecast: Is Super Peso Making a Comeback?
The latest trading sessions have once again highlighted the strength of the Mexican peso. The currency has managed to regain a consistent appreciation trend in the short term, even despite the renewed strength displayed by the U.S. dollar in recent sessions.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.