


Markets Brace for Nvidia Earnings | DAX Near Oversold Zone, Trump buys Bonds
Global markets traded cautiously ahead of Nvidia’s earnings, expected to trigger a record USD 320 bn market-cap swing. US stocks fell, led by tech weakness and fading rate-cut hopes. The DAX extended its slide toward 23,000, entering oversold territory with momentum still weak. Fed officials flagged liquidity stress and hinted at early 2026 balance-sheet expansion. Washington’s tariff cuts and US–Brazil rare-earth cooperation added geopolitical texture, while Apple, Google, and AMD led corporate highlights. Focus shifts to Nvidia’s results and the December FOMC outlook.
Share this:

Market Summary – 19 November 2025
Nvidia Earnings Preview
- Record stakes: Options imply a ~7 % post-earnings move in Nvidia, equivalent to a USD 320 bn market-cap swing—potentially the largest single-day change ever for any company.
- Focus: Investors seek clarity on whether the AI boom is accelerating or cooling. Results are due after the US close Wednesday.
- Context: At ~USD 4.6 trn valuation, Nvidia’s report is viewed as the key sentiment driver for the AI sector this quarter.
Corporate & Sector Highlights
- Apple: Captured 25 % of China’s smartphone market in October, with iPhone 17 sales up 37 % YoY. Overall Chinese smartphone sales rose 8 % YoY.
- Google: Shares hit new highs after Berkshire Hathaway revealed a USD 4.9 bn stake, reinforcing confidence following strong earnings and resilience during the AI pullback.
- US Small Business Sentiment (BoA):
- 74 % of small/mid-sized firms expect higher revenue next year; ~60 % plan expansion.
- Confidence hinges on tariff stability (53 %), cooling inflation (52 %), and lower rates (52 %).
- Profitability for small firms remains resilient in 2025.
Germany: Q3 Earnings Season
- DAX companies: Aggregate profit +2 % YoY, driven by financials, healthcare, and energy tech.
- Auto sector: Earnings –60 % YoY, offsetting broader strength; without autos, total growth would have been +15 ppt higher.
- Outlook: Analysts see –9 % Q4 profit decline, but potential rebound +14 % in 2026 as exports and sentiment stabilize.
Germany 40 Technical Analysis
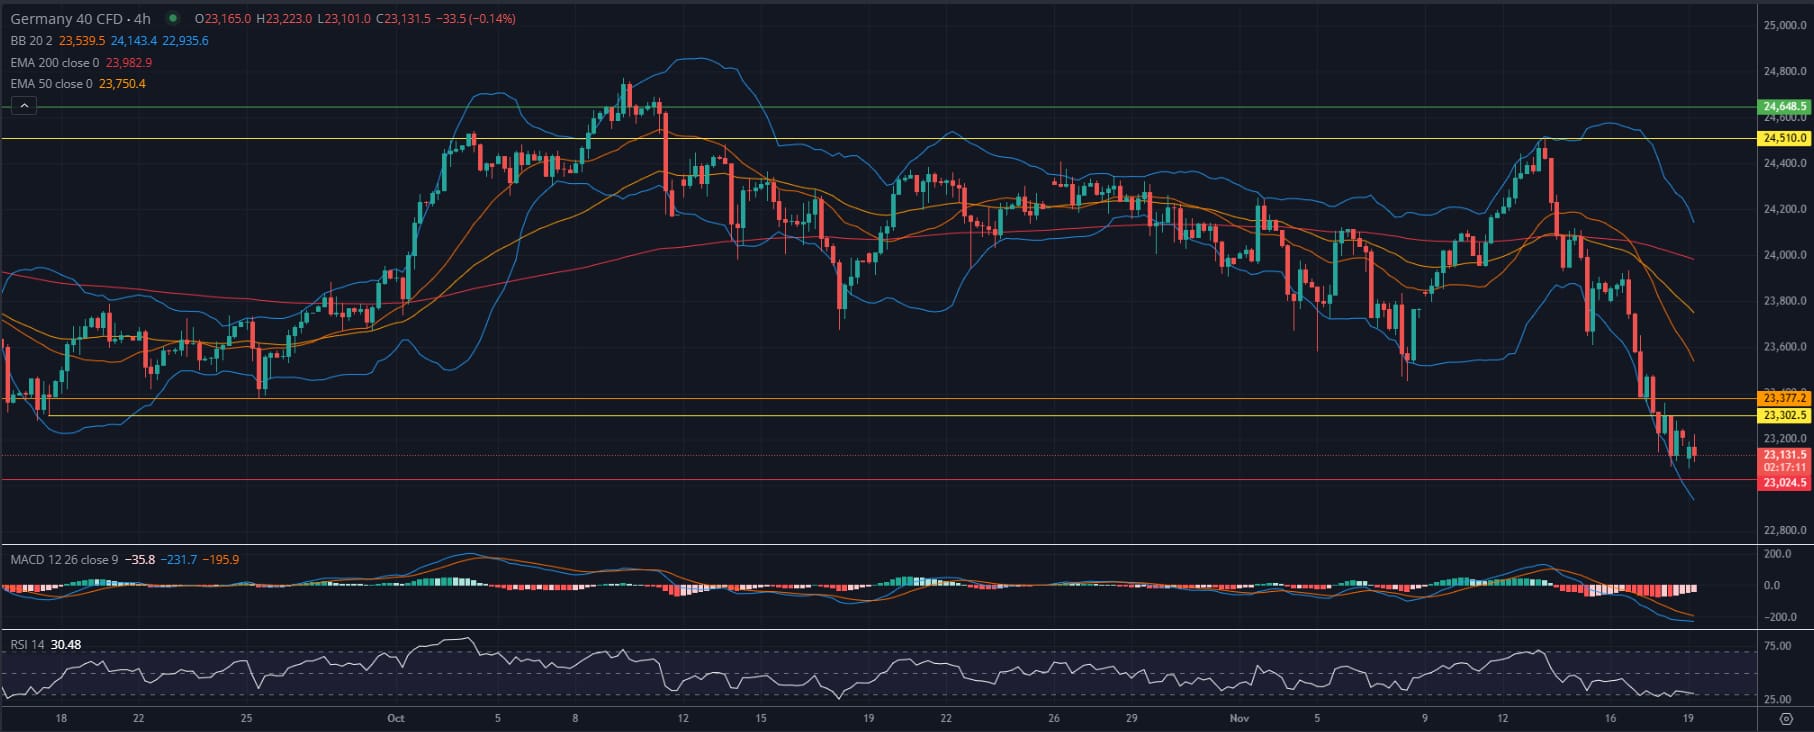
The Germany 40 CFD (4H) remains in a downtrend, extending its decline after breaking below key support at 23,300. Price is now testing the 23,100–23,000 zone, aligning with the lower Bollinger Band and near the March swing low, a critical support area. The RSI (30) is deeply oversold, indicating potential for a technical rebound, though momentum remains weak. The MACD is entrenched in negative territory, confirming persistent downside pressure.
Immediate resistance sits at 23,300–23,380, with stronger supply expected near 23,750 (50 EMA). A recovery above those levels would signal stabilization, while a breakdown below 23,000 risks further downside toward 22,800–22,600. Tone: bearish trend intact, but nearing oversold rebound territory.
Federal Reserve – Rates & Liquidity
- Policy tension: Debate over a possible December rate cut continues as liquidity pressures rise.
- Repo strains: Overnight repo rates exceeding the Fed’s Interest on Reserve Balances (IORB) indicate tight bank reserves.
- Likely response: Market expects the Fed to expand its balance sheet from Jan 2026, adding USD 20 bn/month in T-bills and USD 15 bn/month in MBS reinvestments to prevent year-end repo stress.
- Short-term relief: Treasury’s general account drawdown (~USD 100 bn) and Standing Repo Facility (SRF) usage should temporarily ease pressure.
- Key focus for December FOMC: not only rates, but also liquidity-management guidance.
US Tariffs & Trade
- Food imports: Tariffs cut on coffee, bananas, tomatoes, beef, reducing the average agricultural duty 13.0 % → 10.3 %.
- Swiss goods: Tariffs reduced 39 % → 15 %; Switzerland pledges USD 200 bn US investment (mainly pharma) by 2028.
- Growth impact: Lower tariffs could lift Swiss GDP +0.3–0.5 ppt annually from 2026; CHF strength (0.918/EUR) remains a drag.
Rare Earths & Brazil
- Brazil–US partnership talks: Brazil, holder of the world’s second-largest rare-earth reserves (21 mt), aims to boost output from 20 t to rival China’s 270 t.
- Sector outlook: Brazilian mining P/E 7.1 vs China 13.0—seen as undervalued; new cooperation could diversify US supply chains away from China.
US Real Estate
- Commercial rebound: Q3 2025 transactions +17 % YoY, driven by multifamily, logistics, and data-centre assets.
- Catalyst: September’s 25 bp Fed rate cut improved sentiment; investors favour income-producing, inflation-resilient assets.
Trump’s Portfolio Disclosure
- Total new investments: ≥ USD 82 mn (Aug–Oct), spanning corporate and municipal bonds.
- 175 transactions filed under federal ethics rules.
- Corporate bonds purchased: Broadcom, Qualcomm, Meta, Intel, Home Depot, CVS, Goldman Sachs, Morgan Stanley, JPMorgan.
- Strategic link: Intel bond purchase followed government stake acquisition under Trump’s direction, prompting scrutiny over overlap.
- Theme: Positions align with domestic manufacturing, tech independence, and infrastructure priorities.


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.