


Markets Rally on Softer US CPI | Tech Leads, DAX Reclaims Bullish Structure
US equities rebounded on softer CPI, lifting rate-cut expectations and powering a tech-led rally, with semiconductors outperforming. Shutdown-distorted labour and consumption data kept macro uncertainty elevated, while Japan’s rate hike pushed yields to multi-year highs. Eurozone inflation stayed near target, resource stocks surged, and the DAX regained bullish momentum above key Fibonacci levels. Market tone: constructive but prone to near-term volatility.
Share this:
Market Summary
Equities & Rates
- US equities rebounded after softer-than-expected November CPI boosted rate-cut expectations.
- Nasdaq +1.38%, S&P 500 +0.79%, Dow +0.14%.
- Markets now price a 58% chance of Fed easing by March.
- Tech outperformed:
- Micron +10.2% on strong AI-driven profit guidance, lifting semiconductor peers; the Philadelphia Semi Index +2.6%.
- Trump Media +41% after announcing a $6bn all-share merger with TAE Technologies.
- Lululemon +3.5% on reports of a major activist stake.
Asia
- Asian markets followed the US tech rally.
- Nikkei +1%+ after the BoJ hiked rates to 0.75% and hinted at further tightening; Topix +0.8%.
- JGB yields hit ~2%, highest since 2006, as investors assess the BoJ’s tightening trajectory.
Macro
US labour, inflation, and consumption data were distorted by the shutdown
- Jobs:
- October’s reported –105k jobs entirely reflected the DOGE deferred resignation program, which removed 162k federal jobs on paper.
- Private payrolls were actually +52k in Oct and +69k in Nov.
- Unemployment rose to 4.6% mostly due to temporary layoffs of furloughed federal workers.
- Retail sales:
- Headline flat in October, but:
- Auto sales –1.6% after EV credit expiry pulled demand forward.
- Gasoline spending –0.8% thanks to lower prices.
- Online sales +1.5%, showing early holiday buying strength.
- Headline flat in October, but:
- Inflation:
- Headline CPI eased to 2.7% YoY (vs 3.0% Sep).
- Core CPI slowed to 2.6% (vs 3.0% expected).
- Shutdown disruptions — with data collection beginning only Nov 14 — may have artificially depressed some categories such as core goods.
- Market reaction:
- Treasury yields fell only slightly (10-yr ~4.1%).
- Equity indices, still down ~2% on the week, remain driven by concerns about AI investment intensity, not macro relief alone.
Nasdaq-100 Reconstitution (December)
Removed: TTD, LULU, ON, CDW, GFS, BIIB
Added: FER, MPWR, ALNY, WDC, STX, INSM
Eurozone
Inflation near target — ECB on hold
- November Eurozone CPI to be published tomorrow, but major countries released early data:
- Germany HICP: 2.6% (highest in nine months; above 2.4% consensus).
- Spain: 3.1% (above consensus).
- Italy: 1.1% (well below consensus).
- ECB sees stable inflation path and expects moderate growth (2025–2028: 1.2–1.4%).
- Markets showed little reaction as US CPI dominated attention.
Europe – Resources Sector
- European resource stocks gained >20% over the last three months.
- Drivers: sharp rises in copper, aluminium, silver, gold; copper boosted by supply disruptions at a major mine and low inventories.
- After ~14% earnings decline in 2025, analysts expect >30% EPS growth in 2026.
- Sector trades at ~14x forward earnings, ~25% above its 20-year median → increased risk of volatility next year.
DAX
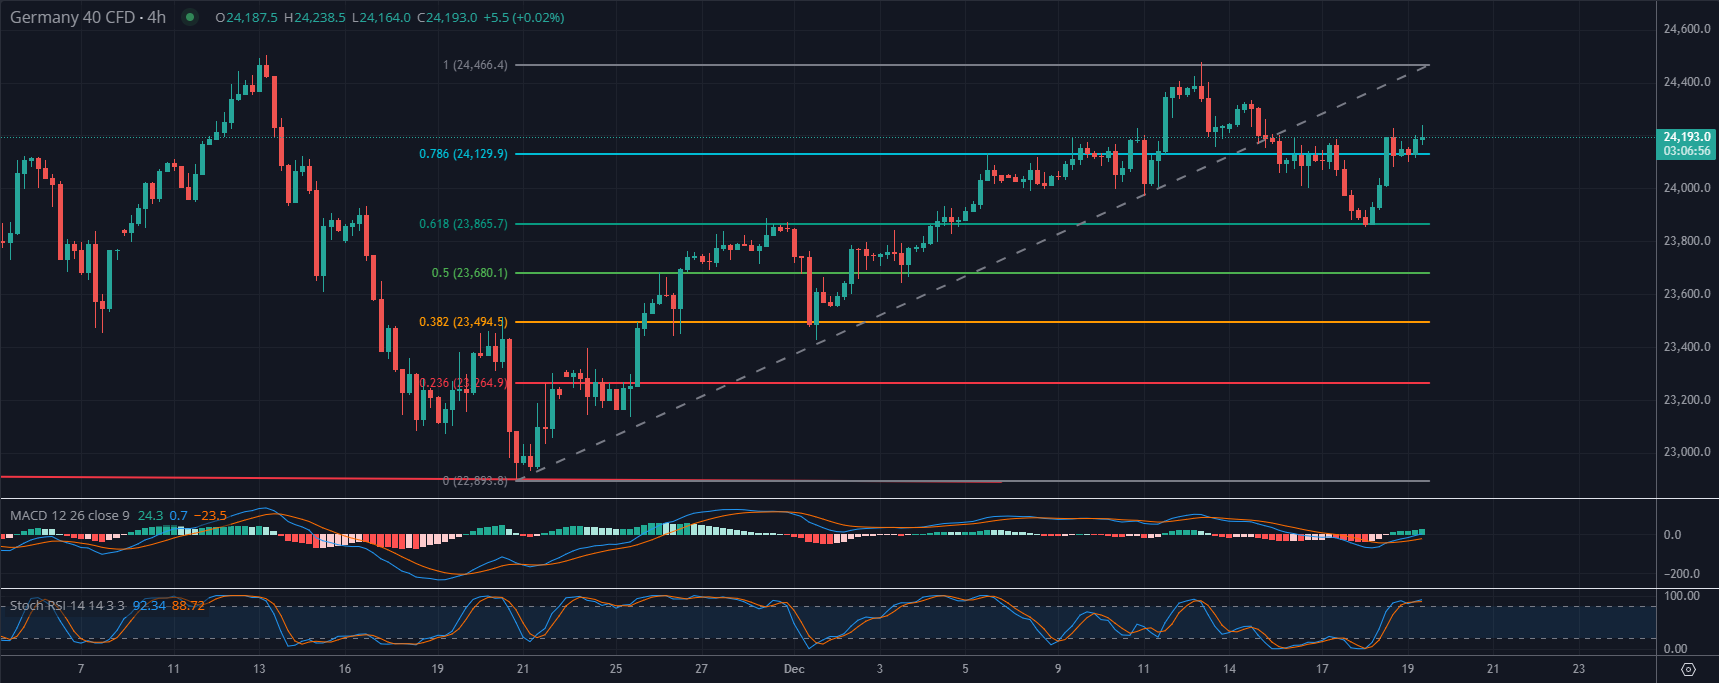
The 4-hour chart for Germany 40 shows a strong recovery after the recent correction, with price now trading at 24,193.6 and holding above the ascending trendline drawn from late November. The index has reclaimed the 24,129 level, which corresponds to the 78.6% Fibonacci retracement of the prior bullish leg, signaling renewed buying pressure. The short-term structure is bullish again, as price is consolidating above the broken trendline and near the upper retracement zone. The next resistance is the recent high at 24,466.4, while immediate support lies at 24,129 and then 23,857 (61.8% Fib).
Momentum indicators confirm the bullish shift. MACD has crossed into positive territory, with the histogram expanding, indicating strengthening upward momentum. Stochastic RSI at 88.72 is in overbought territory, suggesting the rally may face short-term exhaustion or consolidation before another leg higher. If price sustains above 24,129, the next upside target is 24,466.4; failure to hold this level could trigger a pullback toward 23,857 and 23,681 (50% Fib). The technical bias favors continuation toward the recent high, but overbought conditions warrant caution for near-term volatility.
In short: Markets rallied on softer US inflation and strong semiconductor momentum, even as underlying US data remain distorted by the shutdown. Japan tightened policy, pushing yields to multi-year highs. Eurozone inflation remains close to target, resource stocks surged on supply tightness, and the Nasdaq-100 will see notable constituent changes.
-Philip Papageorgiou – Market Analyst
--X ex Twitter: PhilipForexCom


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.