



Mining stock recovery remains distant
China’s economy shows signs of stabilisation though industry views reveal pessimism
Share this:

China’s economy shows signs of stabilisation though industry views reveal pessimism
Base metal mining and steel shares led resurgent European stock markets on Friday following some reassuring aspects in Eurozone data. The gains, which saw the big four—BHP, Rio, Glencore and Anglo rise 2%-to-3% each—partly reflecting relief. The industry has been led a merry dance over the last couple of years as deteriorating relations between Washington and Beijing have exacerbated China’s economic slowdown, chilling miners and metal producers’ most important market.
The early part of 2019’s final quarter appeared to show signs of a turn for the better. Chinese data looked set to stabilize, at least on the surface. Readings showing higher than forecast inflation, PMIs, and steady growth so far this year, roughly coincided with a rebound of mining and metal stocks. Bloomberg’s Europe Mining Index has erased a 4% loss that underperformed the FTSE 100 by some 9 percentage points by mid-August to trade around 9% higher over the year-to-date by Friday. That’s now in line with benchmark’s 2019 rise.
Dither and uncertainty continues to characterise prospects for a ‘phase-one’ trade deal, though sentiment has been underpinned by outward progress of talks since a tentative agreement collapsed in May. The tail-off of declines in Chinese indicators together with a calmer trade outlook has even prompted analysts at some banks to upgrade some mineral volume forecasts. For instance, Citigroup now expects a recovery across many mined commodities, except thermal coal, over the next four quarters. That view, as well as a mellower take by investors on trade sees European steel makers ArcelorMittal, Salzgitter and SSAB rise some 2% to 4%.
No one believes the miners and metal makers are in the clear, of course. JPMorgan’s global manufacturing PMI rose in October, though remained below 50, denoting continued broader contraction, despite China’s resilience. Even there, October credit data and a complete standstill of new infrastructure approvals counters improving conditions elsewhere. Little wonder sentiment at the LME’s recent industry event was reportedly ‘unenthusiastic’, particularly about copper, in which demand growth is expected to average below 2% over the next few years. The underlying consensus seems to be that the demand outlook remains too uncertain for markets and producers to fully commit to more optimism.
Sentiment is aptly demonstrated by the normalised chart of FTSE 100 miners below. The best performer in the year to date is Anglo American, standing 18% ahead on Friday. But it had been almost 30% higher in July. EVRAZ, the UK-listed Russian steel and mining firm gained about 50% into the mid-year only to erase the advance and slump to a 25% loss this week. Investors clearly aren’t expecting a demand recovery across metals in the near term.
Normalised: FTSE 100 mining stocks, year to date
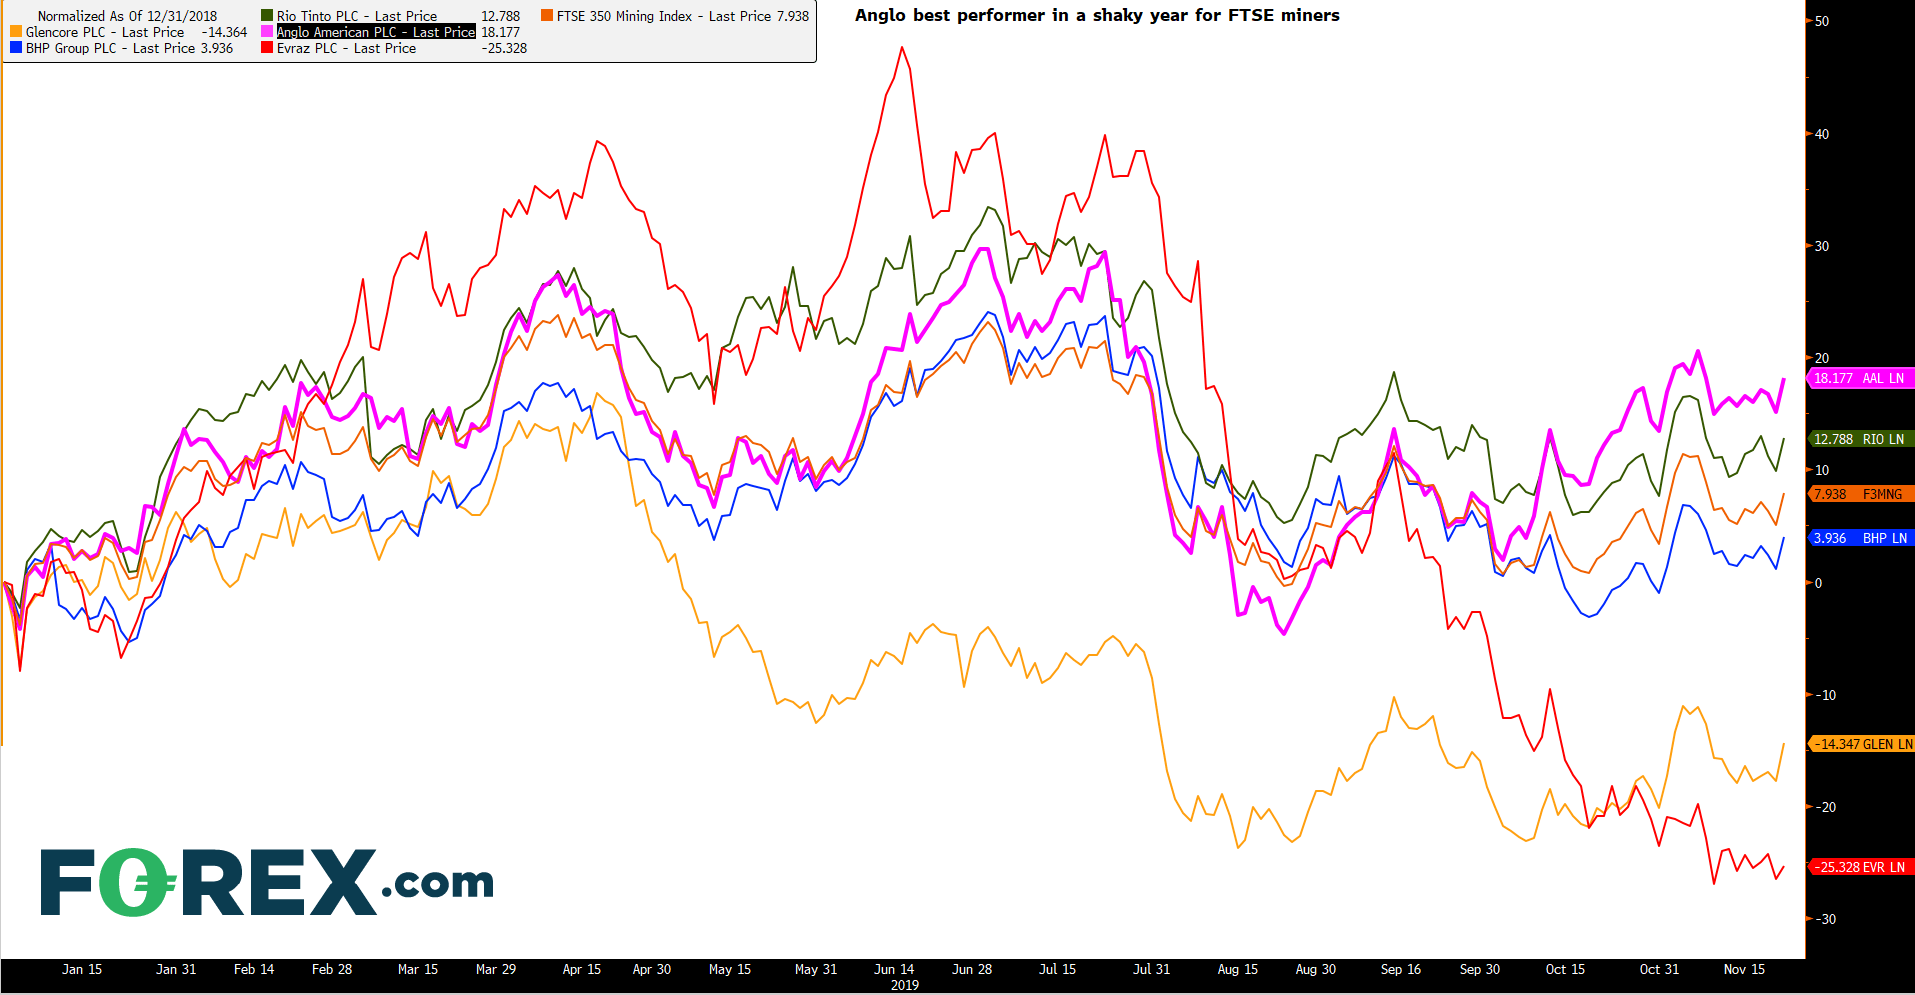
Source: Bloomberg/FOREX.com
China’s economy shows signs of stabilisation though industry views reveal pessimism
Base metal mining and steel shares led resurgent European stock markets on Friday following some reassuring aspects in Eurozone data. The gains, which saw the big four—BHP, Rio, Glencore and Anglo rise 2%-to-3% each—partly reflecting relief. The industry has been led a merry dance over the last couple of years as deteriorating relations between Washington and Beijing have exacerbated China’s economic slowdown, chilling miners and metal producers’ most important market.
The early part of 2019’s final quarter appeared to show signs of a turn for the better. Chinese data looked set to stabilize, at least on the surface. Readings showing higher than forecast inflation, PMIs, and steady growth so far this year, roughly coincided with a rebound of mining and metal stocks. Bloomberg’s Europe Mining Index has erased a 4% loss that underperformed the FTSE 100 by some 9 percentage points by mid-August to trade around 9% higher over the year-to-date by Friday. That’s now in line with benchmark’s 2019 rise.
Dither and uncertainty continues to characterise prospects for a ‘phase-one’ trade deal, though sentiment has been underpinned by outward progress of talks since a tentative agreement collapsed in May. The tail-off of declines in Chinese indicators together with a calmer trade outlook has even prompted analysts at some banks to upgrade some mineral volume forecasts. For instance, Citigroup now expects a recovery across many mined commodities, except thermal coal, over the next four quarters. That view, as well as a mellower take by investors on trade sees European steel makers ArcelorMittal, Salzgitter and SSAB rise some 2% to 4%.
No one believes the miners and metal makers are in the clear, of course. JPMorgan’s global manufacturing PMI rose in October, though remained below 50, denoting continued broader contraction, despite China’s resilience. Even there, October credit data and a complete standstill of new infrastructure approvals counters improving conditions elsewhere. Little wonder sentiment at the LME’s recent industry event was reportedly ‘unenthusiastic’, particularly about copper, in which demand growth is expected to average below 2% over the next few years. The underlying consensus seems to be that the demand outlook remains too uncertain for markets and producers to fully commit to more optimism.
Sentiment is aptly demonstrated by the normalised chart of FTSE 100 miners below. The best performer in the year to date is Anglo American, standing 18% ahead on Friday. But it had been almost 30% higher in July. EVRAZ, the UK-listed Russian steel and mining firm gained about 50% into the mid-year only to erase the advance and slump to a 25% loss this week. Investors clearly aren’t expecting a demand recovery across metals in the near term.
Normalised: FTSE 100 mining stocks, year to date
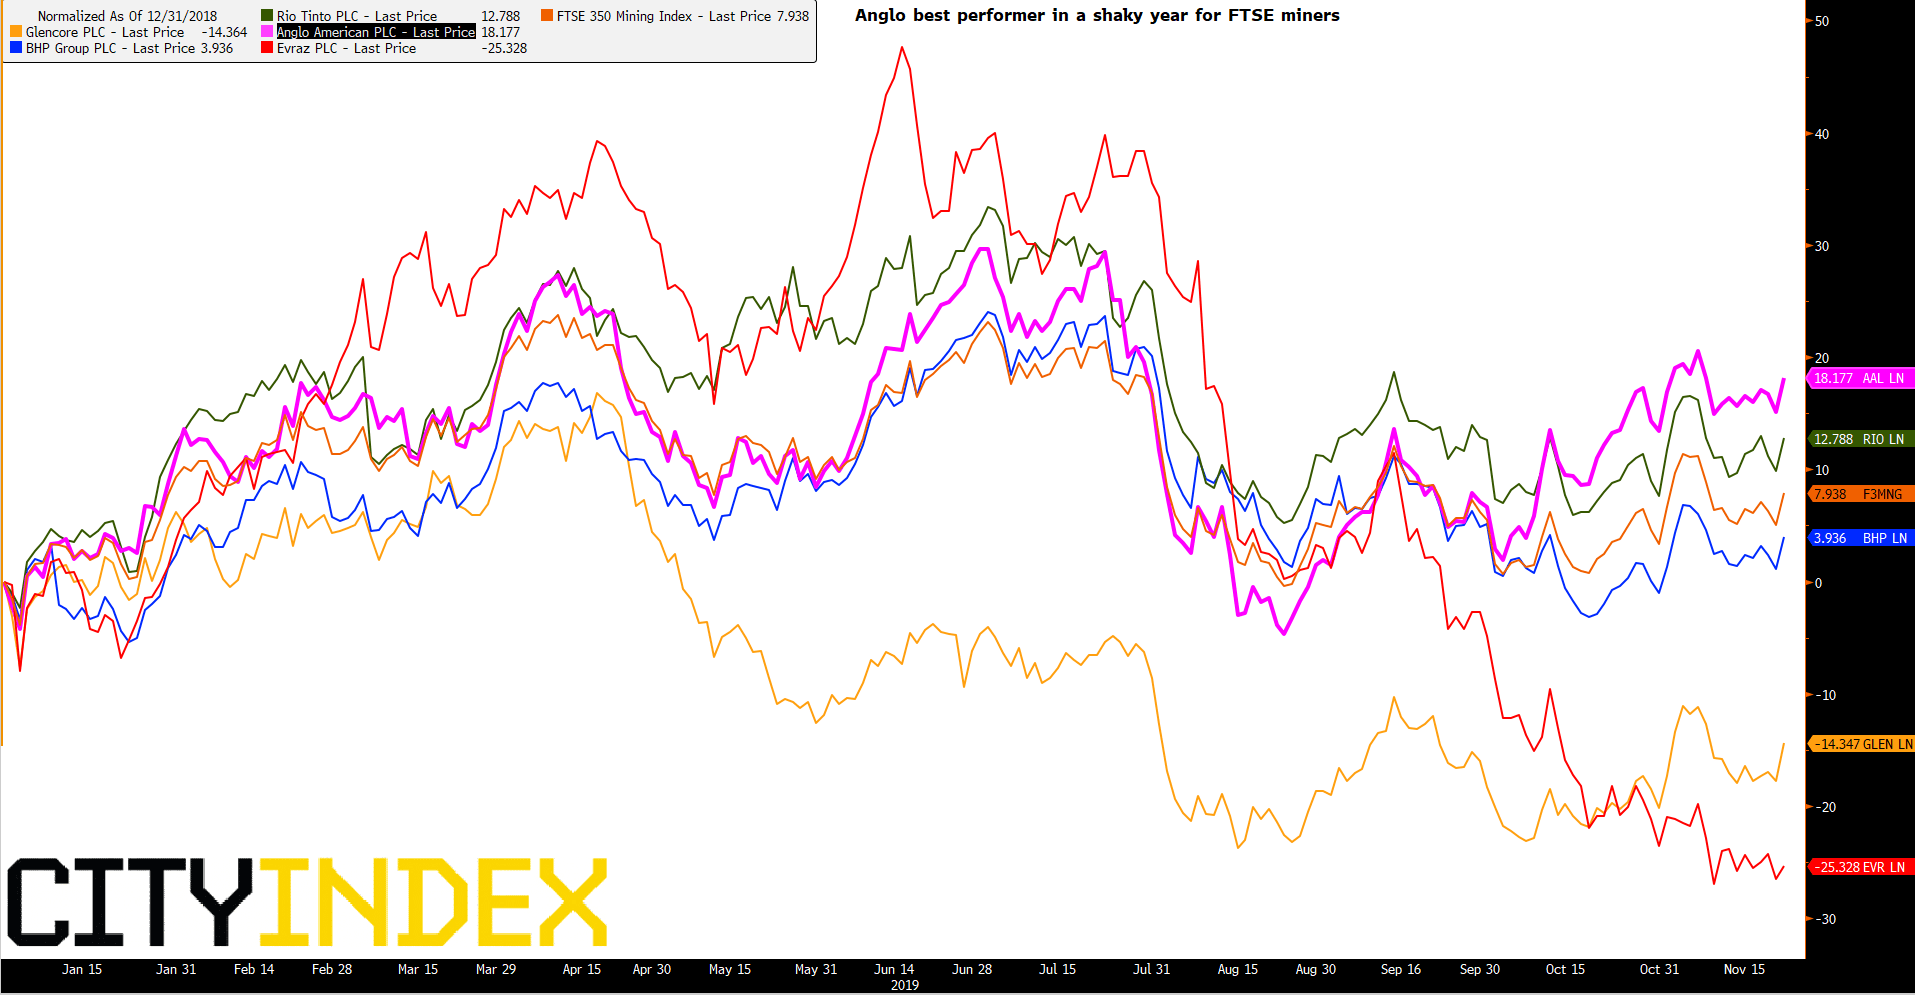
Source: Bloomberg/City Index
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.
Tankers Still Get Hit but Brent Crude Oil Keeps Falling
Brent crude oil has turned bearish after breaking its uptrend, as de-escalation signals outweigh tanker strikes near the Strait of Hormuz.

Gold Feels the Weight of USD, Yields on Hawkish Fed and CPI
Gold remains under pressure as hot US CPI, rising Treasury yields and hawkish Fed commentary support the US dollar. Bears eye another break below $4,000

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.