US futures
Dow futures -0.35%, S&P futures 0.03% & Nasdaq futures 0.38%
In Europe
FTSE 0.13% & DAX 0.45%
- U.S. stocks are mixed after hot PPI data.
- The summit between President Trump and China’s Xi Jinping is in focus.
- Chip stocks rally after losses yesterday
- Oil holds steady as demand set to rise above supply
US stocks are mixed as PPI inflation surges and yields climb
US stocks are mixed ahead of the open as investors digest a sharp rise in US producer price inflation and turn attention towards President Trump’s summit with Xi Jinping in Beijing.
US producer prices accelerated sharply in April, with wholesale inflation rising at the fastest pace since 2022 as higher energy costs filtered through into transportation and supply chain expenses.
PPI rose 6% year-on-year, well above expectations of 4.9%, while the monthly increase of 1.2% marked the strongest gain in four years. Producer prices are often viewed as a leading indicator for consumer inflation, suggesting CPI could remain elevated in the months ahead.
Following the data, Treasury yields moved higher, with the 10-year yield climbing to its highest level since July near 4.49%. The US dollar also strengthened, creating a less supportive backdrop for equities.
Even so, the tech-heavy Nasdaq is outperforming broader indices as markets focus on the Trump–Xi summit and the presence of several high-profile US corporate leaders.
NVIDIA is trading higher premarket after co-founder Jensen Huang was added to the US delegation at the last minute. Micron Technology, Qualcomm, Tesla and Boeing are also advancing as their executives participate in the summit discussions.
Talks are expected to focus on tariffs and trade across key sectors including aerospace, critical minerals and advanced technology.
Corporate movers
Alibaba Group’s US-listed shares are down around 3% after the Chinese e-commerce group reported an 84% drop in Q1 profit alongside a sharp increase in AI-related investment spending.
Micron Technology, NVIDIA and several chipmakers are rebounding after weakness in the previous session, when Micron fell more than 3.5% following a sharp two-day rally of over 23%.
Birkinstock is down more than 5% after missing expectations on both earnings and revenue in its fiscal second quarter. The company said demand across Europe, the Middle East and Africa had been impacted by the ongoing geopolitical conflict.
Nasdaq 100 – Technical analysis
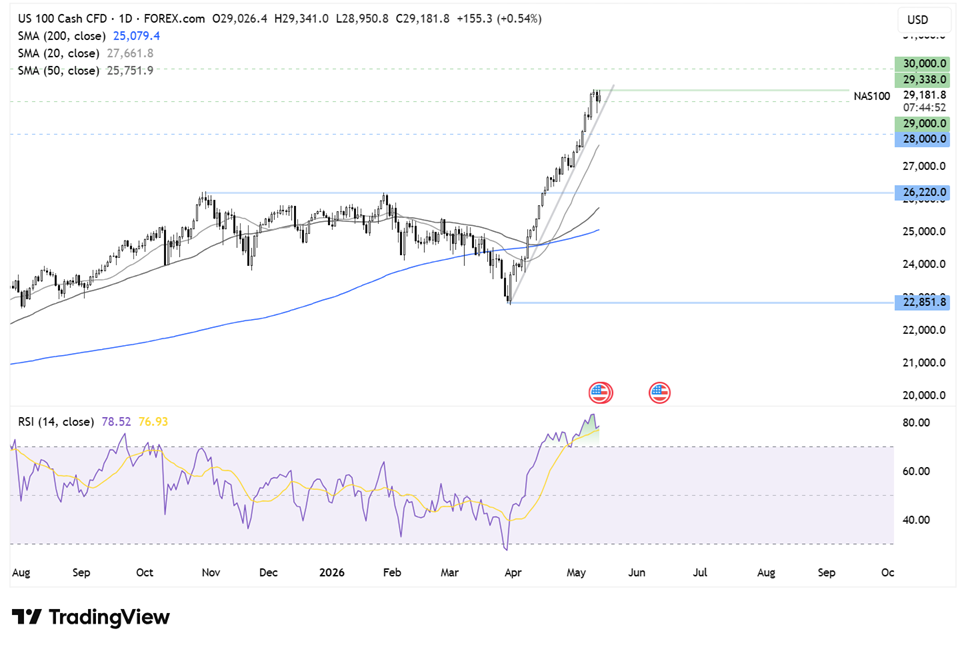
The Nasdaq 100 has extended its recovery from the 22,800 low, rallying to a fresh record high near 29,360 before easing back towards 29,130. The RSI remains deeply overbought, suggesting some consolidation or a near-term pullback may continue.
With no clear signs of reversal yet, buyers will look for a move above 29,360 to target fresh record highs towards the key 30,000 level.
Initial support is seen around 29,000. Below there, the 20-day SMA near 27,660 comes into focus.
A decline below 26,200 — the February and 2025 high — would be needed to materially weaken the broader bullish trend.
FX markets – US dollar strengthens
The US dollar is rising to a two-month high amid persistent Middle East uncertainty and after both CPI and PPI inflation surprised to the upside, reinforcing expectations that the Federal Reserve may need to tighten policy further later this year.
EUR/USD is falling on dollar strength after eurozone data showed economic growth slowed further as higher energy costs and weak industrial activity weighed on momentum. Eurozone GDP expanded just 0.1% in Q1, down from 0.2% in Q4 2025, while employment growth also cooled.
GBP/USD is weakening amid broader dollar strength and continuing political uncertainty in the UK. Keir Starmer remains under pressure as reports suggest divisions within the government are intensifying, with speculation surrounding a possible resignation from senior cabinet members. The uncertainty has pushed gilt yields higher and weighed on sterling as investors reassess UK political risk.
Oil supported as supply concerns persist
Oil prices are broadly steady on Wednesday as markets continue to monitor the fragile Middle East ceasefire and the Trump–Xi summit.
Both Brent and WTI crude remain near the $100 per barrel level, with prices highly sensitive to developments surrounding the Strait of Hormuz, which remains effectively closed.
Any signs of renewed escalation continue to trigger sharp moves higher in crude prices.
Additional support came from the International Energy Agency, which warned that global oil supply may fail to meet demand this year because of ongoing disruptions linked to the conflict.
Current estimates suggest around one billion barrels of supply have been disrupted since the conflict began, implying oil prices could remain structurally elevated even if the Strait eventually reopens.