


New Zealand Dollar Forecast: NZD/USD slides as RBNZ tempers rate expectations
The RBNZ delivered a fully priced hold, but its projected tightening path fell short of market expectations, sending the Kiwi lower. Near-term pressure may persist, even as the broader uptrend remains intact for now.
Share this:
- RBNZ holds at 2.25%, as expected
- Bank confident inflation returns to 2% midpoint within next year
- Updated rate track signals shallow tightening cycle
- Policy track less hawkish than market pricing
- NZD/USD pressured but bullish trend holds
Summary
The RBNZ changed little on policy but delivered a clear repricing signal. While confident inflation will return to target, the Bank’s projected tightening cycle remains shallow and slower than markets had priced, a disconnect that triggered fresh Kiwi weakness. However, the risk remains that rates may ultimately have to move earlier and further than currently envisaged.
No surprises, RBNZ stands pat
The Reserve Bank of New Zealand left its cash rate unchanged at 2.25%, a decision that was fully expected by markets. The Committee outlined several reasons supporting a steady stance, pointing to significant spare capacity, an output gap estimated at -1.5%, elevated unemployment, and subdued wage pressures.
The output gap measures the difference between actual activity and the economy’s estimated capacity, with a negative reading indicating the economy is running below potential.
While inflation remains slightly above its inflation target band, policymakers expressed confidence that it will fall to the 2% midpoint over the next 12 months, citing spare capacity in the economy, modest wage growth, and trends in core inflation measures.
The Bank acknowledged that economic conditions are no longer deteriorating, with activity stabilising and gradually broadening, though household spending remains restrained amid persistent weakness in the housing market.
The minutes also revealed differing views within the Committee, with one member leaning towards earlier withdrawal of stimulus should the recovery strengthen, while another cautioned against reacting too quickly to changes in pricing behaviour from businesses.
Shallow tightening path seen
Source: RBNZ
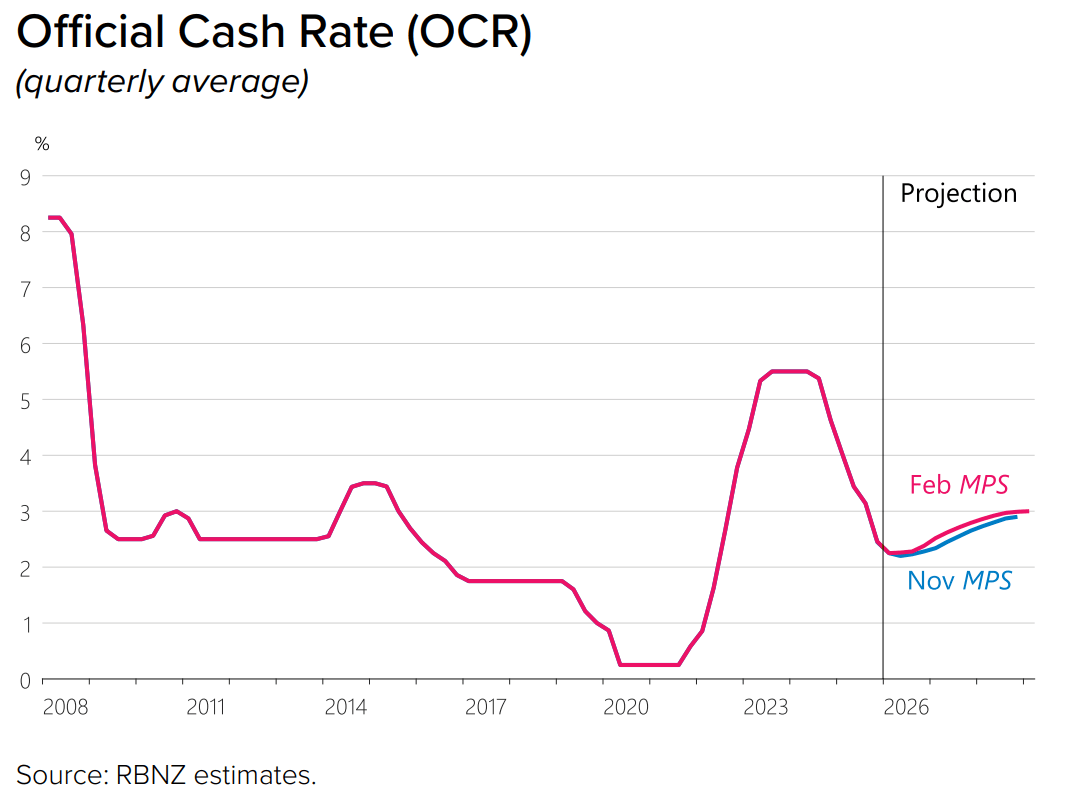
The RBNZ’s updated rate track was always likely to be the main focus of today’s meeting, offering insight into how policymakers see the cash rate evolving over the coming years. As expected, it removed any remaining residual easing bias, effectively signalling that the next move is more likely to be up than down.
Consistent with our prior expectations, it shifted forward the timing of its projected first hike to Q4 2026, a quarter earlier than indicated in November. A hike by Q1 2027 is now anticipated.
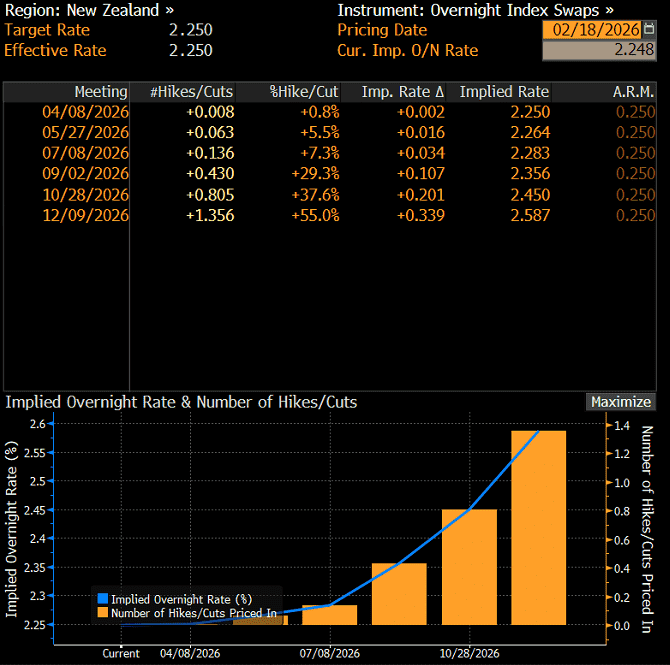
Importantly, the profile was less hawkish than market pricing. Prior to the decision, markets had around 1.5 hikes priced by the end of this year, a disconnect that helps explain the sharp decline seen in the Kiwi following the release.
The Bank continues to signal a very shallow tightening cycle, with the cash rate projected to reach just 3% by 2028, implying that policymakers see neutral settings near that level.
That assumption warrants caution. The RBNZ has a history of misjudging the pace and magnitude of policy shifts, having previously underestimated how far and fast rates needed to be reduced during the prior easing cycle. My view remains that risks are skewed towards earlier and greater tightening than currently projected, reflecting the incoming boost to household and business cashflows as fixed-rate loans reset into a materially lower interest rate environment.
Rate expectations reset
Source: Bloomberg
In response to the updated forecasts and statement, implied pricing for hikes by year end was trimmed by traders, with only one hike now favoured, down from the two before the decision. The first plausible meeting where hike risk is being assigned is July, currently priced at 31%. Probably too soon, but never say never once the full impact of the prior easing cycle begins to feed through.
NZD/USD Outlook
Source: TradingView
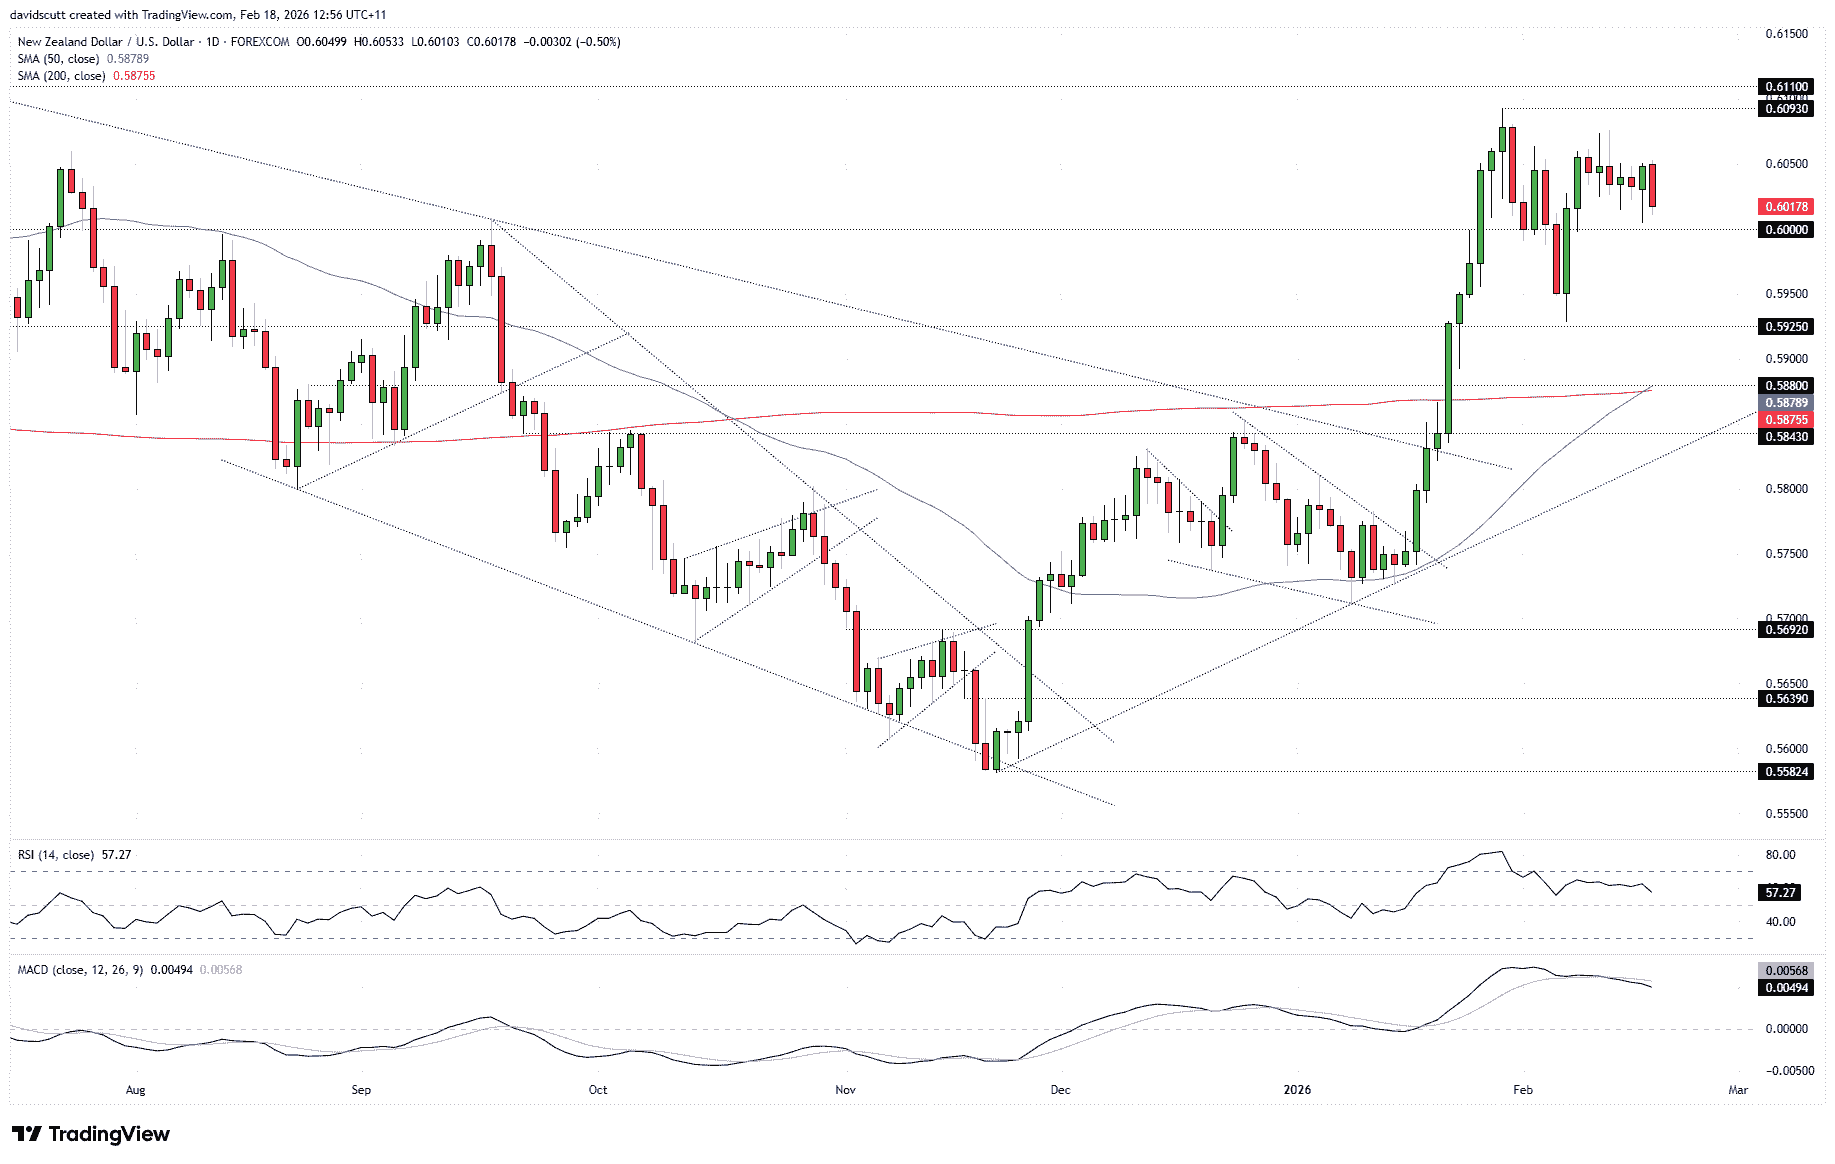
NZD/USD fell as much as 0.6% following the policy decision, moving back towards the .6000 level where it has attracted plenty of bids over the past week. Outside of another sustained deterioration in broader risk appetite, it would be surprising to see the Kiwi break .6000 purely on the RBNZ, unless Anna Breman goes full-bore dove at her first press conference as governor in little over an hour’s time.
The broader backdrop for NZD/USD remains largely unchanged, with the pair continuing to consolidate after the run to multi-month highs in January. RSI (14) and MACD point to waning upside momentum, presenting a more neutral signal on directional risks. However, with price sitting above the rising 50 and 200-day moving averages and the broader uptrend still intact, an upside bias remains preferred. That view would need reassessment should price slide beneath the lows set earlier this month.
.6000 and .5925 are the immediate downside levels on the watchlist. The January high at .6093 remains key to potentially unlocking further upside, with a sustained break signalling a possible resumption of the broader bullish move.


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.