




OIL MARKET WEEK AHEAD PreOPEC Whispers Intensify
Behind-the-scenes discussions on the next production level decision are intensifying...
Share this:

As the OPEC’s December meeting in Vienna draws closer, the behind-the-scenes discussions on the next production level decision are intensifying as is the flow of sideways comments from the cartel’s oil ministers. In the past week, Saudi Arabia, which has ended up with lower output levels not only because of planned cuts but also because of the attack on the Abqaiq refinery, hinted that it is keen to see other members stick to their output quotas, wagging an accusatory finger at Iran and Nigeria.
During the week ahead, look out for a response from Russia which is less than keen to rein in its output. The CEO of Russia’s Rosneft, Igor Sechin, made it openly clear that he is opposed to cutting production and recently indicated that Saudi Arabia should mind its own business rather than put pressure on Russia to reduce output.
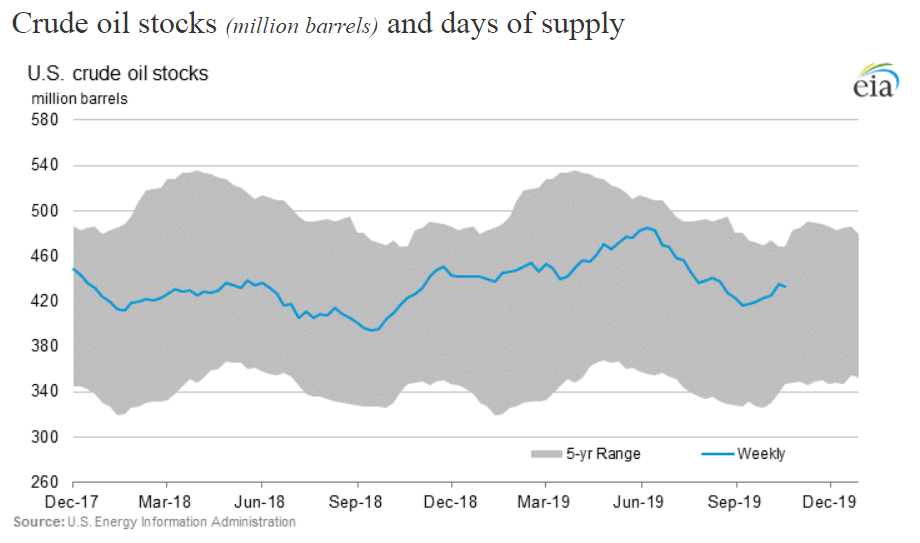
Irrespective of the less-than-amicable comments, oil producers are facing stagnating demand and a build-up of reserves which may force OPEC into not only extending existing output restrictions but also adding new ones to meet slowing demand.
API WEEKLY CRUDE STOCKS
US crude oil production is now running at an all-time high of 12.4M b/d, which is partially catering to slightly higher domestic demand but is also being increasingly exported abroad. According to the EIA the gradual increase in US exports will mean that the US will become a net exporter of petroleum in the last quarter of this year.
The API stocks on Tuesday and EIA weekly petroleum reserves on Wednesday will show if the domestic US stock levels are continuing to build as they did in September and October or if increased exports and domestic demand are managing to balance out the US oil market.
Expectations for US GDP data on Wednesday are for a slight slowdown from the 2% growth in the second quarter, which tallies with other economic indicators over the last few months. A slowdown in domestic growth will not be supportive of the oil market and may require a re-think on domestic production levels.
| When? | What? | Why is it important? |
| Sunday 27 Oct | China Sept industrial profit | Indicator of Chinese industrial growth |
| Tuesday 29 Oct | BP Q3 results | How lower prices affected quarterly earnings |
| Tuesday 29 Oct | Conoco Phillips Q3 earnings | How lower prices affected quarterly earnings |
| Tuesday 29 Oct 15.00 | US pending home sales | Indicator of demand from the construction industry |
| Tuesday 29 Oct 20.30 | API US weekly crude oil stocks | Previously increase of 4.45m bbl |
| Wednesday 30 Oct 13.30 | US GDP | Previously at 2% |
| Wednesday 30 Oct 16.30 | EIA crude oil inventories | Previously down 1.699m |
| Thursday 31 Oct 02.00 | Chinese Manufacturing PMI | Indicator of Chinese manufacturing growth, previously at 49.8 |
| Friday 1 Nov 02.45 | China Caixin Manufacturing PMI | Similar to the previous indicator but focused on smaller and medium-sized enterprises |
| Friday 1 Nov 14.45 | US Manufacturing PMI | Indicator of the state of US manufacturing. Previously at 51.5 |
| Friday 1 Nov 20.30 | CFTC Oil Net Positions |
BP Earnings Results on Tap
BP’s results on Tuesday will provide more information on how badly the oil’s dips below $60 in the last quarter affected the company’s upstream operations. Hurricane Barry slowed down production in the Gulf of Mexico during Q3 as did maintenance activities and seasonal turnaround. Lower prices would have worked in favour of BP’s downstream business. But weaker demand for petroleum products caused by an overall weakening of the global economy is also likely to have affected BP’s refining operations.




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq 100 Forecast: NDX falls ahead of Nvidia’s earnings & Anthropic’s debut this week
U.S. stocks are heading for a weaker open amid a challenging macro backdrop and with AI-linked stocks once again under pressure ahead of Nvidia's results later this week. Attention is also turning to Anthropic's highly anticipated IPO.


Crude Oil Weekly Outlook: Geopolitics vs Oversupply Risks
Crude Oil Weekly Outlook: The IEA has flagged the risk of an oil supply surplus since the Iran war began. Yet WTI and Brent have held onto bullish rebounds from key support near 84 and 89, respectively, as geopolitical risks persist.

S&P 500 forecast: SPX struggles for direction ahead of PPI data
U.S. stocks are struggling for direction on Friday as investors continue to weigh up the fallout from Nvidia’s leadership change, rising Treasury yields and the upcoming U.S. producer price inflation data.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.