



Saudi Oil Attacks What to expect from stocks and oil prices
The Saudi news also triggered a safe-haven response in the wider markets with gold rising and most stock indices and US index futures falling.
Share this:

After gapping about 20% higher as markets responded to the weekend attack on Saudi Arabia’s oil infrastructure — which reduced the nation’s oil output by more than half — oil prices have given back a significant chunk of those gains, although they still remain sharply higher on the day. The Saudi news also triggered a safe-haven response in the wider markets with gold rising and most stock indices and US index futures falling. Sentiment was hurt further by fresh signs that the ongoing US-China trade war was hurting activity at the world’s second largest economy. Industrial production in China rose by just 4.4% year-over-year in August compared with 4.8% in July and 5.2% expected. This was also the worst reading since February 2002. On top of this, retail sales growth slowed down again, this time to 7.5% compared to 7.6% in July and below expectations of 7.9%.
FTSE outperforms on oil, pound
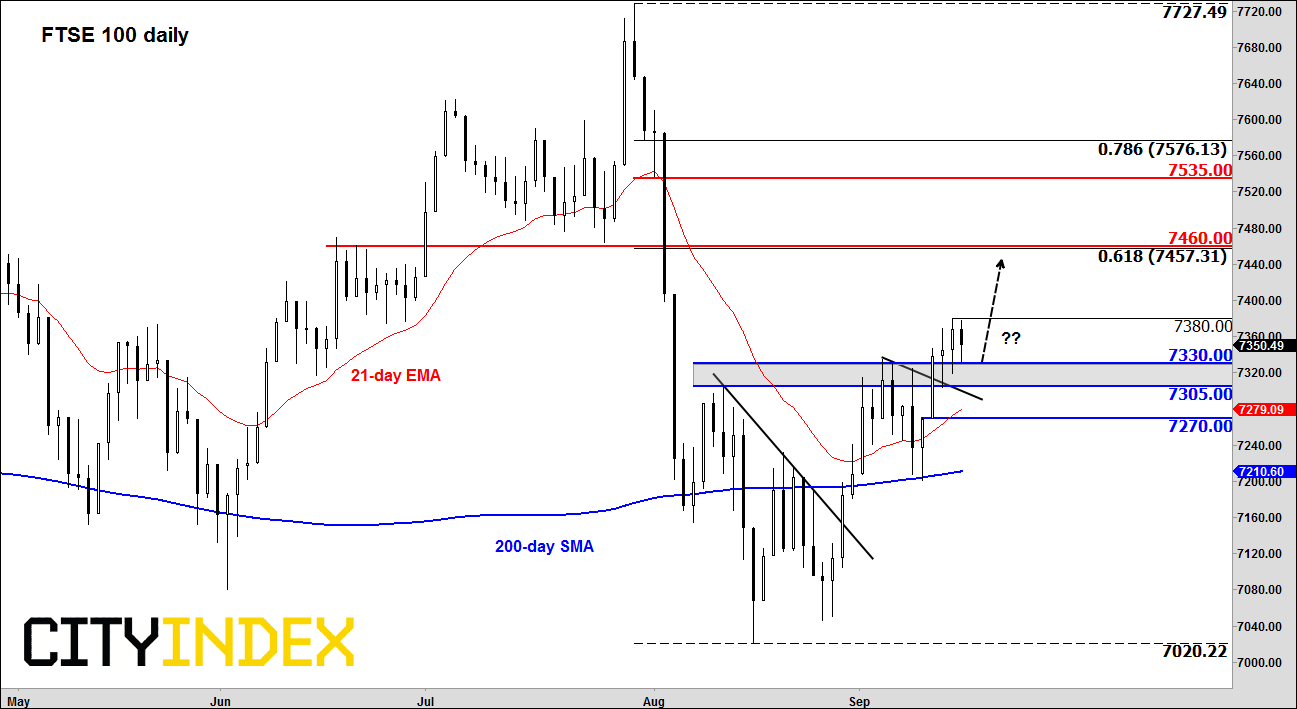
Despite the latest slowdown signs in China and falls for global stocks in response to the Saudi news, the UK’s FTSE 100 managed to reclaim most of its lost ground before almost turning flat this morning. Other major indices were still lower at the time of writing, however. The FTSE’s relatively strong performance is hardly a surprise given that BP and Shell (both of which rose on the oil news) are among the heaviest weighted stocks in the index. However, stocks of insurance companies and International Consolidated Airlines Group fell, and that prevented the FTSE from rising more meaningfully. Also helping the FTSE was the fact that sterling eased off its monthly highs hit on Friday as the GBP/USD hit a key resistance area circa 1.2480 as investors awaited fresh Brexit-related headlines.
Oil attack implications
The oil attack means Saudi’s crude production capacity could be impacted for weeks and this could keep Brent prices and stocks of energy companies supported for a while. However, OPEC’s other members will be more than happy to step up production to make up for some of the short falls in Saudi’s regular crude production. US President Donald Trump has meanwhile already authorised the release of US reserves and this has helped to lower prices following the big spike overnight. However, the longer-term impact is unclear at the moment and depends on how severe or otherwise the damage is going to be. Also, with the US suggesting that Iran could have been behind the attack, there is a small risk that this could turn to something much bigger in the region, possibly involving US military action. However, if this turns out to be a one-off attack and everyone is convinced that it was indeed the Houthi rebels rather than the Iranian government, then in that case the situation could calm down pretty quickly.
Fed in focus
Meanwhile, with lots of central bank meetings to look forward to this week, the focus for equity investors could quickly turn to interest rates from oil prices. Clearly, most of the attention will be on the Federal Reserve on Wednesday. A 25-basis point rate cut is widely expected, and it would be a major shock if the Fed doesn’t deliver. But some, including Donald Trump, want more than just 25 basis points. In fact, the US President has called for “boneheads” Fed to cut rates to zero or lower in a tweet last week. Understandably, with US data not deteriorating as badly as, say, Germany, the Fed is reluctant to cut aggressively and rightly so. The risk therefore is that the Fed refuses to provide a dovish outlook for interest rates. In this potential scenario, a rate cut might only provide mild support for stocks. With most other major central banks already being or turning dovish, the Fed will also need to be super dovish for stocks to rally meaningfully.
Source: eSignal and City Index.
After gapping about 20% higher as markets responded to the weekend attack on Saudi Arabia’s oil infrastructure — which reduced the nation’s oil output by more than half — oil prices have given back a significant chunk of those gains, although they still remain sharply higher on the day. The Saudi news also triggered a safe-haven response in the wider markets with gold rising and most stock indices and US index futures falling. Sentiment was hurt further by fresh signs that the ongoing US-China trade war was hurting activity at the world’s second largest economy. Industrial production in China rose by just 4.4% year-over-year in August compared with 4.8% in July and 5.2% expected. This was also the worst reading since February 2002. On top of this, retail sales growth slowed down again, this time to 7.5% compared to 7.6% in July and below expectations of 7.9%.
FTSE outperforms on oil, pound
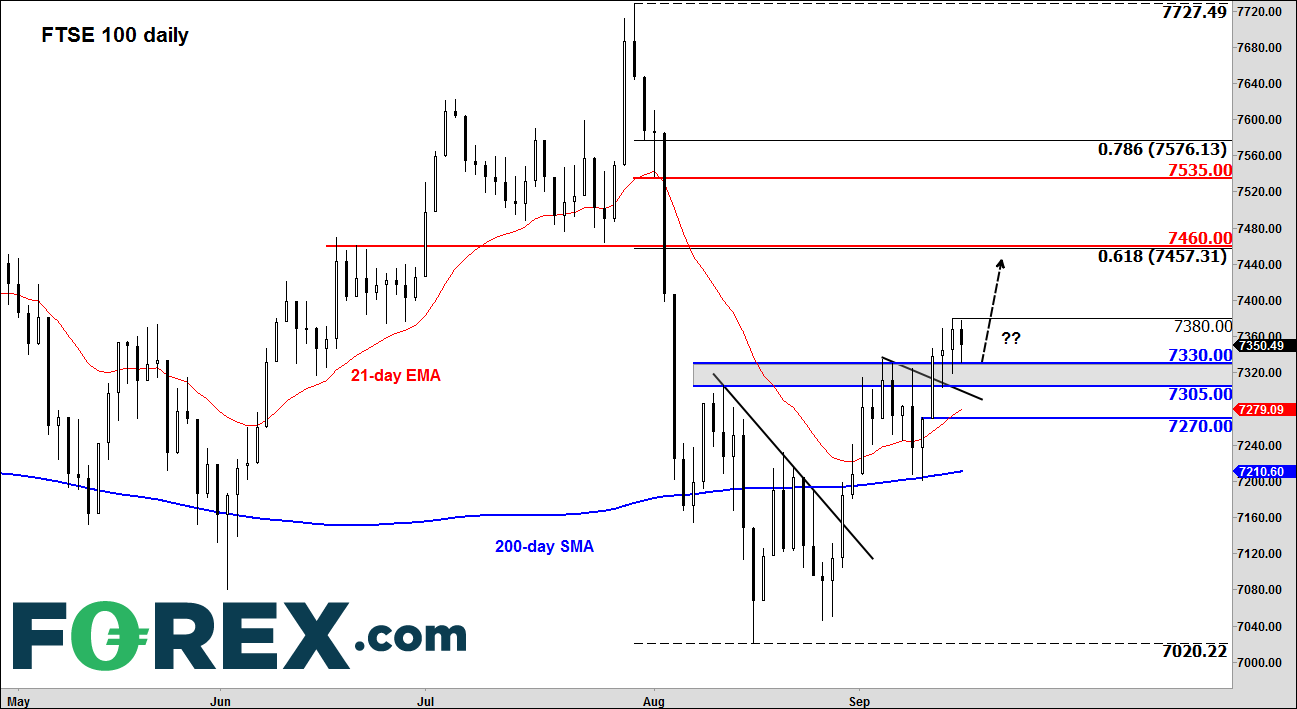
Despite the latest slowdown signs in China and falls for global stocks in response to the Saudi news, the UK’s FTSE 100 managed to reclaim most of its lost ground before almost turning flat this morning. Other major indices were still lower at the time of writing, however. The FTSE’s relatively strong performance is hardly a surprise given that BP and Shell (both of which rose on the oil news) are among the heaviest weighted stocks in the index. However, stocks of insurance companies and International Consolidated Airlines Group fell, and that prevented the FTSE from rising more meaningfully. Also helping the FTSE was the fact that sterling eased off its monthly highs hit on Friday as the GBP/USD hit a key resistance area circa 1.2480 as investors awaited fresh Brexit-related headlines.
Oil attack implications
The oil attack means Saudi’s crude production capacity could be impacted for weeks and this could keep Brent prices and stocks of energy companies supported for a while. However, OPEC’s other members will be more than happy to step up production to make up for some of the short falls in Saudi’s regular crude production. US President Donald Trump has meanwhile already authorised the release of US reserves and this has helped to lower prices following the big spike overnight. However, the longer-term impact is unclear at the moment and depends on how severe or otherwise the damage is going to be. Also, with the US suggesting that Iran could have been behind the attack, there is a small risk that this could turn to something much bigger in the region, possibly involving US military action. However, if this turns out to be a one-off attack and everyone is convinced that it was indeed the Houthi rebels rather than the Iranian government, then in that case the situation could calm down pretty quickly.
Fed in focus
Meanwhile, with lots of central bank meetings to look forward to this week, the focus for equity investors could quickly turn to interest rates from oil prices. Clearly, most of the attention will be on the Federal Reserve on Wednesday. A 25-basis point rate cut is widely expected, and it would be a major shock if the Fed doesn’t deliver. But some, including Donald Trump, want more than just 25 basis points. In fact, the US President has called for “boneheads” Fed to cut rates to zero or lower in a tweet last week. Understandably, with US data not deteriorating as badly as, say, Germany, the Fed is reluctant to cut aggressively and rightly so. The risk therefore is that the Fed refuses to provide a dovish outlook for interest rates. In this potential scenario, a rate cut might only provide mild support for stocks. With most other major central banks already being or turning dovish, the Fed will also need to be super dovish for stocks to rally meaningfully.
Source: eSignal and FOREX.com. Please note this product may not be available to trade in all regions.




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq 100 Forecast: NDX falls ahead of Nvidia’s earnings & Anthropic’s debut this week
U.S. stocks are heading for a weaker open amid a challenging macro backdrop and with AI-linked stocks once again under pressure ahead of Nvidia's results later this week. Attention is also turning to Anthropic's highly anticipated IPO.


Crude Oil Weekly Outlook: Geopolitics vs Oversupply Risks
Crude Oil Weekly Outlook: The IEA has flagged the risk of an oil supply surplus since the Iran war began. Yet WTI and Brent have held onto bullish rebounds from key support near 84 and 89, respectively, as geopolitical risks persist.

S&P 500 forecast: SPX struggles for direction ahead of PPI data
U.S. stocks are struggling for direction on Friday as investors continue to weigh up the fallout from Nvidia’s leadership change, rising Treasury yields and the upcoming U.S. producer price inflation data.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.