



Seasonals Suggest A Lower Vix For September
After a bumpy ride throughout August, perhaps volatility can subside and present us with a more directional move once traders return to their desks.
Share this:

It's been a volatile month for markets, with the fallout from the ongoing trade war, attacks on the Fed, Brexit and Italian elections (to name a few rivers). This may feel counter to how markets ‘should be’ during the lazy summer periods yet, according to the seasonality for VIX, it appears to be on track for a typical summer month.
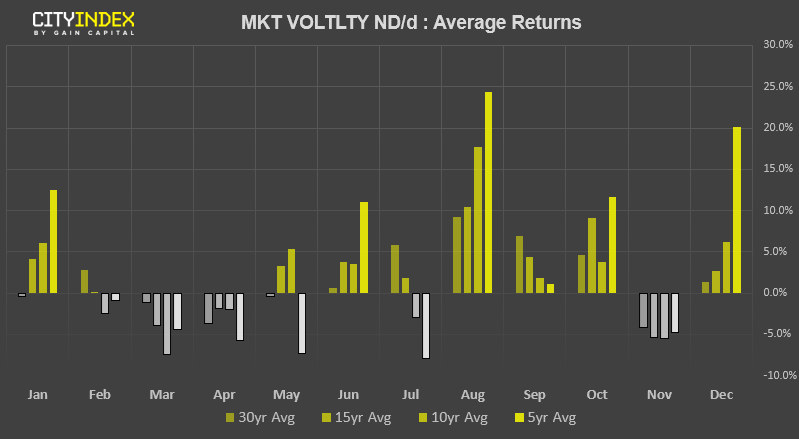
Taking the past 30 years of data, we can see that the VIX is typically higher during the month of August. Moreover, the average has increased if we measure over the past 5, 10 and 15 years. Whilst each August will have its own tale to tell, it can partly rationalised to a lower liquidity environment which can leave markets (such as the S&P500) more vulnerable to large moves from perhaps smaller headlines.
Looking forward, we can see that the level of VIX typically lowers during September as traders return to their desks. In turn, this could suggest we’re in for a period of dull, sideways trading or (hopefully) lower volatility at the beginning of new trends amid a more liquid market. Of course, time will tell, but it’ something to consider moving forward (and whilst the S&P500 remains rangebound).
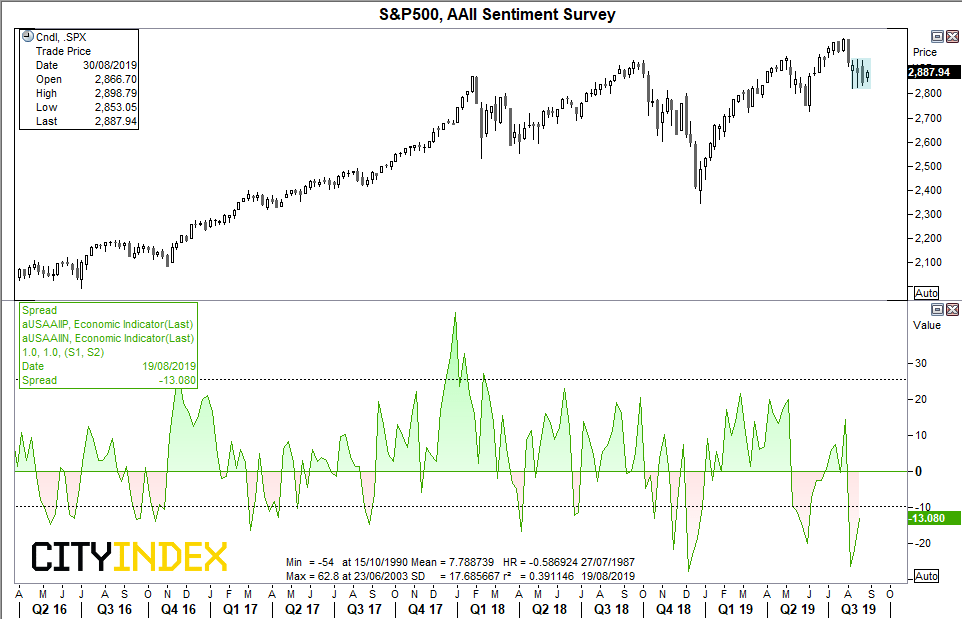
It’s possible we may not see the S&P500 break out of range until traders (and therefore volumes) return, so traders could look to buy at the lows or short at the highs. However, we’ve noticed that the AAII Sentiment Survey (American Association of Individual Investors) has signalled a bearish extreme earlier this month. As with most sentiment indicators, timing can be off, but looking back through history shows that extremely low readings can occur some time around the actual price low, give or take a few weeks. The indicator is the spread between bullish and bearish investors, and the dotted lines represent +/1 1 standard deviation. And, given we’ve seen the yield curve invert which has historically been bullish for the S&P500, perhaps traders will want to enter long when they return from their break. As always, let price action be your guide.
Related analysis:
Forward Returns Following A US10-2 Year Inversion
It's been a volatile month for markets, with the fallout from the ongoing trade war, attacks on the Fed, Brexit and Italian elections (to name a few rivers). This may feel counter to how markets ‘should be’ during the lazy summer periods yet, according to the seasonality for VIX, it appears to be on track for a typical summer month.
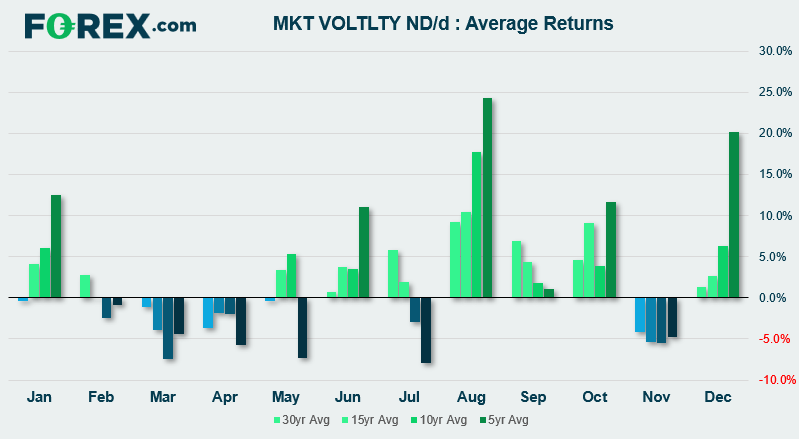
Taking the past 30 years of data, we can see that the VIX is typically higher during the month of August. Moreover, the average has increased if we measure over the past 5, 10 and 15 years. Whilst each August will have its own tale to tell, it can partly rationalised to a lower liquidity environment which can leave markets (such as the S&P500) more vulnerable to large moves from perhaps smaller headlines.
Looking forward, we can see that the level of VIX typically lowers during September as traders return to their desks. In turn, this could suggest we’re in for a period of dull, sideways trading or (hopefully) lower volatility at the beginning of new trends amid a more liquid market. Of course, time will tell, but it’ something to consider moving forward (and whilst the S&P500 remains rangebound).
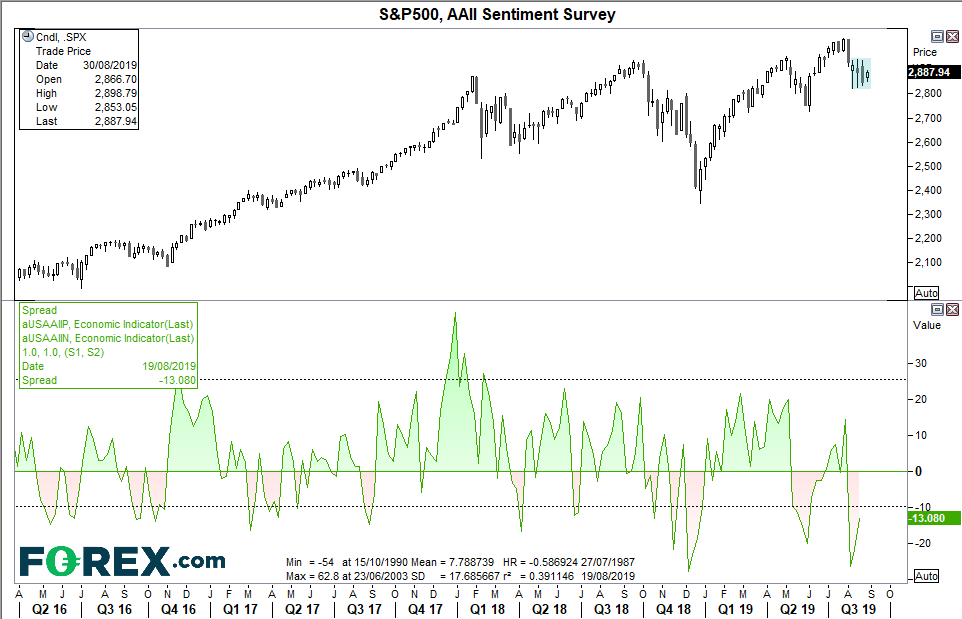
It’s possible we may not see the S&P500 break out of range until traders (and therefore volumes) return, so traders could look to buy at the lows or short at the highs. However, we’ve noticed that the AAII Sentiment Survey (American Association of Individual Investors) has signalled a bearish extreme earlier this month. As with most sentiment indicators, timing can be off, but looking back through history shows that extremely low readings can occur some time around the actual price low, give or take a few weeks. The indicator is the spread between bullish and bearish investors, and the dotted lines represent +/1 1 standard deviation. And, given we’ve seen the yield curve invert which has historically been bullish for the S&P500, perhaps traders will want to enter long when they return from their break. As always, let price action be your guide.
Related analysis:
Forward Returns Following A US10-2 Year Inversion
Two Scenarios We're Watching On The Dax
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nikkei swings harder than Nasdaq as AI fears deepen
Nikkei 225 volatility is running well ahead of Nasdaq 100, with the index construction and Japan's heavy exposure to AI manufacturing potentially explaining the difference.

S&P 500, Nasdaq 100 Claw Back But NVDA Cloud Looms Overhead
Last week was green for both the Nasdaq and S&P 500 but given the sell-off that led into that bounce there’s still a very real question as to whether bears still have a statement to make. And the NVDA situation presents a very real threat.


Nasdaq 100 forecast: Nvidia troubles put AI recovery into question
The recovery for major indices this week has helped repair much of the technical damage inflicted by last week’s sell-off, but the latest developments with Nvidia suggest investors are not quite ready to put the underlying risks behind them. The Nasdaq 100 led other US index futures lower overnight, with falls of around 0.8%.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.