



US Dollar Index Tags a Fresh 2018 High on Mixed Economic Data
Generally speaking, US traders have been focused on the other side of the Atlantic this week, with particular attention on the continued Brexit drama and the mostly as-expected ECB meeting. With those situations (at least temporarily) behind us, the market’s eye has shifted back stateside in advance of next week’s highly-anticipated Federal Reserve meeting.
Share this:

Generally speaking, US traders have been focused on the other side of the Atlantic this week, with particular attention on the continued Brexit drama and the mostly as-expected ECB meeting. With those situations (at least temporarily) behind us, the market’s eye has shifted back stateside in advance of next week’s highly-anticipated Federal Reserve meeting.
A series of economic reports this morning may prompt Fed policymakers to raise their eyebrows, though it’s a bit late in the game to deviate from next week’s (assumed) interest rate increase. November’s Retail Sales report printed at +0.2% m/m, a tick above the market’s expected +0.1% reading. Bolstering the strength of the report, sales in the report’s “control group” (a cohort seen as more representative of underlying consumer demand) rose +0.9% m/m, more than twice the median economists’ estimate. In a separate report, Industrial Production rose +0.6% m/m vs. +0.3% eyed, though the previous month’s report was revised lower.
While the retail sales report and industrial production reports were both solid, the forward-looking Markit PMI readings for December were more concerning. Both the manufacturing and services PMI figures came in lower than expected, as well as lower than last months’ readings. Overall, the composite Markit PMI reading printed at 53.6, the lowest level of economic activity since May 2017. In the words IHS Markit’s Chief economist Chris Williamson, “The flash PMIs bring signs of the US economy ending 2018 on a softer note. With business activity expanding at the slowest rate for one and a half years, the surveys indicate that the pace of economic growth has faded to 2.0% in December albeit closer to 2.5% for the fourth quarter as a whole…amid uncertainty about the economic outlook, linked in part to growing geopolitical concerns and trade wars.”
Technical View: US Dollar Index
Today’s hour-by-hour price action in the greenback reflects traders’ evolving views on the US economy. After the better-than-expected Retail Sales and Industrial Production reports, the US Dollar Index peeked out to a fresh 2018 high above 97.70. However, the progress was short-lived, with the disappointing Markit PMI readings taking rates back down to the mid-97.00s, where they remain as of writing.
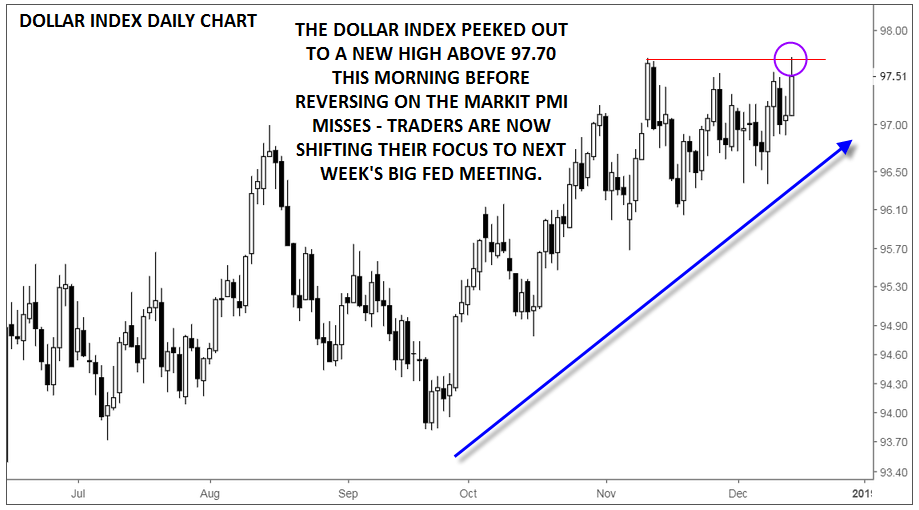
Source: TradingView, FOREX.com
Moving forward, the dollar’s prospects will hinge on next week’s Fed meeting. At this point, the market has discounted a “dovish hike,” meaning that the central bank will raise interest rates but policymakers will ratchet down their expectations for future increases in 2019 (from September’s three projected hikes).
If Powell and Company vote unanimously next week and strike an optimistic note on 2019 (i.e. by projecting another two interest rate increases), the greenback could surge out of its recent consolidation to trade at 18-month highs above 98.00. On the other hand, a very cautious statement, any dissenting voters, or a revision down to just one projected rate hike in the median Fed policymakers outlook for next year could take the dollar index back toward 96.00 by Christmas.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq 100 Forecast: NDX falls ahead of Nvidia’s earnings & Anthropic’s debut this week
U.S. stocks are heading for a weaker open amid a challenging macro backdrop and with AI-linked stocks once again under pressure ahead of Nvidia's results later this week. Attention is also turning to Anthropic's highly anticipated IPO.

S&P 500 forecast: SPX struggles for direction ahead of PPI data
U.S. stocks are struggling for direction on Friday as investors continue to weigh up the fallout from Nvidia’s leadership change, rising Treasury yields and the upcoming U.S. producer price inflation data.
AUD/USD Outlook: Historic yield squeeze leaves Aussie bears in control
Australian bond yields have fallen below their US equivalents as the Fed's hawkish repricing gathers momentum. With the Aussie weakening broadly, technical signals suggest sellers remain in control.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.