



US open: Risk-off returns with inflation back in focus
The relief rally was short lived and stocks are once again heading lower as treasury yields rise and recession fears build.
Share this:

US futures
Dow futures -1% at 29222
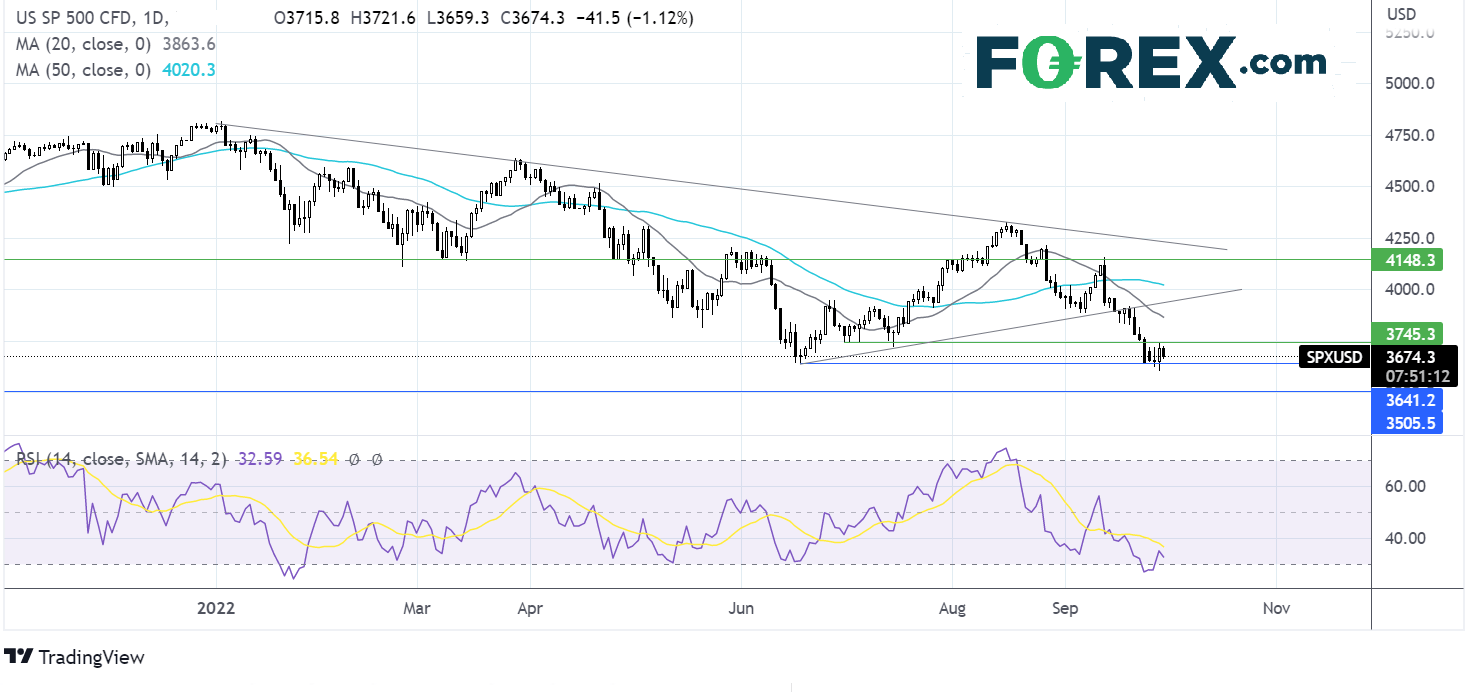
S&P futures -1.35% at 3650
Nasdaq futures -1.7% at 11300
In Europe
FTSE -1.1% at 6910
Dax -1.5% at 12003
Jobless claims fall by more than forecast
US stocks are heading southwards, back towards the year-to-date lows after gains in the previous session. The BoE rode to the rescue of the markets for one day, and the overall impact has been limited.
Higher US treasury yields, inflation and rising recession fears are back in the driving seat. Federal Reserve officials have been clear that interest rates need to keep rising and will stay higher for longer than previously thought, raising the risk of recession.
Stronger than forecast data also supports a more hawkish Federal Reserve. The US GDP Q2 was confirmed at -0.6% QoQ annualized. However, Core PCE for the quarter was revised higher to 4.7%. US jobless claims fell by more than forecast to 193k, down from 213k, highlighting the tightness in the jobs market.
Adding to the souring market mood, Russia has announced that it will formally annex four more areas of Ukraine after referendums in the region. This move could potentially escalate the war as Putin threatens those who do not recognize the new borders.
Corporate news:
Apple falls pre-market after Bank of America downgraded the stock to neutral from buy, citing the expected fall in discretionary spending
Travel stocks are also under pressure, with the likes of American Airline, Delta Airlines, and Carnival falling as journeys are canceled due to Hurricane Ian.
Where next for the S&P500?
FX markets – USD holds steady & GBP as well
The USD is holding steady after steep losses yesterday. The greenback fell as US bond yields dropped following the BoE’s intervention, calming the financial markets. However, bond yields are climbing again today, although the USD is not following suit.
EUR/USD is falling as investors digest German soaring inflation and deteriorating economic sentiment. German inflation jumped to 10.9% YoY in September, well up from 8.9% in August and significantly above the 10% forecast. The data piles pressure on the ECB to hike rates aggressively, yet with economic sentiment plunging, recession fears are rising, keeping the euro under pressure.
GBPUSD is holding steady as investors continue digesting the latest developments in the post-mini-budget saga. Whilst the pound has recovered from its record low, and is finding some support from the BoE riding to the rescue, the action by the central bank, has calmed a jittery market but doesn’t address the underlying cause of the problem. Instead, it raises more questions over incoherent policy, which leaves the pound looking vulnerable. As far as the consumer is concerned the outlook is bleak, with aggressive rate hikes on the cards, which are set to push interest rates and mortgage repayments higher, disposable income is set to fall significantly. This feels like a ticking time bomb with retailers bracing for a hard hit and house prices expected to collapse quickly.
GBP/USD -0.15% at 1.0873
EUR/USD -0.08% at 0.9727
Oil rises as attention turns to OPEC+
Oil prices are rising, extending strong gains from yesterday on reports that OPEC+ is considering a production cut in its next meeting in the coming week.
OPEC+ cut output by 100kbpd in the September meeting, a reversal of a production increase in the previous meeting. However, reports are circulating that a larger output cut could be on the cards, possibly by as much as 1 million barrels per day.
Hurricane Ian is also providing support as some oil production remains shut down in the Gulf of Mexico.
Meanwhile, gains are likely to remain capped by recession fears hurting the growth outlook.
WTI crude trades +0.27% at $82.70
Brent trades +0.26% at $88.50
Looking ahead
18:00 ECB Lane
US futures
Dow futures -1% at 29222
S&P futures -1.35% at 3650
Nasdaq futures -1.7% at 11300
In Europe
FTSE -1.1% at 6910
Dax -1.5% at 12003
Learn more about trading indices
Jobless claims fall by more than forecast
US stocks are heading southwards, back towards the year-to-date lows after gains in the previous session. The BoE rode to the rescue of the markets for one day, and the overall impact has been limited.
Higher US treasury yields, inflation and rising recession fears are back in the driving seat. Federal Reserve officials have been clear that interest rates need to keep rising and will stay higher for longer than previously thought, raising the risk of recession.
Stronger than forecast data also supports a more hawkish Federal Reserve. The US GDP Q2 was confirmed at -0.6% QoQ annualized. However, Core PCE for the quarter was revised higher to 4.7%. US jobless claims fell by more than forecast to 193k, down from 213k, highlighting the tightness in the jobs market.
Adding to the souring market mood, Russia has announced that it will formally annex four more areas of Ukraine after referendums in the region. This move could potentially escalate the war as Putin threatens those who do not recognize the new borders.
Corporate news:
Apple falls pre-market after Bank of America downgraded the stock to neutral from buy, citing the expected fall in discretionary spending
Travel stocks are also under pressure, with the likes of American Airline, Delta Airlines, and Carnival falling as journeys are canceled due to Hurricane Ian.
Where next for the S&P500?

FX markets – USD holds steady & GBP as well
The USD is holding steady after steep losses yesterday. The greenback fell as US bond yields dropped following the BoE’s intervention, calming the financial markets. However, bond yields are climbing again today, although the USD is not following suit.
EUR/USD is falling as investors digest German soaring inflation and deteriorating economic sentiment. German inflation jumped to 10.9% YoY in September, well up from 8.9% in August and significantly above the 10% forecast. The data piles pressure on the ECB to hike rates aggressively, yet with economic sentiment plunging, recession fears are rising, keeping the euro under pressure.
GBPUSD is holding steady as investors continue digesting the latest developments in the post-mini-budget saga. Whilst the pound has recovered from its record low, and is finding some support from the BoE riding to the rescue, the action by the central bank, has calmed a jittery market but doesn’t address the underlying cause of the problem. Instead, it raises more questions over incoherent policy, which leaves the pound looking vulnerable. As far as the consumer is concerned the outlook is bleak, with aggressive rate hikes on the cards, which are set to push interest rates and mortgage repayments higher, disposable income is set to fall significantly. This feels like a ticking time bomb with retailers bracing for a hard hit and house prices expected to collapse quickly.
GBP/USD -0.15% at 1.0873
EUR/USD -0.08% at 0.9727
Oil rises as attention turns to OPEC+
Oil prices are rising, extending strong gains from yesterday on reports that OPEC+ is considering a production cut in its next meeting in the coming week.
OPEC+ cut output by 100kbpd in the September meeting, a reversal of a production increase in the previous meeting. However, reports are circulating that a larger output cut could be on the cards, possibly by as much as 1 million barrels per day.
Hurricane Ian is also providing support as some oil production remains shut down in the Gulf of Mexico.
Meanwhile, gains are likely to remain capped by recession fears hurting the growth outlook.
WTI crude trades +0.27% at $82.70
Brent trades +0.26% at $88.50
Learn more about trading oil here.
Looking ahead
18:00 ECB Lane
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.