



US open: Stocks mixed Snap, Twitter disappoint
US stocks are mixed but are set for a weekly gain after broadly upbeat earnings in tech. However, Snap & Twitter disappointed.
Share this:

US futures
Dow futures +0.18% at 32100
S&P futures +0.1% at 3960
Nasdaq futures -0.35% at 12570
In Europe
FTSE +0.37% at 7250
Dax +0.8% at 13320
Euro Stoxx +0.4% at 3616
Stocks mixed but set for weekly gains
US stocks are pointing to a mixed start to trading on Friday, with the Nasdaq lower after Snap and Twitter earnings disappoint.
Earnings season is in full swing and so far have been broadly ahead of expectations. Rising costs, the stronger USD and slowing growth are areas that remain in focus.
Whilst Netflix and Tesla beat forecasts this week, boosting optimism, Snap is hurting the mood today after weaker earnings.
The markets have risen higher across the week, boosted by upbeat earnings and tempered expectations of aggressive Fed rate hikes.
The big test for the rally will be next week when faced with the Fed interest rates decision and more earnings from big tech, which have already indicated slower hiring and therefore slower spending.
Looking ahead US PMI data is expected to show that business activity growth slowed,. With the composite PMI is expected to slip to 51.7 in July from 52.3 in June.
In corporate news:
Snap was the first major tech firm to report Q2 earnings, and the picture was pretty grim, with the company falling 25% pre-market. The stock missed the top and bottom line and said that it plans to slow hiring substantially as it battles slowing revenue.
Twitter also disappointed on top and bottom lines citing weaker advertising revenue and uncertainty surrounding the Musk takeover.
Where next for the Nasdaq?
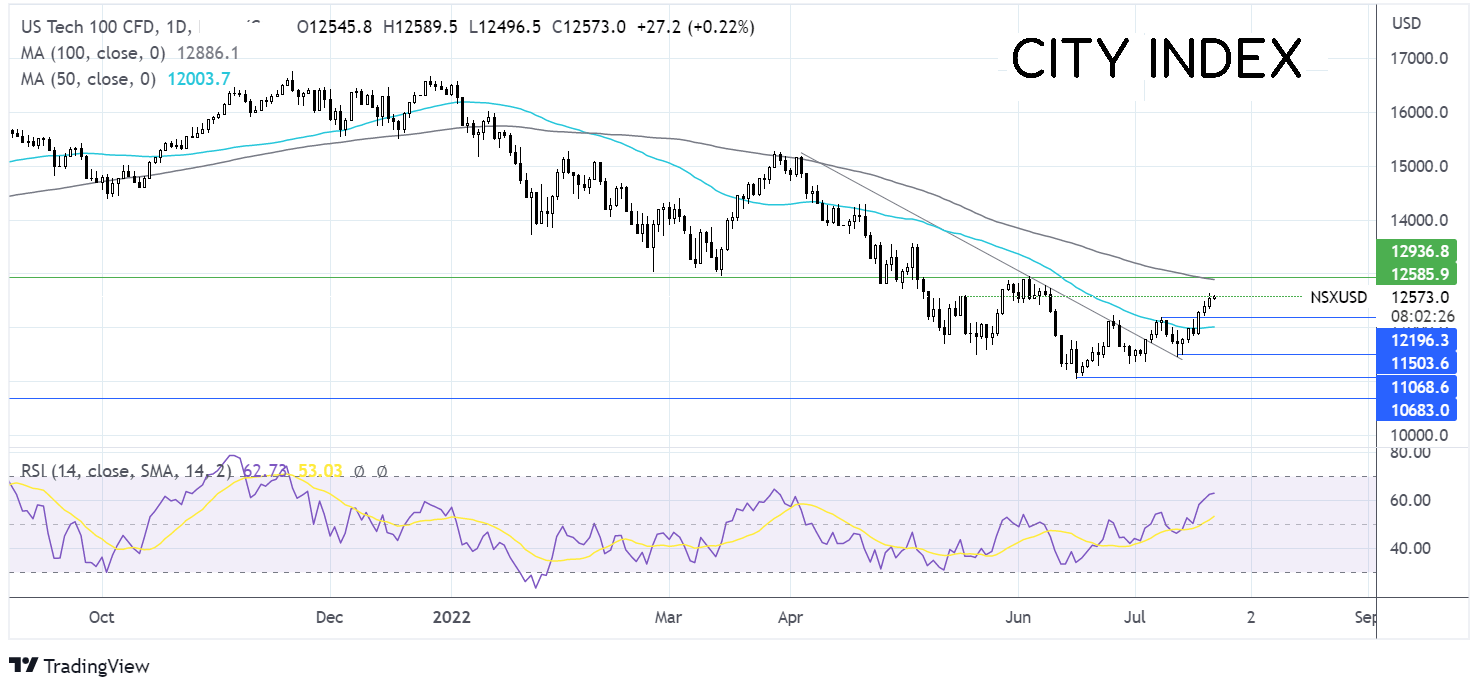
The Nasdaq is extending its rally from 2022 lows, retaking the 50 sna, which, combined with the bullish RSI, is keeping buyers optimistic about further gains. Buyers need to break above 12585, the 100 sma, and the June high. On the flip side, it would take a move below the 50 sma at 12040 to negate the near-term downtrend.

FX markets – USD rises, EUR falls.
USD is rising but is set for losses across the week as investors pare back expectations of a more aggressive rate hike. Higher than expected jobless claims yesterday raised recession concerns.
EURUSD is falling after PMI data showed that business activity slipped into contraction. The composite PMI fell to 49.4 in July, worse than the 51 forecasts and down from 52 in June. The data doesn’t bode well for GDP growth in the quarter.
GBP/USD is falling against a stronger USD and despite retail sales and business activity falling less than feared. Retail sales slipped -0.1% YoY, better than the -0.3% feared and up from -0.5%. The composite PMI data fell to 52.8, down from 53.7.
GBP/USD -0.06% at 1.1950
EUR/USD -0.5% at 1.0180
Oil falls by $5
Oil prices are falling, extending losses from the previous session and puts oil on track for losses of around 2.5% across the week, the third straight week of declines.
The weakening global demand outlook combined with the resumption of Libyan crude oil output is dragging on oil prices.
Macro data points to a global economic slowdown just as central banks are aggressively hiking rates. Slower growth hurts the demand outlook.
WTI crude trades -4.5% at $95.20
Brent trades -4% at $99.00
Looking ahead
N/A
US futures
Dow futures +0.18% at 32100
S&P futures +0.1% at 3960
Nasdaq futures -0.35% at 12570
In Europe
FTSE +0.37% at 7250
Dax +0.8% at 13320
Euro Stoxx +0.4% at 3616
Learn more about trading indices
Stocks mixed but set for weekly gains
US stocks are pointing to a mixed start to trading on Friday, with the Nasdaq lower after Snap and Twitter earnings disappoint.
Earnings season is in full swing and so far have been broadly ahead of expectations. Rising costs, the stronger USD and slowing growth are areas that remain in focus.
Whilst Netflix and Tesla beat forecasts this week, boosting optimism, Snap is hurting the mood today after weaker earnings.
The markets have risen higher across the week, boosted by upbeat earnings and tempered expectations of aggressive Fed rate hikes.
The big test for the rally will be next week when faced with the Fed interest rates decision and more earnings from big tech, which have already indicated slower hiring and therefore slower spending.
Looking ahead US PMI data is expected to show that business activity growth slowed,. With the composite PMI is expected to slip to 51.7 in July from 52.3 in June.
In corporate news:
Snap was the first major tech firm to report Q2 earnings, and the picture was pretty grim, with the company falling 25% pre-market. The stock missed the top and bottom line and said that it plans to slow hiring substantially as it battles slowing revenue.
Twitter also disappointed on top and bottom lines citing weaker advertising revenue and uncertainty surrounding the Musk takeover.
Where next for the Nasdaq?
The Nasdaq is extending its rally from 2022 lows, retaking the 50 sna, which, combined with the bullish RSI, is keeping buyers optimistic about further gains. Buyers need to break above 12585, the 100 sma, and the June high. On the flip side, it would take a move below the 50 sma at 12040 to negate the near-term downtrend.
FX markets – USD rises, EUR falls.
USD is rising but is set for losses across the week as investors pare back expectations of a more aggressive rate hike. Higher than expected jobless claims yesterday raised recession concerns.
EURUSD is falling after PMI data showed that business activity slipped into contraction. The composite PMI fell to 49.4 in July, worse than the 51 forecasts and down from 52 in June. The data doesn’t bode well for GDP growth in the quarter.
GBP/USD is falling against a stronger USD and despite retail sales and business activity falling less than feared. Retail sales slipped -0.1% YoY, better than the -0.3% feared and up from -0.5%. The composite PMI data fell to 52.8, down from 53.7.
GBP/USD -0.06% at 1.1950
EUR/USD -0.5% at 1.0180
Oil falls by $5
Oil prices are falling, extending losses from the previous session and puts oil on track for losses of around 2.5% across the week, the third straight week of declines.
The weakening global demand outlook combined with the resumption of Libyan crude oil output is dragging on oil prices.
Macro data points to a global economic slowdown just as central banks are aggressively hiking rates. Slower growth hurts the demand outlook.
WTI crude trades -4.5% at $95.20
Brent trades -4% at $99.00
Learn more about trading oil here.
Looking ahead
N/A
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.

Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.

Nasdaq 100 Forecast: NDX falls ahead of Nvidia’s earnings & Anthropic’s debut this week
U.S. stocks are heading for a weaker open amid a challenging macro backdrop and with AI-linked stocks once again under pressure ahead of Nvidia's results later this week. Attention is also turning to Anthropic's highly anticipated IPO.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.