




Vodafone returns to two bar growth
Rebounding service revenues justify giving Vodafone the benefit of the doubt, for now
Share this:

Rebounding service revenues and some turnarounds in Europe justify a medium-term benefit of the doubt
Organic rebound in context
Vodafone’s return to organic service revenue growth is the biggest relief in H1 results. The 0.7% year-on-year rise in the second quarter compares with 0.2% expected and more than erases Q1’s 0.2% decline. A sequential rebound leaves +0.3% on a half-year basis, pointing to a turnaround in Vodafone’s most important measure of revenues following two quarters of shrinking sales. Strengthening key sales on the back of improvements in some of Vodafone’s most troubled regions—South Africa, Spain and Italy—together with the best ever quarter for new UK customers have enabled a mild outlook upgrade.
Guidance signal
Adjusted Ebitda is now seen at €14.8bn-€15bn in the 2020 financial year compared with €13.8bn-€14.2bn before. Though the new forecast includes an €800m one-off boost from the purchase of some Liberty Global assets and the disposal of New Zealand operations, the midpoint of the new range is still €100m higher excluding those benefits. In effect, guidance is tightened with a slight shift to the higher end. It’s the most confident signal on guidance from Vodafone in the current financial year. CEO Nick Read duly confirmed that revenue growth is expected to continue through the remainder of the year in both Europe and Africa.
Tweak tempers relief
Investor relief has been evident in the stock’s rise of as much as 3.2%. As outlined in our preview, stabilisation of trouble spots like Spain, Italy and South Africa was necessary to safeguard underlying earnings goals, which were already lower than the year before. In turn, cash flow generation is critical for the dividend outlook after investors were forced to swallow a ‘rebase’ with an eye to lower debt and striking a better balance on spectrum costs and investments. Free cash flow guidance has been tweaked to “around” €5.4bn from “at least” €5.4bn. Although Vodafone shares pared their initial jump to a 2.3% gain by late morning, investors appear to have given Nick Read the benefit of the doubt on free cash flow goals. Greater clarity on earnings guidance helps.
Vodafone Idea still messy
The earnings guidance signal may even have encouraged the market to overlook persisting value destruction from Vodafone’s burdensome business in India. A €1.9bn loss was recorded for jointly owned Vodafone Idea with fierce competition exacerbated by a Supreme Court ruling. The UK group has struck some proceeds from the venture out from guidance whilst “financial relief” is sought from the government there. The update from India wasn’t as dire as feared by some investors, who suggested a write down of some €1bn was possible. Still, overall relief for the region remains some way off, providing ample room for critics who suspect Indian assets may eventually become worthless.
Germany, UK also stuck
Vodafone’s weak ‘coverage’ areas closer to home also remain evident, with a 1.4% H1 contraction in Europe, albeit that was still an improvement. Low margin wholesale businesses and stagnation in the mature markets of Germany and UK respectively look as intractable as ever. As such, some of Tuesday’s share fade is likely tied to medium-term prospects that may only have improved moderately, despite a relatively successful first half.
Stock price outlook
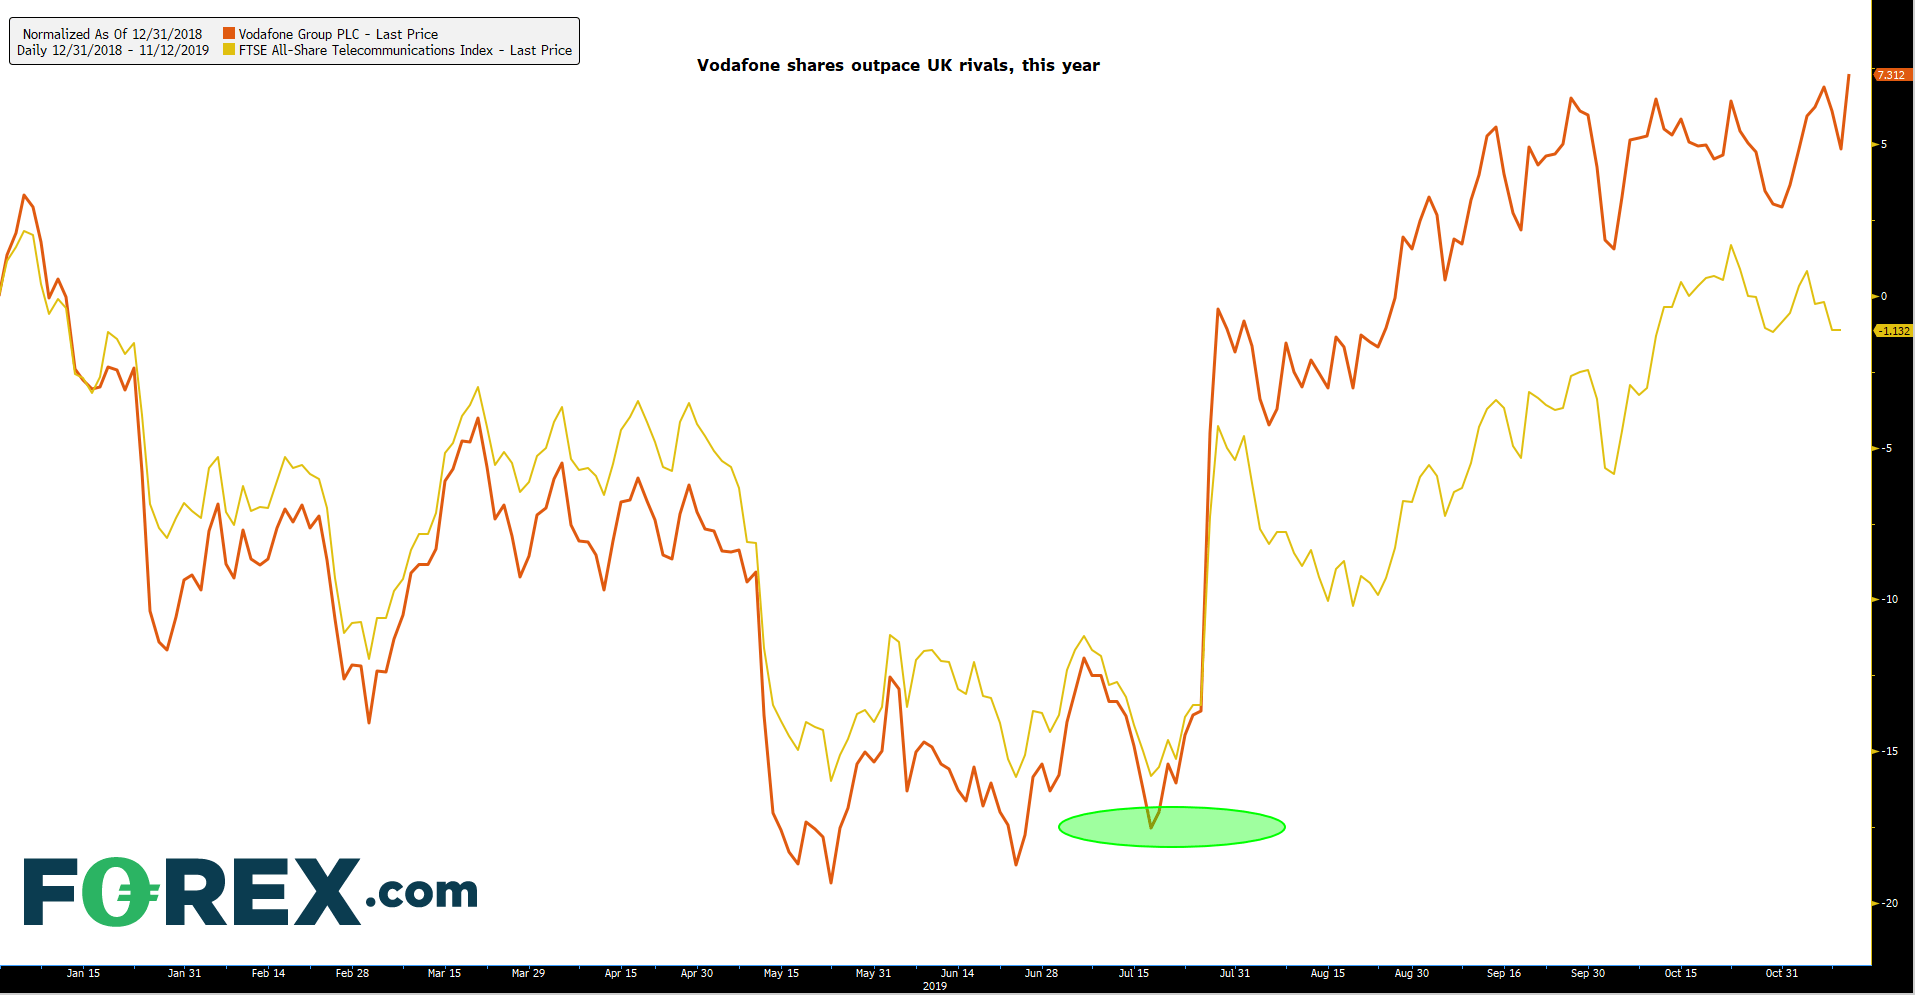
VOD shares have bounced from a 20% slump into the middle of the year to trade 7% higher so far in 2019. Latest results imply reduced impediments for the stock to recoup further into the year end. Still, the odds are better for steady rather than spectacular upside progress as VOD extends a mild outperformance of the UK sector. With shares now better underpinned, VOD’s total return of around 18.3 times now looks far more palatable relative to FTSE ALL-Share telecom peers’ trading on 18.4 x. Closing of the gap implies improved VOD stability ahead, so long as revenue, earnings and cash prospects remain on track.
Normalised: Vodafone Group Plc. / FTSE All-Share Telecommunications Index – year to date
Source: Bloomberg/FOREX.com
Rebounding service revenues and some turnarounds in Europe justify a medium-term benefit of the doubt
Organic rebound in context
Vodafone’s return to organic service revenue growth is the biggest relief in H1 results. The 0.7% year-on-year rise in the second quarter compares with 0.2% expected and more than erases Q1’s 0.2% decline. A sequential rebound leaves +0.3% on a half-year basis, pointing to a turnaround in Vodafone’s most important measure of revenues following two quarters of shrinking sales. Strengthening key sales on the back of improvements in some of Vodafone’s most troubled regions—South Africa, Spain and Italy—together with the best ever quarter for new UK customers have enabled a mild outlook upgrade.
Guidance signal
Adjusted Ebitda is now seen at €14.8bn-€15bn in the 2020 financial year compared with €13.8bn-€14.2bn before. Though the new forecast includes an €800m one-off boost from the purchase of some Liberty Global assets and the disposal of New Zealand operations, the midpoint of the new range is still €100m higher excluding those benefits. In effect, guidance is tightened with a slight shift to the higher end. It’s the most confident signal on guidance from Vodafone in the current financial year. CEO Nick Read duly confirmed that revenue growth is expected to continue through the remainder of the year in both Europe and Africa.
Tweak tempers relief
Investor relief has been evident in the stock’s rise of as much as 3.2%. As outlined in our preview, stabilisation of trouble spots like Spain, Italy and South Africa was necessary to safeguard underlying earnings goals, which were already lower than the year before. In turn, cash flow generation is critical for the dividend outlook after investors were forced to swallow a ‘rebase’ with an eye to lower debt and striking a better balance on spectrum costs and investments. Free cash flow guidance has been tweaked to “around” €5.4bn from “at least” €5.4bn. Although Vodafone shares pared their initial jump to a 2.3% gain by late morning, investors appear to have given Nick Read the benefit of the doubt on free cash flow goals. Greater clarity on earnings guidance helps.
Vodafone Idea still messy
The earnings guidance signal may even have encouraged the market to overlook persisting value destruction from Vodafone’s burdensome business in India. A €1.9bn loss was recorded for jointly owned Vodafone Idea with fierce competition exacerbated by a Supreme Court ruling. The UK group has struck some proceeds from the venture out from guidance whilst “financial relief” is sought from the government there. The update from India wasn’t as dire as feared by some investors, who suggested a write down of some €1bn was possible. Still, overall relief for the region remains some way off, providing ample room for critics who suspect Indian assets may eventually become worthless.
Germany, UK also stuck
Vodafone’s weak ‘coverage’ areas closer to home also remain evident, with a 1.4% H1 contraction in Europe, albeit that was still an improvement. Low margin wholesale businesses and stagnation in the mature markets of Germany and UK respectively look as intractable as ever. As such, some of Tuesday’s share fade is likely tied to medium-term prospects that may only have improved moderately, despite a relatively successful first half.
Stock price outlook
VOD shares have bounced from a 20% slump into the middle of the year to trade 7% higher so far in 2019. Latest results imply reduced impediments for the stock to recoup further into the year end. Still, the odds are better for steady rather than spectacular upside progress as VOD extends a mild outperformance of the UK sector. With shares now better underpinned, VOD’s total return of around 18.3 times now looks far more palatable relative to FTSE ALL-Share telecom peers’ trading on 18.4 x. Closing of the gap implies improved VOD stability ahead, so long as revenue, earnings and cash prospects remain on track.
Normalised: Vodafone Group Plc. / FTSE All-Share Telecommunications Index – year to date
Source: Bloomberg/City Index
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nvidia Earnings Preview: NVDA’s First Test of the Post Jenson Huang Era
Nvidia is expected to report $2.47 in EPS on $108.8B in revenue this quarter, but investors will be more interested in the company's guidance after the unexpected departure of founder and CEO Jenson Huang.

Nvidia Holds Support Ahead of Earnings as Nasdaq 100 Rebounds
Nvidia shares approach major support as selling pressure eases, while the Nasdaq 100 rebounds. Could upcoming earnings fuel a broader recovery?

S&P 500 Analysis: Earnings Uncertainty Continues to Weigh on the SPX
The trading week is coming to an end, and a phase of weakness remains evident across the S&P 500 in the short term. Recent price action reflects this dynamic, with SPX losing more than 2.00% over the last two trading sessions, bringing selling pressure back into focus.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.