



Week Ahead RBA RBNZ and US CPI
The week ahead features two key interest rate decisions from the Reserve Banks of Australia and New Zealand, as well top-tier data from the Eurozone, China and the US.
Share this:

The week ahead features two key interest rate decisions from the Reserve Banks of Australia and New Zealand, as well top-tier data from the Eurozone, China and the US. Speculators will be hoping that the pickup in volatility will continue next week after what has been a very quiet few months in some major FX markets. Their wishes may certainly come true if we see more surprises in next week’s economic events.
Monday could be a quieter session compared to the volatile conditions market participants witnessed on Friday as a result of the mixed-bag US jobs report. UK markets will be closed due to a bank holiday, which could mean smaller-than-usual ranges for the GBP/USD and other pound crosses. It is going to be a busy first half of the week for the euro and the single currency will be tested on Monday with the release of Eurozone retail sales, Sentix investor confidence and final PMIs. We have noted some improvement in Euro-area data of late, with core CPI inflation jumping to 1.2% on Friday, a six-month high. Let’s see if the momentum continues this week…
Tuesday: More Eurozone data will follow on Tuesday in the form of German factory orders. Investors are watching German data closely after the recent soft patch in macro pointers at the eurozone’s economic powerhouse. If the euro is to head back towards $1.15s again, it will need the support of a strong German economy.
Ahead of German factory orders data on Tuesday, it is likely that the Aussie dollar will have moved sharply in overnight trading in reaction to the interest rate decision from the Reserve Bank of Australia. The RBA has recently opened the door for a rate cut following a soft patch in Aussie data and the AUD has responded by depreciating noticeably. Last week, a very poor inflation report from Down Under hit the Aussie hard, with headline CPI remaining flat quarter-over-quarter and disappointing a rise of 0.2% expected. With building permits also slumping more than 15% this week, a growing number of analysts expect the RBA to trim benchmark interest rates to 1.25% from 1.50% at the moment.
The Reserve Bank of New Zealand is meeting on Wednesday but it is not clear whether it will cut interest rates at this meeting, although it could surprise given that the RBA is likely to trim its own interest rates the day before in order to prevent the NZD/AUD appreciating sharply. New Zealand data has also deteriorated in recent months, with quarterly employment data this week showing a surprise drop of 0.2% quarter-over-quarter when expectations were pointing to a 0.5% increase. Like the RBA, the RBNZ has also prepared the markets for a potential rate cut over the past couple of months.
Wednesday: China will also be in focus on Wednesday with the release of the latest trade figures. The world’s second largest economy has been in the spotlight due to its ongoing trade dispute with the US and investors have been quick to blame any weakness in data on that. Undoubtedly, any surprise improvement in trade figures will help underpin risk-sensitive assets. Meanwhile Chinese CPI will be published a day later on Thursday.
Global growth will remain a key talking point when the European session gets underway on Wednesday, as Germany’s latest industrial production data is published. A day earlier, we will have had German factory orders. So by Wednesday, we should have a better understanding about the health of some of the world’s largest economies.
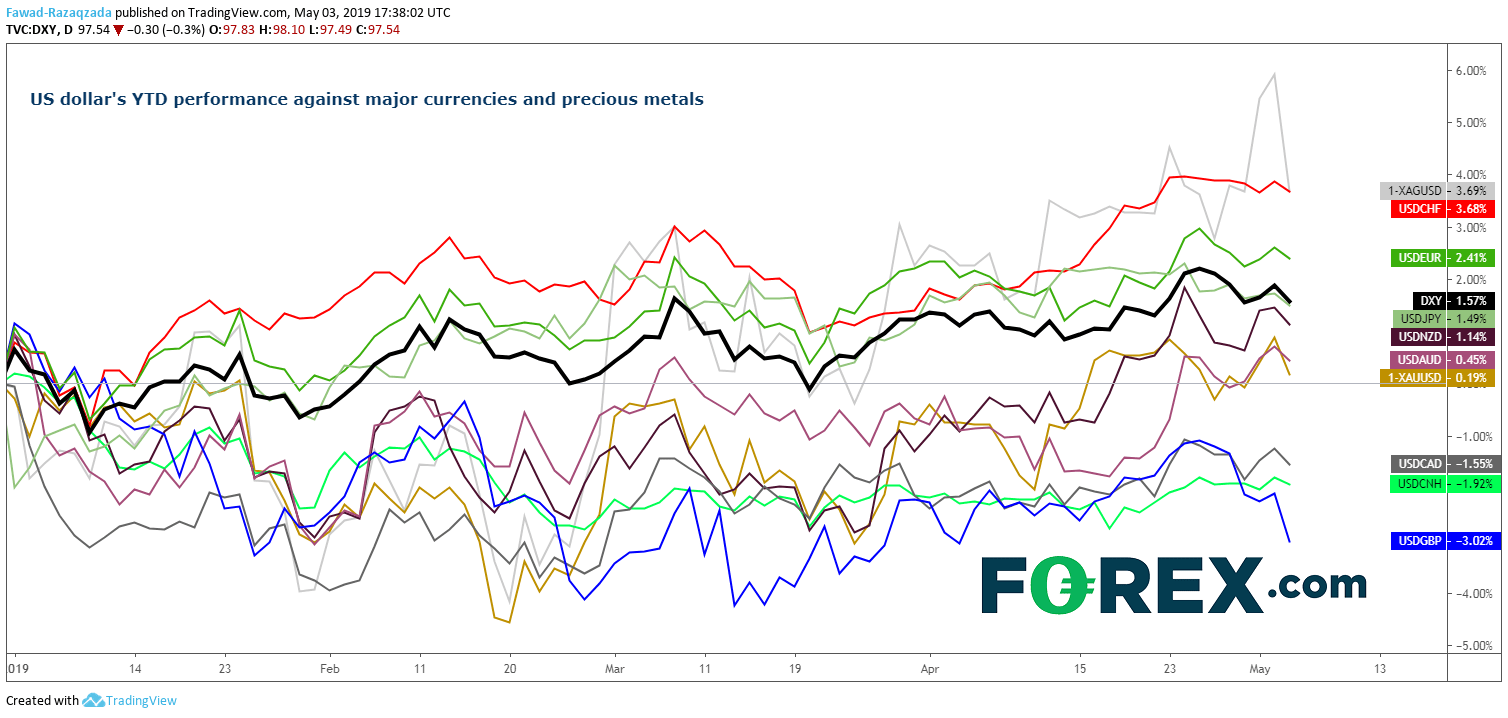
Friday will also be another busy day for data after a quiet-ish Thursday. We will have the first quarter UK GDP estimate, as well as construction and industrial data. The pound, which has outperformed her major rivals so far this year, could gain further ground should the latest economic pointers beat expectations. Meanwhile, Canada’s monthly employment report and U.S. consumer inflation data will be released during the North American session, meaning it will be a particularly busy day for the USD/CAD. With Friday’s US employment report showing decent jobs figures but slightly weaker wages growth, it will be interesting to see the latest inflation reading and what this might mean for interest rates outlook. A weak CPI print could seriously dent the dollar’s rally.
Source: TradingView and FOREX.com


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

GBP/USD, GBP/JPY, GBP/AUD: Sterling Eyes UK Inflation Catalyst
Sterling faces a pivotal UK inflation test as traders weigh BoE tightening, Fed minutes and Australian employment data across GBP/USD, GBP/JPY and GBP/AUD.


USD/MXN Forecast: Is Super Peso Making a Comeback?
The latest trading sessions have once again highlighted the strength of the Mexican peso. The currency has managed to regain a consistent appreciation trend in the short term, even despite the renewed strength displayed by the U.S. dollar in recent sessions.


EUR/USD outlook: euro back above 1.1000 as dollar rally loses steam
EUR/USD has recovered back above 1.1000 after a brief break lower, a sign the dollar's inflation-driven rally may be losing momentum. With a December Fed hike largely priced in and oil a potential tailwind for the euro, the risks are starting to tilt to the upside.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.