



19 08 EU PRE OPEN
European stocks report | Softcat | RWE | Alcon | Maersk...
Share this:

INDICES
Yesterday, European stocks were broadly lower. The Stoxx Europe 600 Index dropped 0.56%. Germany's DAX 30 slipped 0.30%, France's CAC 40 lost 0.68%, and the U.K.'s FTSE 100 was down 0.83%.
EUROPE ADVANCE/DECLINE
77% of STOXX 600 constituents traded lower or unchanged yesterday.
55% of the shares trade above their 20D MA vs 65% Monday (above the 20D moving average).
51% of the shares trade above their 200D MA vs 54% Monday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 0.49pt to 23.27, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Retail
3mths relative low: none
Europe Best 3 sectors
insurance, personal & household goods, retail
Europe worst 3 sectors
real estate, utilities, energy
INTEREST RATE
The 10yr Bund yield fell 3bps to -0.45% (above its 20D MA). The 2yr-10yr yield spread rose 1bp to -19bps (below its 20D MA).
ECONOMIC DATA
UK : UK-EU Brexit Talks
UK 07:00: Jul Retail Price Idx MoM, exp.: 0.2%
UK 07:00: Jul Retail Price Idx YoY, exp.: 1.1%
UK 07:00: Jul PPI Core Output YoY, exp.: 0.5%
UK 07:00: Jul PPI Core Output MoM, exp.: 0%
UK 07:00: Jul PPI Output YoY, exp.: -0.8%
UK 07:00: Jul PPI Input MoM, exp.: 2.4%
UK 07:00: Jul PPI Input YoY, exp.: -6.4%
UK 07:00: Jul PPI Output MoM, exp.: 0.3%
UK 07:00: Jul Core Inflation Rate YoY, exp.: 1.4%
UK 07:00: Jul Inflation Rate MoM, exp.: 0.1%
UK 07:00: Jul Inflation Rate YoY, exp.: 0.6%
UK 07:00: Jul Core Inflation Rate MoM, exp.: 0.2%
EC 09:00: Jun Current Account, exp.: E-10.5B
EC 10:00: Jul Core Inflation Rate YoY final, exp.: 0.8%
EC 10:00: Jul Inflation Rate MoM final, exp.: 0.3%
EC 10:00: Jul Inflation Rate YoY final, exp.: 0.3%
GE 10:40: 30-Year Bund auction, exp.: -0.06%
MORNING TRADING
In Asian trading hours, EUR/USD held gains at 1.1937 and GBP/USD was firm at 1.3244. USD/JPY remains subdued at 105.39. This morning, official data showed that Japan's exports declined 19.2% on year in July (-20.9% expected), while core machine orders dropped 7.6% on month in June (+2.0% expected).
Spot gold dropped to $1,994 an ounce.
#UK - IRELAND#
Softcat, an IT infrastructure provider, posted a full-year trading update: "Following the third quarter update provided in May, the Company has continued to trade satisfactorily during the final three months of the year and has delivered operating profit for the full year slightly ahead of the Board's expectations. Cash generation also remained strong and it is now the Company's intention to resume its normal dividend policy and timetable later this year. This will include payment of the interim dividend previously cancelled in March of this year."
Rio Tinto, a giant miner, has lowered its full-year refined copper production guidance to 135k - 175k tons from 165k - 205k tons previously, saying its "Kennecott mine in Utah has experienced delays to the restart of the smelter due to unexpected issues that appeared following planned maintenance."
#GERMANY#
RWE, an electric utilities company, said it has raised 2 billion euros from share issue to support its renewable energy expansion, including a 480 million dollars acquisition of the 2.7 GW project pipeline from Nordex as announced on July 31.
#BENELUX#
Galapagos, a pharmaceutical research company, reported that the U.S. Food and Drug Administration has requested data before completing its review of the New Drug Application for filgotinib, and "has expressed concerns regarding the overall benefit/risk profile of the filgotinib 200 mg dose".
#SWITZERLAND#
Alcon, an eye care company, posted 2Q core LPS of 0.21 dollar, compared with a core EPS of 0.47 dollar in the prior-year period, and net sales declined 36% on year (-34% at constant currency) to 1.20 billion dollars. The company said: "Due to the uncertain scope and duration of the ongoing COVID-19 outbreak, the Company is unable to provide an estimate for financial results for the full year 2020."
Clariant, a speciality chemicals company, was downgraded to "equalweight" from "overweight" at Barclays.
#DENMARK#
Maersk, a Danish integrated shipping company, announced that 2Q underlying profit from continuing operations jumped to 359 million dollars from 134 million dollars in the prior-year period, and EBITDA rose 25.1% on year to 1.70 billion dollars on revenue of 9.00 billion dollars, down 6.5%. The company said: " The continued improvement in operating results were driven by strong cost performance across all of our businesses, lower fuel prices and higher freight rates on Ocean and increased profitability in Logistics & Services. (...) Reinstating full-year guidance for 2020 with EBITDA expectations between USD 6.0bn-7.0bn compared to the initial full-year guidance of an EBITDA around USD 5.5bn."
GN Store Nord, a Danish manufacturer of hearing aids and headsets, reported that 2Q EPS declined 97% on year to 0.06 Danish krone and EBITA dropped 95% to 25 million Danish krone on revenue of 2.66 billion Danish krone, down 13%. The company said it was COVID-19 caused "ripple effects of production shutdown in Q1" and "various demand implications as consumers stayed at home, and as enterprises continued to invest in employees working from home".
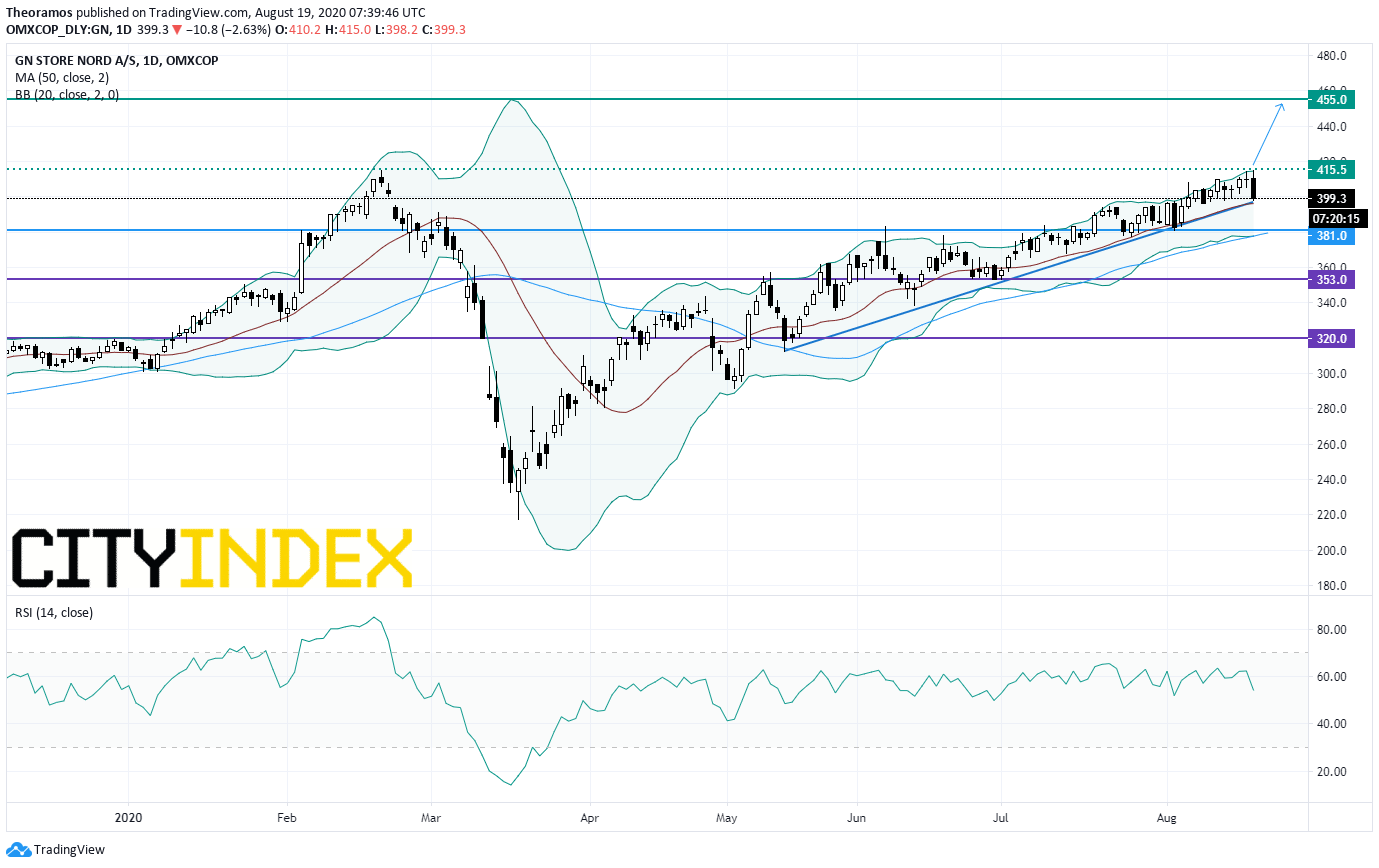
From a daily point of view, the stock is supported by a rising trend line drawn since May. Furthermore, the 20DMA is playing the role of support. A break above the previous all-time high of February at 415.5DKK would trigger a new up leg with a target set at 455DKK.
Source: GAIN Capital, TradingView
Yesterday, European stocks were broadly lower. The Stoxx Europe 600 Index dropped 0.56%. Germany's DAX 30 slipped 0.30%, France's CAC 40 lost 0.68%, and the U.K.'s FTSE 100 was down 0.83%.
EUROPE ADVANCE/DECLINE
77% of STOXX 600 constituents traded lower or unchanged yesterday.
55% of the shares trade above their 20D MA vs 65% Monday (above the 20D moving average).
51% of the shares trade above their 200D MA vs 54% Monday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 0.49pt to 23.27, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Retail
3mths relative low: none
Europe Best 3 sectors
insurance, personal & household goods, retail
Europe worst 3 sectors
real estate, utilities, energy
INTEREST RATE
The 10yr Bund yield fell 3bps to -0.45% (above its 20D MA). The 2yr-10yr yield spread rose 1bp to -19bps (below its 20D MA).
ECONOMIC DATA
UK : UK-EU Brexit Talks
UK 07:00: Jul Retail Price Idx MoM, exp.: 0.2%
UK 07:00: Jul Retail Price Idx YoY, exp.: 1.1%
UK 07:00: Jul PPI Core Output YoY, exp.: 0.5%
UK 07:00: Jul PPI Core Output MoM, exp.: 0%
UK 07:00: Jul PPI Output YoY, exp.: -0.8%
UK 07:00: Jul PPI Input MoM, exp.: 2.4%
UK 07:00: Jul PPI Input YoY, exp.: -6.4%
UK 07:00: Jul PPI Output MoM, exp.: 0.3%
UK 07:00: Jul Core Inflation Rate YoY, exp.: 1.4%
UK 07:00: Jul Inflation Rate MoM, exp.: 0.1%
UK 07:00: Jul Inflation Rate YoY, exp.: 0.6%
UK 07:00: Jul Core Inflation Rate MoM, exp.: 0.2%
EC 09:00: Jun Current Account, exp.: E-10.5B
EC 10:00: Jul Core Inflation Rate YoY final, exp.: 0.8%
EC 10:00: Jul Inflation Rate MoM final, exp.: 0.3%
EC 10:00: Jul Inflation Rate YoY final, exp.: 0.3%
GE 10:40: 30-Year Bund auction, exp.: -0.06%
MORNING TRADING
In Asian trading hours, EUR/USD held gains at 1.1937 and GBP/USD was firm at 1.3244. USD/JPY remains subdued at 105.39. This morning, official data showed that Japan's exports declined 19.2% on year in July (-20.9% expected), while core machine orders dropped 7.6% on month in June (+2.0% expected).
Spot gold dropped to $1,994 an ounce.
#UK - IRELAND#
Softcat, an IT infrastructure provider, posted a full-year trading update: "Following the third quarter update provided in May, the Company has continued to trade satisfactorily during the final three months of the year and has delivered operating profit for the full year slightly ahead of the Board's expectations. Cash generation also remained strong and it is now the Company's intention to resume its normal dividend policy and timetable later this year. This will include payment of the interim dividend previously cancelled in March of this year."
Rio Tinto, a giant miner, has lowered its full-year refined copper production guidance to 135k - 175k tons from 165k - 205k tons previously, saying its "Kennecott mine in Utah has experienced delays to the restart of the smelter due to unexpected issues that appeared following planned maintenance."
#GERMANY#
RWE, an electric utilities company, said it has raised 2 billion euros from share issue to support its renewable energy expansion, including a 480 million dollars acquisition of the 2.7 GW project pipeline from Nordex as announced on July 31.
#BENELUX#
Galapagos, a pharmaceutical research company, reported that the U.S. Food and Drug Administration has requested data before completing its review of the New Drug Application for filgotinib, and "has expressed concerns regarding the overall benefit/risk profile of the filgotinib 200 mg dose".
#SWITZERLAND#
Alcon, an eye care company, posted 2Q core LPS of 0.21 dollar, compared with a core EPS of 0.47 dollar in the prior-year period, and net sales declined 36% on year (-34% at constant currency) to 1.20 billion dollars. The company said: "Due to the uncertain scope and duration of the ongoing COVID-19 outbreak, the Company is unable to provide an estimate for financial results for the full year 2020."
Clariant, a speciality chemicals company, was downgraded to "equalweight" from "overweight" at Barclays.
#DENMARK#
Maersk, a Danish integrated shipping company, announced that 2Q underlying profit from continuing operations jumped to 359 million dollars from 134 million dollars in the prior-year period, and EBITDA rose 25.1% on year to 1.70 billion dollars on revenue of 9.00 billion dollars, down 6.5%. The company said: " The continued improvement in operating results were driven by strong cost performance across all of our businesses, lower fuel prices and higher freight rates on Ocean and increased profitability in Logistics & Services. (...) Reinstating full-year guidance for 2020 with EBITDA expectations between USD 6.0bn-7.0bn compared to the initial full-year guidance of an EBITDA around USD 5.5bn."
GN Store Nord, a Danish manufacturer of hearing aids and headsets, reported that 2Q EPS declined 97% on year to 0.06 Danish krone and EBITA dropped 95% to 25 million Danish krone on revenue of 2.66 billion Danish krone, down 13%. The company said it was COVID-19 caused "ripple effects of production shutdown in Q1" and "various demand implications as consumers stayed at home, and as enterprises continued to invest in employees working from home".
From a daily point of view, the stock is supported by a rising trend line drawn since May. Furthermore, the 20DMA is playing the role of support. A break above the previous all-time high of February at 415.5DKK would trigger a new up leg with a target set at 455DKK.
Source: GAIN Capital, TradingView
INDICES
Yesterday, European stocks were broadly lower. The Stoxx Europe 600 Index dropped 0.56%. Germany's DAX 30 slipped 0.30%, France's CAC 40 lost 0.68%, and the U.K.'s FTSE 100 was down 0.83%.
EUROPE ADVANCE/DECLINE
77% of STOXX 600 constituents traded lower or unchanged yesterday.
55% of the shares trade above their 20D MA vs 65% Monday (above the 20D moving average).
51% of the shares trade above their 200D MA vs 54% Monday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 0.49pt to 23.27, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Retail
3mths relative low: none
Europe Best 3 sectors
insurance, personal & household goods, retail
Europe worst 3 sectors
real estate, utilities, energy
INTEREST RATE
The 10yr Bund yield fell 3bps to -0.45% (above its 20D MA). The 2yr-10yr yield spread rose 1bp to -19bps (below its 20D MA).
ECONOMIC DATA
UK : UK-EU Brexit Talks
UK 07:00: Jul Retail Price Idx MoM, exp.: 0.2%
UK 07:00: Jul Retail Price Idx YoY, exp.: 1.1%
UK 07:00: Jul PPI Core Output YoY, exp.: 0.5%
UK 07:00: Jul PPI Core Output MoM, exp.: 0%
UK 07:00: Jul PPI Output YoY, exp.: -0.8%
UK 07:00: Jul PPI Input MoM, exp.: 2.4%
UK 07:00: Jul PPI Input YoY, exp.: -6.4%
UK 07:00: Jul PPI Output MoM, exp.: 0.3%
UK 07:00: Jul Core Inflation Rate YoY, exp.: 1.4%
UK 07:00: Jul Inflation Rate MoM, exp.: 0.1%
UK 07:00: Jul Inflation Rate YoY, exp.: 0.6%
UK 07:00: Jul Core Inflation Rate MoM, exp.: 0.2%
EC 09:00: Jun Current Account, exp.: E-10.5B
EC 10:00: Jul Core Inflation Rate YoY final, exp.: 0.8%
EC 10:00: Jul Inflation Rate MoM final, exp.: 0.3%
EC 10:00: Jul Inflation Rate YoY final, exp.: 0.3%
GE 10:40: 30-Year Bund auction, exp.: -0.06%
MORNING TRADING
In Asian trading hours, EUR/USD held gains at 1.1937 and GBP/USD was firm at 1.3244. USD/JPY remains subdued at 105.39. This morning, official data showed that Japan's exports declined 19.2% on year in July (-20.9% expected), while core machine orders dropped 7.6% on month in June (+2.0% expected).
Spot gold dropped to $1,994 an ounce.
#UK - IRELAND#
Softcat, an IT infrastructure provider, posted a full-year trading update: "Following the third quarter update provided in May, the Company has continued to trade satisfactorily during the final three months of the year and has delivered operating profit for the full year slightly ahead of the Board's expectations. Cash generation also remained strong and it is now the Company's intention to resume its normal dividend policy and timetable later this year. This will include payment of the interim dividend previously cancelled in March of this year."
Rio Tinto, a giant miner, has lowered its full-year refined copper production guidance to 135k - 175k tons from 165k - 205k tons previously, saying its "Kennecott mine in Utah has experienced delays to the restart of the smelter due to unexpected issues that appeared following planned maintenance."
#GERMANY#
RWE, an electric utilities company, said it has raised 2 billion euros from share issue to support its renewable energy expansion, including a 480 million dollars acquisition of the 2.7 GW project pipeline from Nordex as announced on July 31.
#BENELUX#
Galapagos, a pharmaceutical research company, reported that the U.S. Food and Drug Administration has requested data before completing its review of the New Drug Application for filgotinib, and "has expressed concerns regarding the overall benefit/risk profile of the filgotinib 200 mg dose".
#SWITZERLAND#
Alcon, an eye care company, posted 2Q core LPS of 0.21 dollar, compared with a core EPS of 0.47 dollar in the prior-year period, and net sales declined 36% on year (-34% at constant currency) to 1.20 billion dollars. The company said: "Due to the uncertain scope and duration of the ongoing COVID-19 outbreak, the Company is unable to provide an estimate for financial results for the full year 2020."
Clariant, a speciality chemicals company, was downgraded to "equalweight" from "overweight" at Barclays.
#DENMARK#
Maersk, a Danish integrated shipping company, announced that 2Q underlying profit from continuing operations jumped to 359 million dollars from 134 million dollars in the prior-year period, and EBITDA rose 25.1% on year to 1.70 billion dollars on revenue of 9.00 billion dollars, down 6.5%. The company said: " The continued improvement in operating results were driven by strong cost performance across all of our businesses, lower fuel prices and higher freight rates on Ocean and increased profitability in Logistics & Services. (...) Reinstating full-year guidance for 2020 with EBITDA expectations between USD 6.0bn-7.0bn compared to the initial full-year guidance of an EBITDA around USD 5.5bn."
GN Store Nord, a Danish manufacturer of hearing aids and headsets, reported that 2Q EPS declined 97% on year to 0.06 Danish krone and EBITA dropped 95% to 25 million Danish krone on revenue of 2.66 billion Danish krone, down 13%. The company said it was COVID-19 caused "ripple effects of production shutdown in Q1" and "various demand implications as consumers stayed at home, and as enterprises continued to invest in employees working from home".
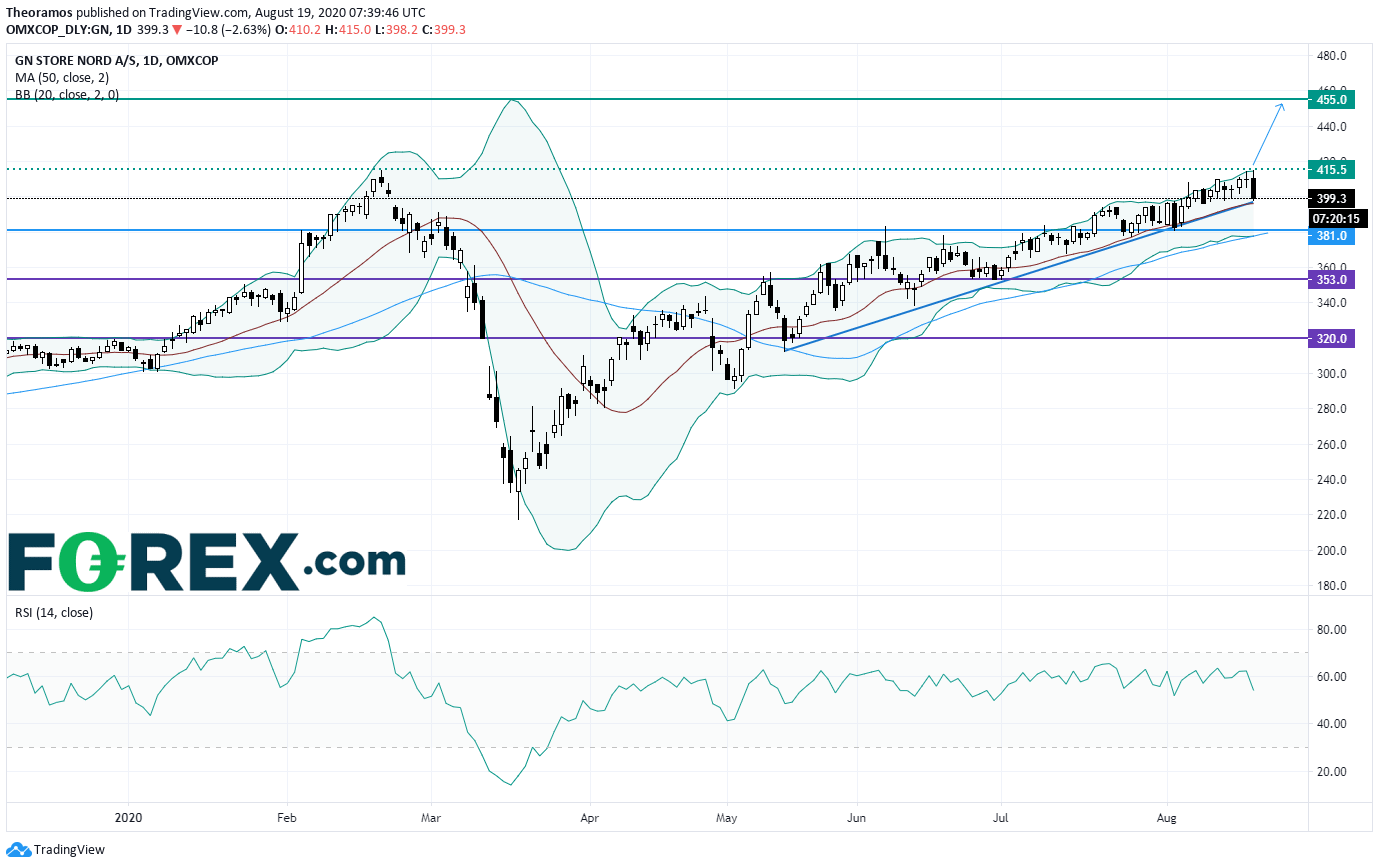
From a daily point of view, the stock is supported by a rising trend line drawn since May. Furthermore, the 20DMA is playing the role of support. A break above the previous all-time high of February at 415.5DKK would trigger a new up leg with a target set at 455DKK.
Source: GAIN Capital, TradingView
Yesterday, European stocks were broadly lower. The Stoxx Europe 600 Index dropped 0.56%. Germany's DAX 30 slipped 0.30%, France's CAC 40 lost 0.68%, and the U.K.'s FTSE 100 was down 0.83%.
EUROPE ADVANCE/DECLINE
77% of STOXX 600 constituents traded lower or unchanged yesterday.
55% of the shares trade above their 20D MA vs 65% Monday (above the 20D moving average).
51% of the shares trade above their 200D MA vs 54% Monday (above the 20D moving average).
The Euro Stoxx 50 Volatility index added 0.49pt to 23.27, a new 52w high.
SECTORS vs STOXX 600
3mths relative high: Retail
3mths relative low: none
Europe Best 3 sectors
insurance, personal & household goods, retail
Europe worst 3 sectors
real estate, utilities, energy
INTEREST RATE
The 10yr Bund yield fell 3bps to -0.45% (above its 20D MA). The 2yr-10yr yield spread rose 1bp to -19bps (below its 20D MA).
ECONOMIC DATA
UK : UK-EU Brexit Talks
UK 07:00: Jul Retail Price Idx MoM, exp.: 0.2%
UK 07:00: Jul Retail Price Idx YoY, exp.: 1.1%
UK 07:00: Jul PPI Core Output YoY, exp.: 0.5%
UK 07:00: Jul PPI Core Output MoM, exp.: 0%
UK 07:00: Jul PPI Output YoY, exp.: -0.8%
UK 07:00: Jul PPI Input MoM, exp.: 2.4%
UK 07:00: Jul PPI Input YoY, exp.: -6.4%
UK 07:00: Jul PPI Output MoM, exp.: 0.3%
UK 07:00: Jul Core Inflation Rate YoY, exp.: 1.4%
UK 07:00: Jul Inflation Rate MoM, exp.: 0.1%
UK 07:00: Jul Inflation Rate YoY, exp.: 0.6%
UK 07:00: Jul Core Inflation Rate MoM, exp.: 0.2%
EC 09:00: Jun Current Account, exp.: E-10.5B
EC 10:00: Jul Core Inflation Rate YoY final, exp.: 0.8%
EC 10:00: Jul Inflation Rate MoM final, exp.: 0.3%
EC 10:00: Jul Inflation Rate YoY final, exp.: 0.3%
GE 10:40: 30-Year Bund auction, exp.: -0.06%
MORNING TRADING
In Asian trading hours, EUR/USD held gains at 1.1937 and GBP/USD was firm at 1.3244. USD/JPY remains subdued at 105.39. This morning, official data showed that Japan's exports declined 19.2% on year in July (-20.9% expected), while core machine orders dropped 7.6% on month in June (+2.0% expected).
Spot gold dropped to $1,994 an ounce.
#UK - IRELAND#
Softcat, an IT infrastructure provider, posted a full-year trading update: "Following the third quarter update provided in May, the Company has continued to trade satisfactorily during the final three months of the year and has delivered operating profit for the full year slightly ahead of the Board's expectations. Cash generation also remained strong and it is now the Company's intention to resume its normal dividend policy and timetable later this year. This will include payment of the interim dividend previously cancelled in March of this year."
Rio Tinto, a giant miner, has lowered its full-year refined copper production guidance to 135k - 175k tons from 165k - 205k tons previously, saying its "Kennecott mine in Utah has experienced delays to the restart of the smelter due to unexpected issues that appeared following planned maintenance."
#GERMANY#
RWE, an electric utilities company, said it has raised 2 billion euros from share issue to support its renewable energy expansion, including a 480 million dollars acquisition of the 2.7 GW project pipeline from Nordex as announced on July 31.
#BENELUX#
Galapagos, a pharmaceutical research company, reported that the U.S. Food and Drug Administration has requested data before completing its review of the New Drug Application for filgotinib, and "has expressed concerns regarding the overall benefit/risk profile of the filgotinib 200 mg dose".
#SWITZERLAND#
Alcon, an eye care company, posted 2Q core LPS of 0.21 dollar, compared with a core EPS of 0.47 dollar in the prior-year period, and net sales declined 36% on year (-34% at constant currency) to 1.20 billion dollars. The company said: "Due to the uncertain scope and duration of the ongoing COVID-19 outbreak, the Company is unable to provide an estimate for financial results for the full year 2020."
Clariant, a speciality chemicals company, was downgraded to "equalweight" from "overweight" at Barclays.
#DENMARK#
Maersk, a Danish integrated shipping company, announced that 2Q underlying profit from continuing operations jumped to 359 million dollars from 134 million dollars in the prior-year period, and EBITDA rose 25.1% on year to 1.70 billion dollars on revenue of 9.00 billion dollars, down 6.5%. The company said: " The continued improvement in operating results were driven by strong cost performance across all of our businesses, lower fuel prices and higher freight rates on Ocean and increased profitability in Logistics & Services. (...) Reinstating full-year guidance for 2020 with EBITDA expectations between USD 6.0bn-7.0bn compared to the initial full-year guidance of an EBITDA around USD 5.5bn."
GN Store Nord, a Danish manufacturer of hearing aids and headsets, reported that 2Q EPS declined 97% on year to 0.06 Danish krone and EBITA dropped 95% to 25 million Danish krone on revenue of 2.66 billion Danish krone, down 13%. The company said it was COVID-19 caused "ripple effects of production shutdown in Q1" and "various demand implications as consumers stayed at home, and as enterprises continued to invest in employees working from home".
From a daily point of view, the stock is supported by a rising trend line drawn since May. Furthermore, the 20DMA is playing the role of support. A break above the previous all-time high of February at 415.5DKK would trigger a new up leg with a target set at 455DKK.
Source: GAIN Capital, TradingView
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.


USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.