





Asian Open Dollar Dominates and Equities Fall on Hawkish Fed
Well, the Fed didn’t wait for the Jackson hole symposium to turn hawkish (from a very dovish base), sending equities, commodities lower and the US dollars higher.
Share this:
The S&P 500 and Nasdaq 100 are on track to close lower for a third week, a bearish sequence not seen since July. I suspect the selloff is reaching a near-term exhaustion point, given both indices are now trading back above their 50-week EMAs.
And as their 3-week selloffs began with a lower could suggest that they’re in no hurry to reach a new record high in the near term. Even if history stacks the odds of new record highs heavily in their favour further out. Furthermore, market positioning of the Nasdaq 100 and S&P 500 futures markets show that bets against it are on the rise, which bolsters my case that any incoming bounce could be short lived.
Nasdaq 100 Futures (NQ) Market Positioning – COT report
I am seeing mixed signals between large speculators and asset managers. I generally find the latter to be better at tracking the direction of indices, so more weigh shall given to this subset of trader. Asset managers increased their gross-short exposure to a near 2-year high last week and trimmed longs, which dragged net-long exposure down to a 23-week low. Yet large speculators trimmed both longs and shorts. For this reason, my expectation is for the Nasdaq to trade lower in a few weeks from now, but price action also suggests a bounce could be due first.
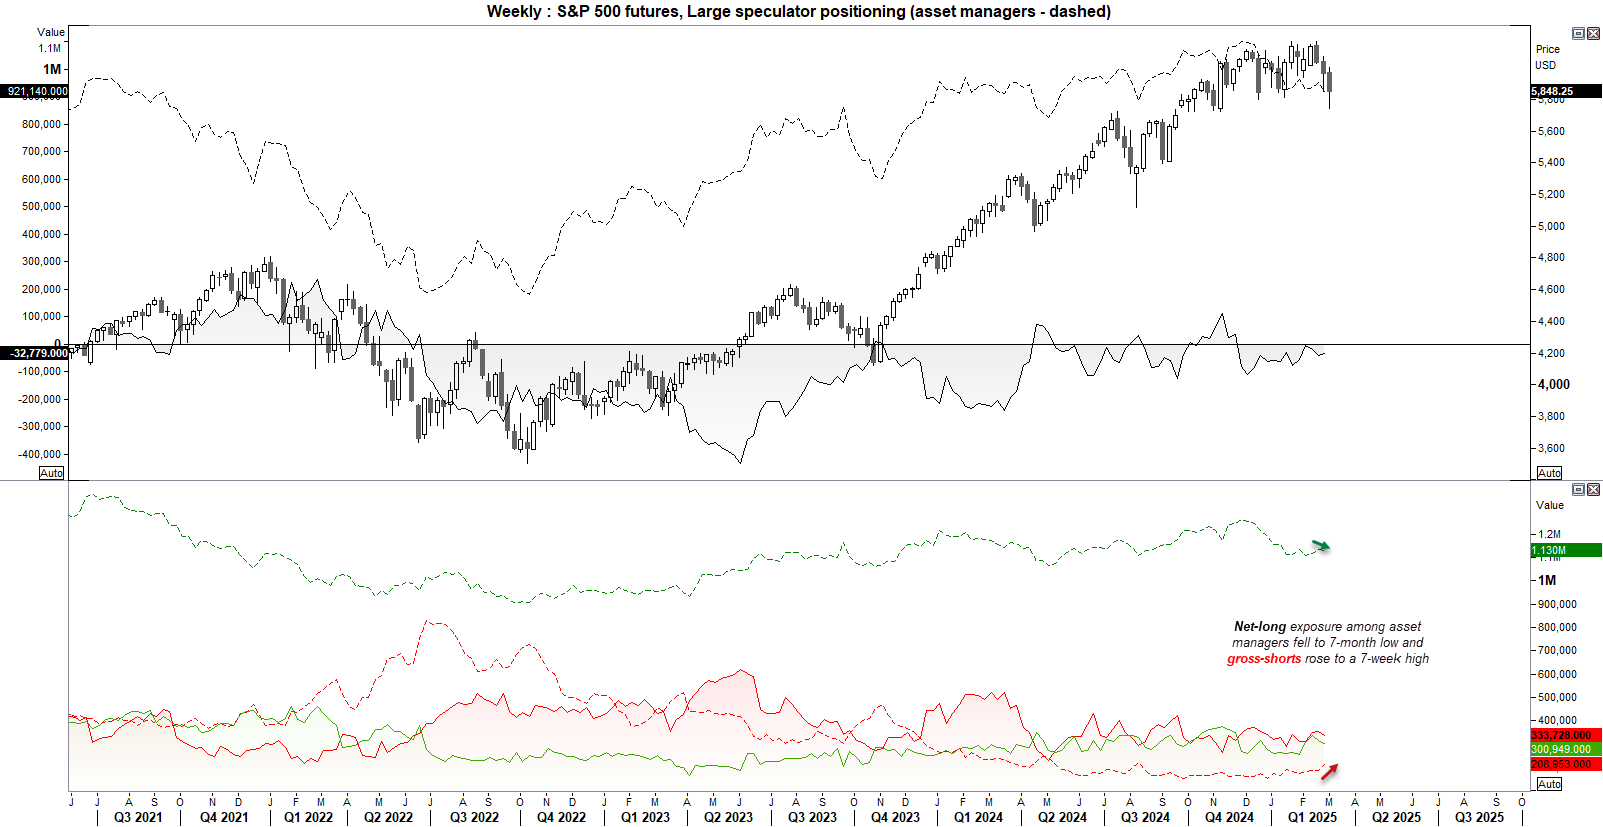
S&P 500 Futures (ES) Market Positioning – COT Report
Again, we’re seeing net-long exposure fall on the S&P 500 among asset managers, although net-short exposure has declined among large speculators. But as the latter group saw a reduction of longs and shorts, their bullish case is far from compelling.
Meanwhile, asset managers have increased their gross-short exposure to S&P 500 futures to a 7-month high and trimmed longs. And this suggests the same as above; any bounce could be short lived and a break to a new record high is not currently favoured.
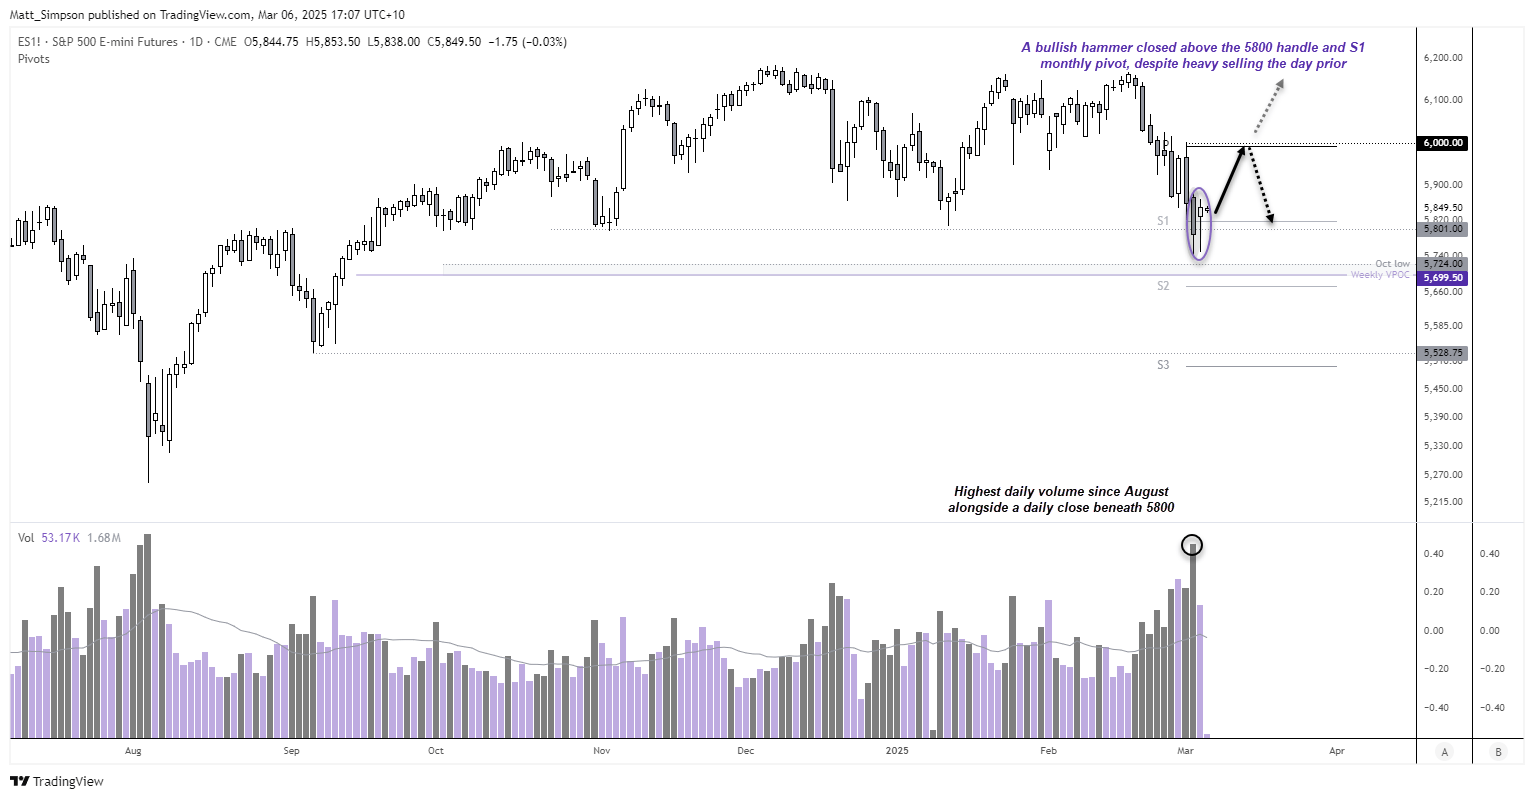
S&P 500 futures technical analysis
A daily close beneath the November low and 5800 level was accompanied by the heaviest daily volumes since August. While this shows bears clearly dominated the session, they must be disappointed with Wednesday’s bullish hammer, which was also a small bullish inside day which close back above 5800 and the monthly S1 pivot.
The bias is to seek dips within yesterday’s range while prices hold above Tuesday’s low, in anticipation of a move towards 6,00 near the monthly pivot point.
I can reassess sentiment if this plays out, but for now the bias is for a bounce to occur ahead of its next leg lower.
Nasdaq 100 futures technical analysis
It could argued that price action on Nasdaq futures are marginally more bullish than those seen on the S&p 500. While both formed a bullish hammer on Wednesday, the Nasdaq printed a doji instead of a decisively bearish bar with a daily close beneath key resistance. The doji also found support at the monthly S1 pivot, just above a weekly VPOC (volume point of control) and 20k handle.
Like the S&P 500, the bias is for a bounce towards the monthly pivot ahead of its next leg lower.
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.