



AU Q4 CPI preview and what lies ahead for the ASX200
The rout in U.S. stock markets deepened last week on concerns over rising interest rates and heightened tensions between Russia and Ukraine. The broader U.S. share market has now fallen 8.3% from its high of early January, while the tech-heavy Nasdaq is down ~14% from its all-time high from November.
Share this:
The negative lead from Wall Street weighed on the Australian share market, the ASX200, as it closed out the week almost 3% lower at 7175. The heavy falls coming despite last week's robust Australian labour force data and additional monetary policy easing by Chinese authorities.
Ahead of this Thursday's crucial FOMC meeting, the ASX200 will need to negotiate the release of Australian Q4 CPI data tomorrow morning, before the RBA's next Board Meeting on February 1.
Headline inflation is expected to rise by 1% q/q on the back of gains in petrol prices and new dwellings, taking the annual inflation rate up to 3.2% y/y. The trimmed mean (core or underlying inflation) is expected to rise 0.7 %q/q, taking the annual rate of underlying inflation to 2.4% y/y, above the 2.25% forecast by the RBA in November.
Presuming tomorrow's inflations numbers come in at or higher than expected, and following the robust jobs data last week, it will likely confirm the end of quantitative easing (QE) at the RBA's February meeting. It may also prompt the RBA to elect to shrink its balance sheets as bonds mature, aka quantitative tightening (QT).
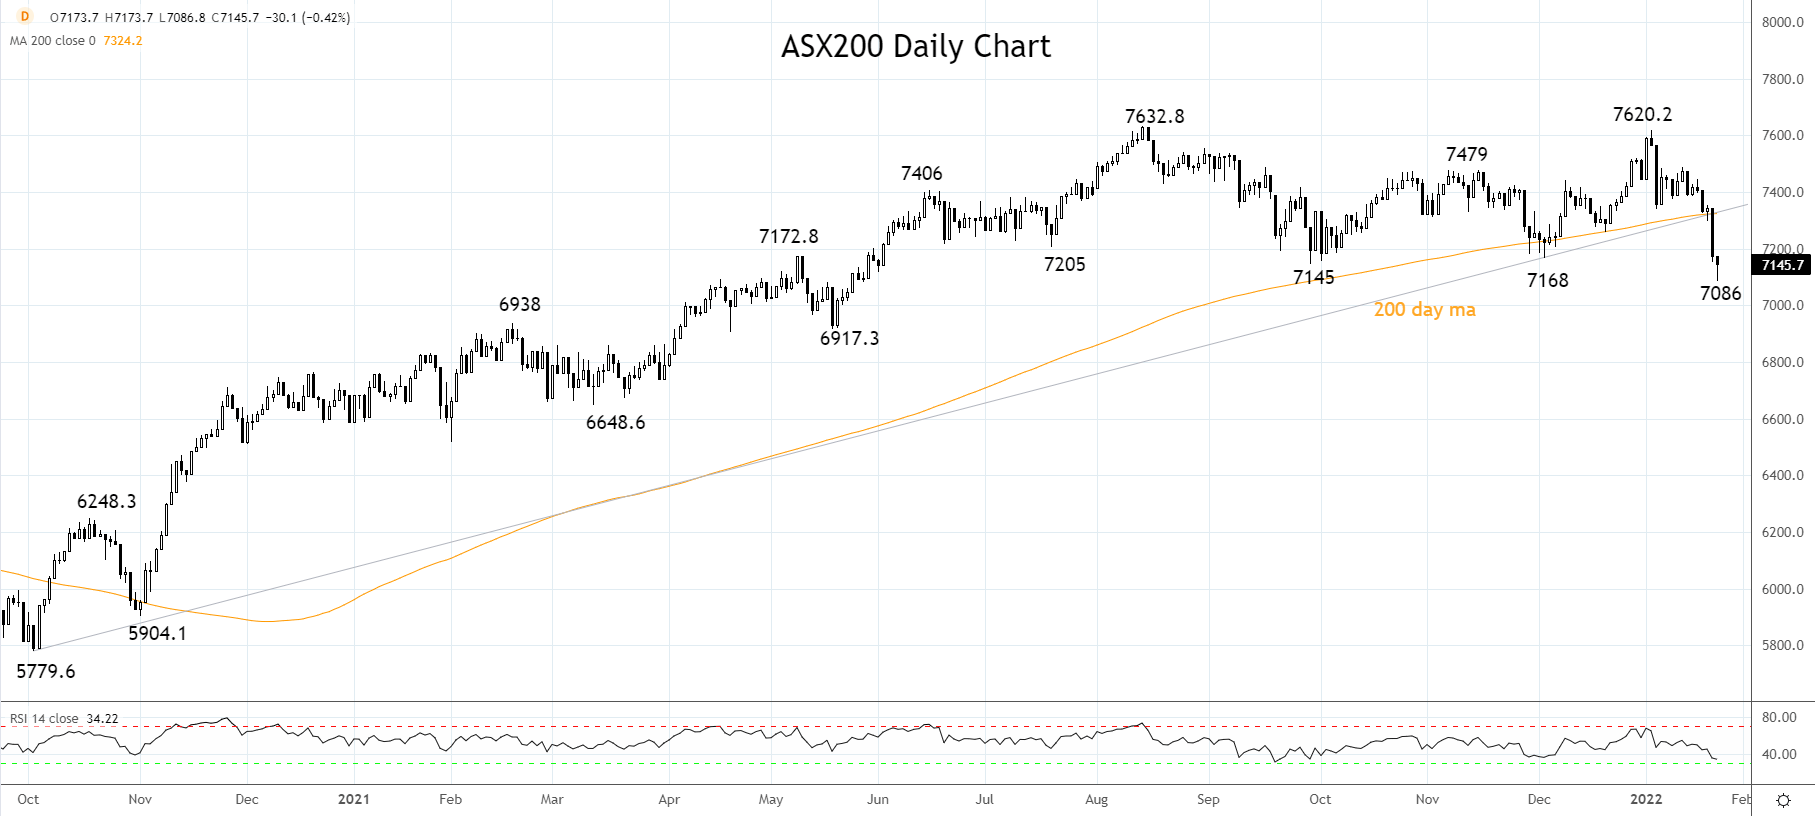
The break of critical support at 7310/00 noted in this article last week here has seen the initial pullback target of 7150 reached in rapid time.
"A sustained break below 7310/00 would warn a deeper pullback is underway initially towards 7150 before 7000."
There remains scope for the pullback to continue lower towards 7030/00, which, if achieved, would amount to an ~8.5% pullback from the August 7632 high.To negate the bearish bias and provide the first indication that the correction is complete, the ASX200 needs to reclaim the 7320/00 breakdown level.
Source Tradingview. The figures stated areas of January 24, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The negative lead from Wall Street weighed on the Australian share market, the ASX200, as it closed out the week almost 3% lower at 7175. The heavy falls coming despite last week's robust Australian labour force data and additional monetary policy easing by Chinese authorities.
Ahead of this Thursday's crucial FOMC meeting, the ASX200 will need to negotiate the release of Australian Q$ CPI data tomorrow morning, before the RBA's next Board Meeting on February 1.
Headline inflation is expected to rise by 1% q/q on the back of gains in petrol prices and new dwellings, taking the annual inflation rate up to 3.2% y/y. The trimmed mean (core or underlying inflation) is expected to rise 0.7 %q/q, taking the annual rate of underlying inflation to 2.4% y/y, above the 2.25% forecast by the RBA in November.
Presuming tomorrow's inflations numbers come in at or higher than expected, and following the robust jobs data last week, it will likely confirm the end of quantitative easing (QE) at the RBA's February meeting. It may also prompt the RBA to elect to shrink its balance sheets as bonds mature, aka quantitative tightening (QT).
The break of critical support at 7310/00 noted in this article last week here has seen the initial pullback target of 7150 reached in rapid time.
"A sustained break below 7310/00 would warn a deeper pullback is underway initially towards 7150 before 7000."
There remains scope for the pullback to continue lower towards 7030/00, which, if achieved, would amount to an ~8.5% pullback from the August 7632 high. To negate the bearish bias and provide the first indication that the correction is complete, the ASX200 needs to reclaim the 7320/00 breakdown level.
Source Tradingview. The figures stated areas of January 24, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Brazil Elections: Is Investor Confidence Beginning to Fade?
One of the most relevant events for emerging markets in recent sessions has been the outcome of Brazil’s presidential election. Following Lula da Silva’s victory in the second round, investor sentiment began to deteriorate noticeably. This can be observed in both the iShares MSCI Brazil ETF and the VanEck Brazil Small-Cap ETF, two important benchmarks for tracking the Brazilian equity market, both of which have posted declines of more than 15% at the start of the week.

Weekly Equities Outlook: Amazon, Alphabet and Lloyds
Big tech earnings ramp up, with Amazon, Alphabet and Microsoft updating the market as worries over heavy AI spending weigh on sentiment. UK banks are also in focus ahead of the Budget, with earnings from Lloyds, NatWest, Standard Chartered, and HSBC.

Silver Forecast: XAG/USD Hits Fresh 2026 Lows as Selling Pressure Accelerates
Trading conditions continue to be challenging for silver in the short term. The precious metal has been losing value at an accelerated pace and, during today's session alone, has fallen more than 5.5%, reaching new lows for 2026. This development highlights how selling pressure has become increasingly dominant across recent market activity.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.