



Outlook for the Brazilian Real and the real economy
Bullish Factors Copom minutes may fail to ease past credibility problems and perception of divergence in last week's decision, worsening agents' future expectations and weakening the real. Bearish Factors Copom minutes can ease credibility problems and perception of past divergence in last week's decision and contribute to stabilizing future expectations of agents, strengthening the real. Consumer inflation in the US may remain a gentle slowdown, consolidating expectations that the Fed's interest rate hike cycle has ended, weakening the USDBRL. Economic data in Brazil may reinforce the perception that economic activity remains better than expected and inflation continues to moderate, favoring an optimistic reading of Brazilian assets and strengthening the real.
Share this:

Bullish Factors
- Copom minutes may fail to ease past credibility problems and perception of divergence in last week's decision, worsening agents' future expectations and weakening the real.
Bearish Factors
- Copom minutes can ease credibility problems and perception of past divergence in last week's decision and contribute to stabilizing future expectations of agents, strengthening the real.
- Consumer inflation in the US may remain a gentle slowdown, consolidating expectations that the Fed's interest rate hike cycle has ended, weakening the USDBRL.
- Economic data in Brazil may reinforce the perception that economic activity remains better than expected and inflation continues to moderate, favoring an optimistic reading of Brazilian assets and strengthening the real.
Week in review
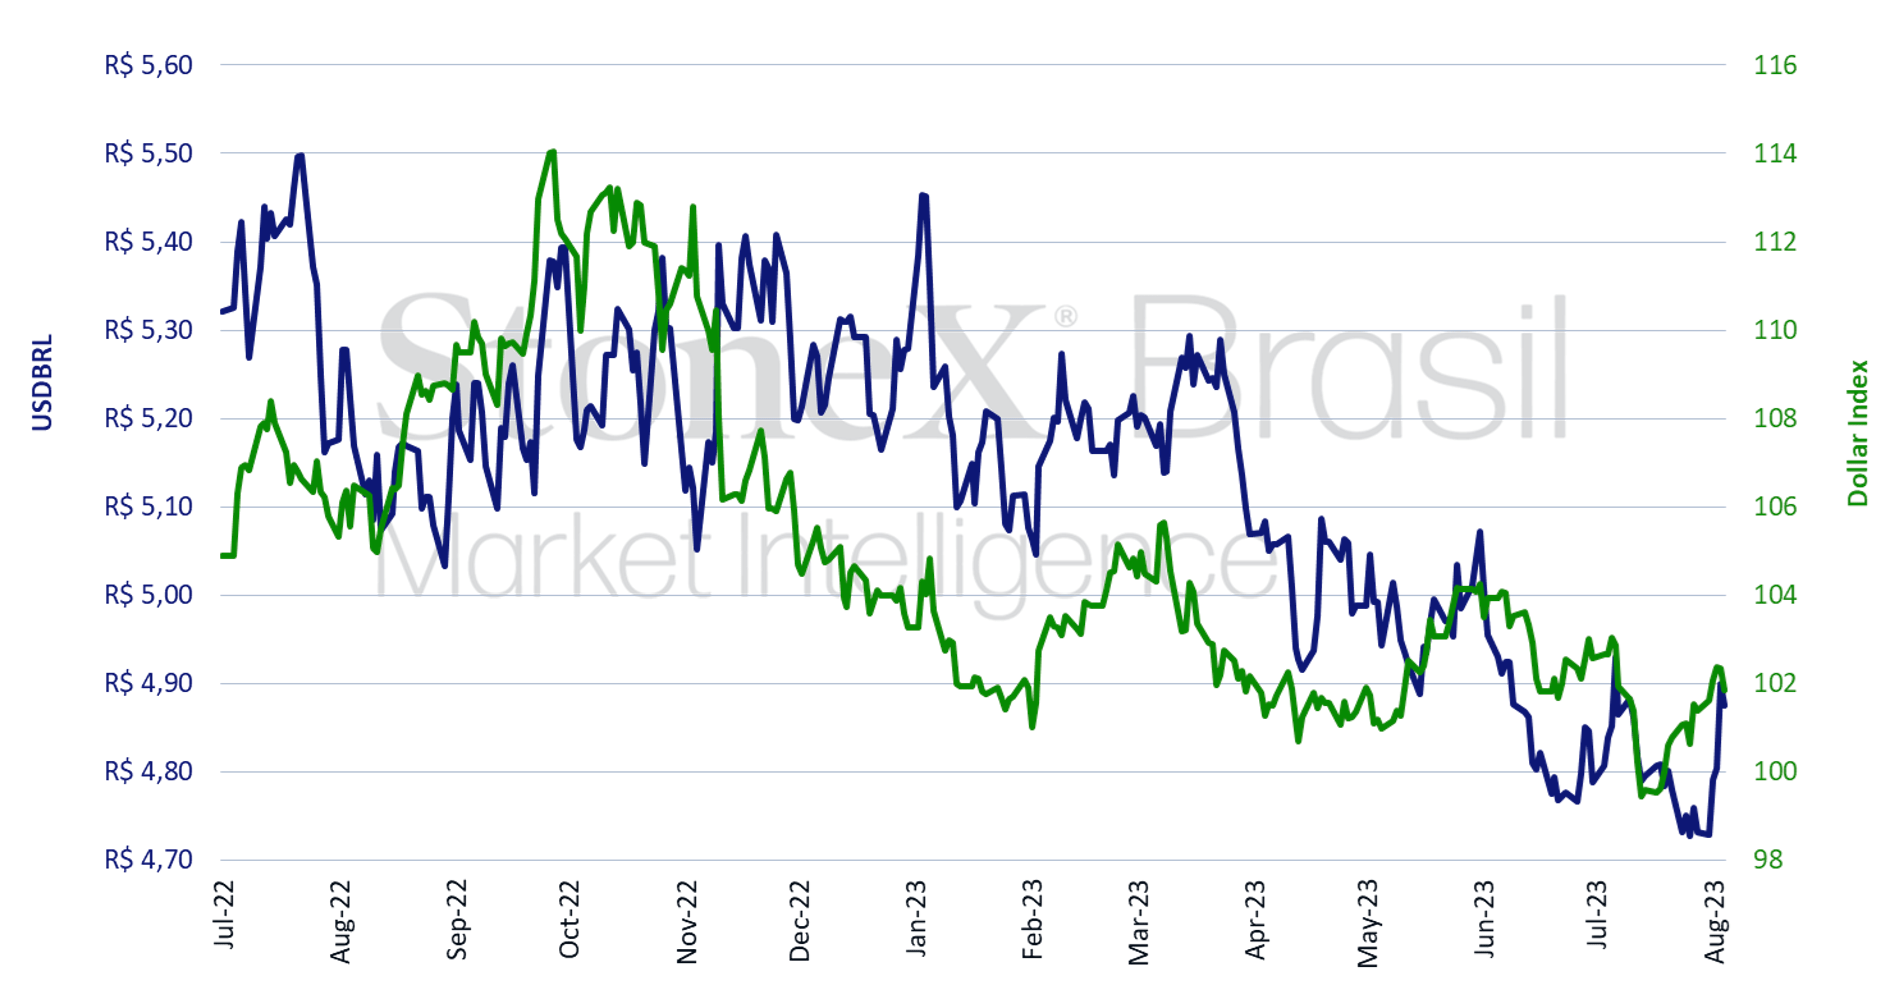
The USDBRL ended the week higher, ending Friday's session (04) at BRL 4.875, a variation of +3.0% in the week, +3.1% in the month and -7.7% in the year. The dollar index closed the session at 101.9 points, a weekly gain of 0.5% and monthly 0,2%, but an annual decline of 1.4%. The foreign exchange market reflected the decision of the Central Bank of Brazil's Monetary Policy Committee (Copom), which caused a strong devaluation of the BRL amid expectations of a reduction in interest rates in Brazil. Additionally, weak economic data in Europe and China contributed to weekly gains in the US currency abroad.
USDBRL and Dollar Index (points)
Source: StoneX cmdtyView. Design: StoneX
Most important event: Copom minutes
Expected impact on USDBRL: uncertain
The investors' attention this week should be on the Copom minutes. Last week, Copom's decision to reduce the basic interest rate (Selic) from 13.75% p.a. to 13.25% p.a. as well as to signal a new readjustment of the same magnitude for the September meeting provoked an intense weakening of the BRL, which was attributed by some to a lack of credibility of the committee's stance.
Initially, the tight scoreboard for the decision caught the attention of analysts, with five votes in favor of a 0.50 p.p. cut in Selic and four votes in favor of a 0.25 p.p. cut, with the tie-breaking vote given by the president of the institution, Roberto Campos Neto. On the other hand, there was consensus among the committee members to signal the intention of a further reduction of 0.50 p.p. in September if the conjuncture evolves according to projections. The minutes bring risks for both a strengthening and a weakening of the BRL depending on how this division is explained, what arguments were considered by each group of votes and how this impacts the reading of the inflation and interes t trajectory by the committee.
Another frequent question this week was the change in stance between June when the Copom statement did not even mention the possibility of reducing interest rates and the minutes only mentioned the possibility of a “parsimonious process” of easing, and August, when its members opted for the fastest pace in its reduction. Similarly, the absence of mentions of fiscal policy in the balance sheet of inflationary risks for the first time since 2017 also caught the attention of analysts. The minutes can contribute significantly to more efficient and transparent communication about the Copom decision-making process and how market players should anticipate future analyses and decisions.
Inflation in the United States
Expected impact on USDBRL: bearish
The release of the Consumer Price Index (CPI) for July should influence the reading of other macroeconomic data throughout August. Analysts' projections point to a moderate reading for the third consecutive month in both the overall index and its core (which excludes the volatile food and energy components), with a median monthly increase expectation of 0.2% for both – which would represent an annualized rate of less than 2%, a target sought by the Federal Reserve. If these forecasts are confirmed, the data should reinforce the interpretation that inflationary pressure in the country is easing and that the Fed's interest rate hike cycle should have ended, which could weaken the US currency.
Economic data for Brazil
Expected impact on USDBRL: bearish
Investors will also follow the release of the National Broad Consumer Price Index (IPCA) for July, which is expected to come close to zero for the second consecutive month, reinforcing the perception that price pressure in Brazil is moderating and there is room for monetary easing by the Central Bank. In addition, the Central Bank's Economic Activity Index (IBC-Br) for June will be released, showing slight growth after an unexpected contraction in May.
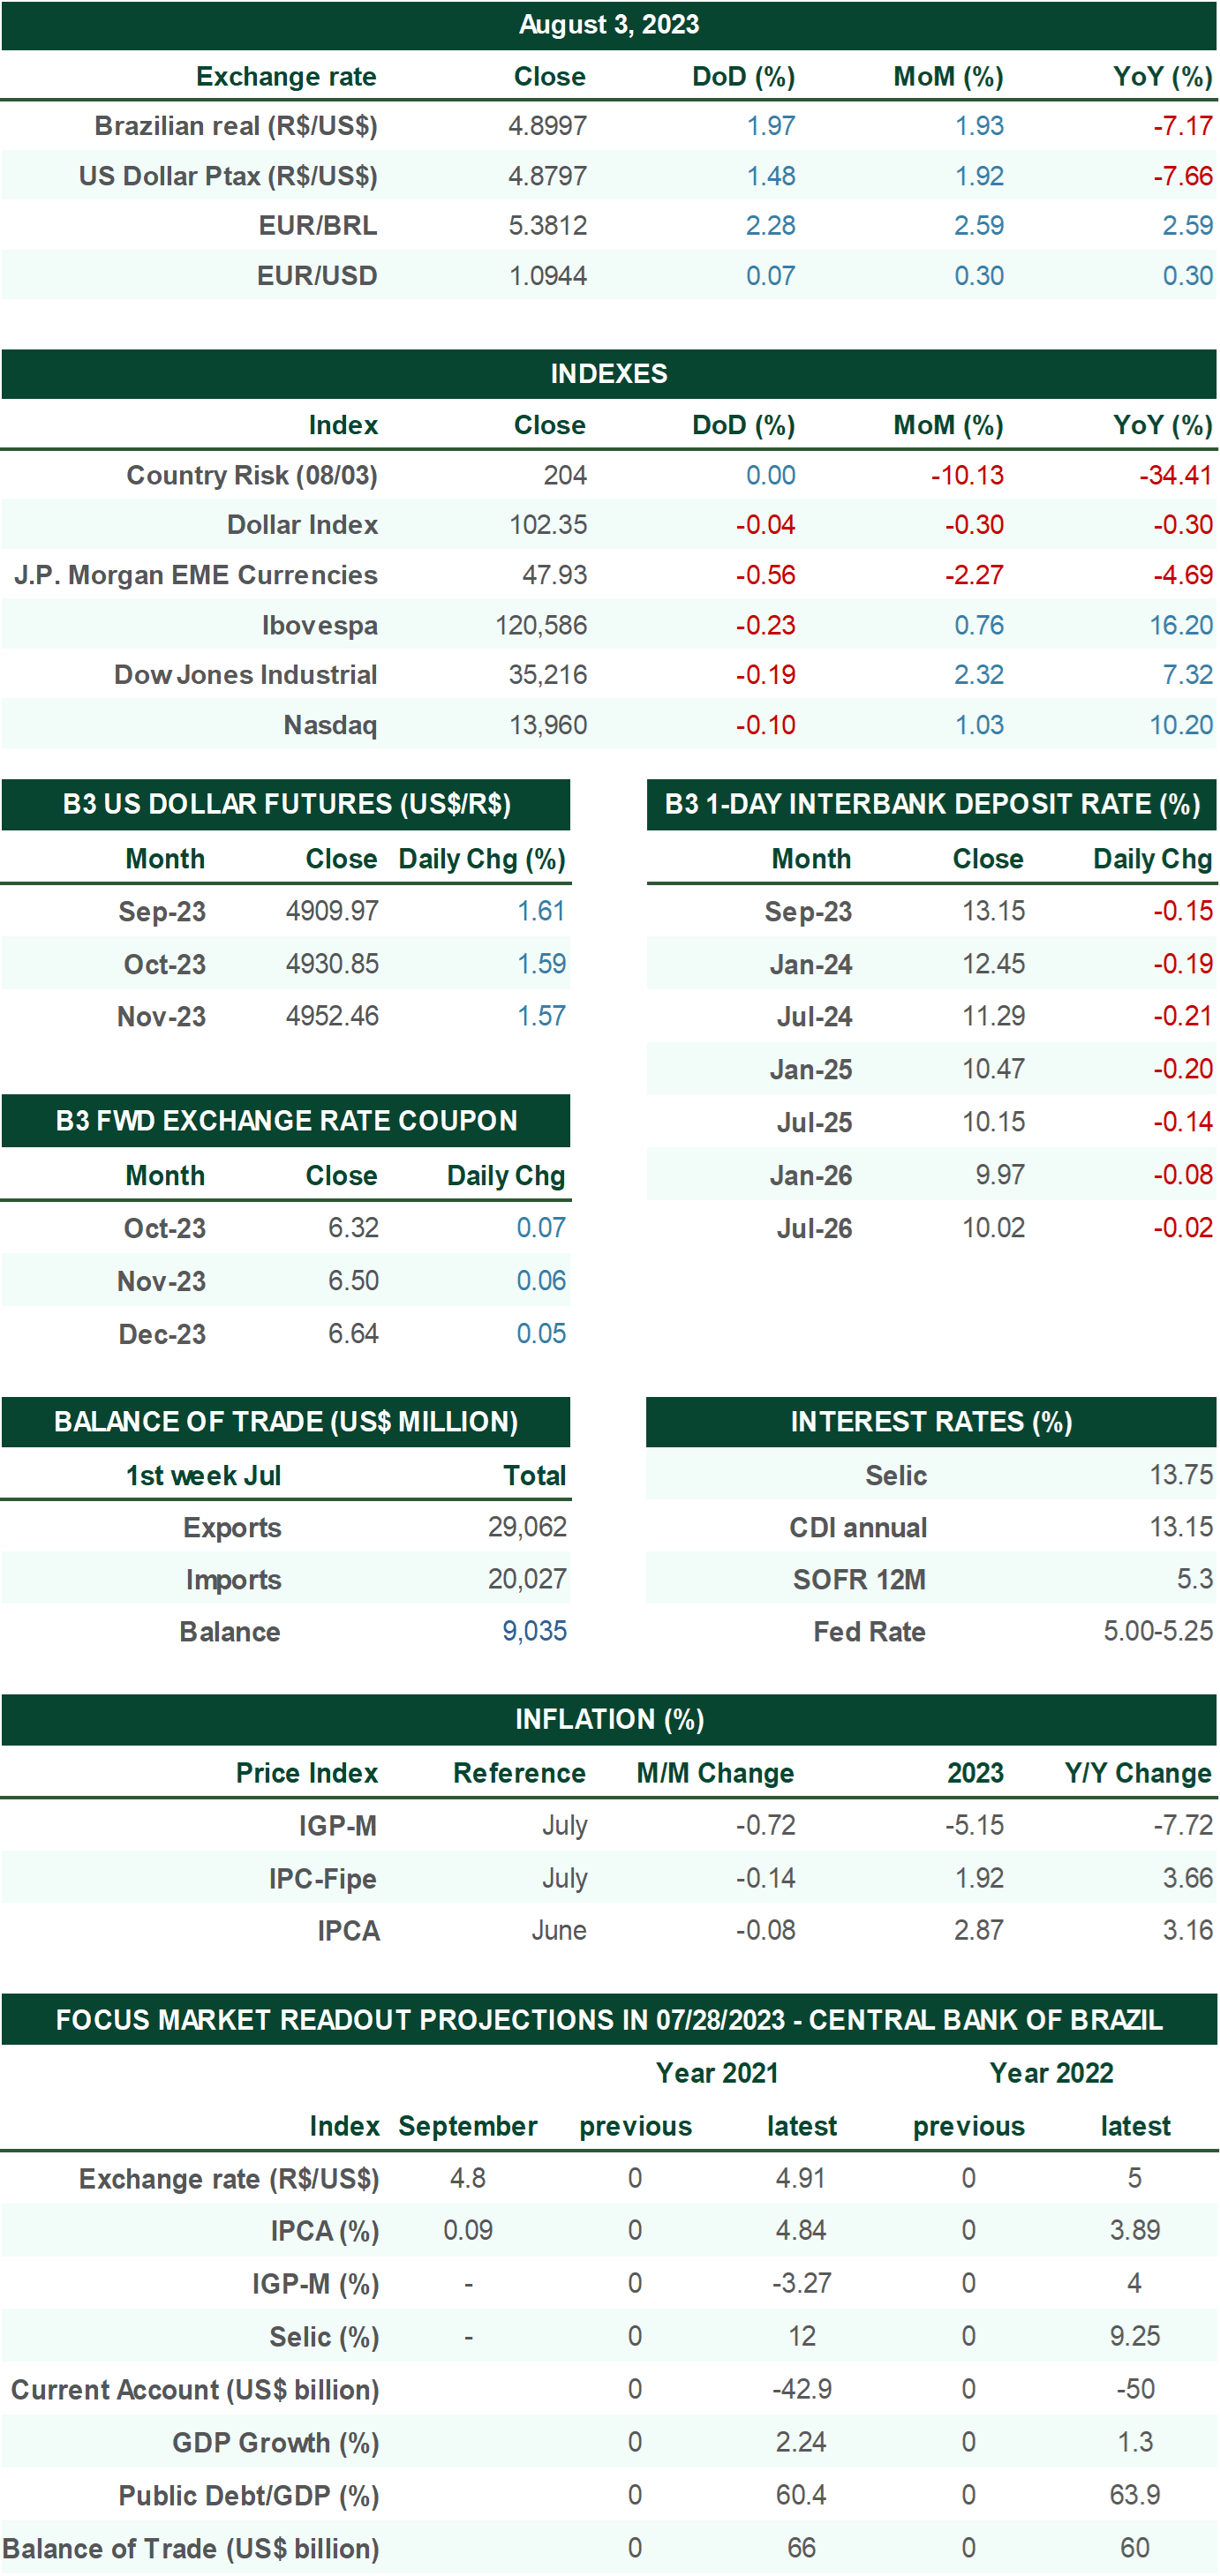
Key Indicators
Sources: Central Bank of Brazil; B3; IBGE; Fipe; FGV; MDIC; IPEA and StoneX cmdtyView.
Our Brazil team provides regular weekly coverage of the Brazilian economy and the outlook for the Real, accessible by clicking the link in the banner above.
Analysis by: Leonel Oliveira Mattos ([email protected]), Alan Lima ([email protected]), and Vitor Andrioli ([email protected]).
Financial editor: Paul Walton ([email protected]).
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

USD/JPY Q4 2026 Outlook: Hawkish Fed Pricing Clashes With Intervention Risk
The year-end tug-of-war is clear: hawkish Fed pricing supports USD/JPY, while intervention risk limits the upside.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.