

DAX Outlook: 27,000 Rejection Puts Key Support in Focus
The DAX faces a critical test after failing to sustain its breakout above 27,000. Opening weakness puts the 26,663 support zone in focus, while the broader uptrend remains intact. US producer inflation, European GDP data and Fed speakers could drive volatility throughout the session. Meanwhile, NVIDIA's reported leadership shake-up and a Microsoft service disruption add uncertainty to technology stocks.
Share this:
Friday, 13 November 2026 | 09:00 CET cash open
1. Overnight & Pre-Market Action
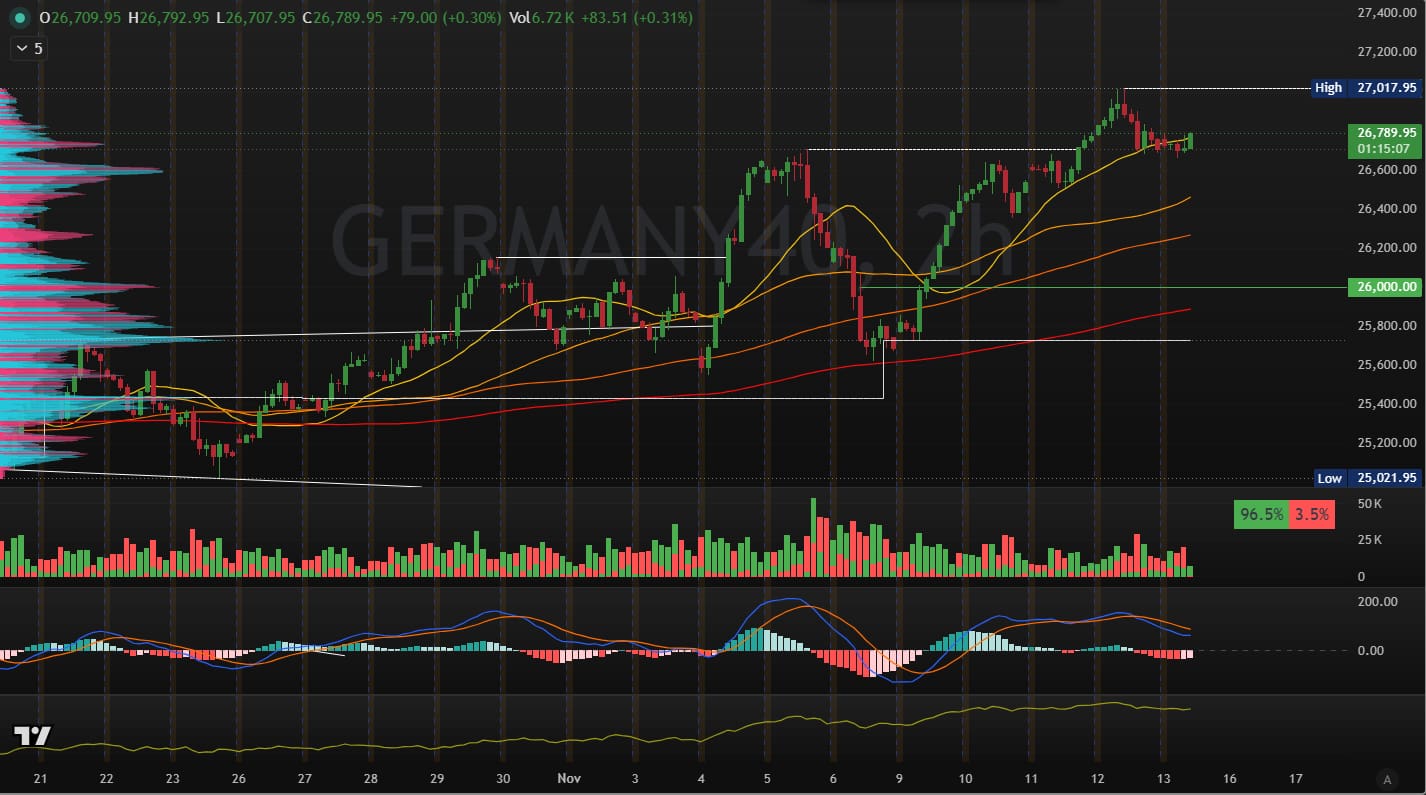
- Opening picture: The DAX indication stood at 26,728.25 at 08:59, approximately 44 points, or 0.16%, below Thursday’s cash close of 26,771.88. Yesterday’s 0.41% gain masked a retreat from the record 27,014.2 high: buyers failed to hold 27,000.
- Overnight futures range: Through 08:26, December DAX futures traded between 26,726 and 26,851, a 125-point range. The latest reading was 26,811, down 84 points, or 0.31%, against the previous futures close. These are futures prices, separate from the cash levels below.
- Overseas lead: Wall Street finished modestly lower: S&P 500 −0.35% and Nasdaq 100 −0.30%. Asian trading was mixed, with Japan recovering while Chinese markets remained weaker.
2. Macro & Catalyst Watch
- 10:00 — IEA Oil Market Report: Changes to supply and demand forecasts could move crude, inflation expectations and sentiment towards European industrial companies.
- 11:00 — Euro-area GDP, employment and trade: The second Q3 GDP estimate, initial employment figures and September trade balance provide the morning’s main European growth check.
- 14:30 — US October producer prices: The main scheduled volatility risk. Consensus is +0.4% month-on-month for headline PPI and +0.3% for core. An upside surprise could lift bond yields and pressure equities; softer figures would ease that pressure.
- Central-bank speakers: Collins at 15:10, Logan at 15:40, Bowman at 16:50, Nagel at 17:00 and Daly at 18:00. Nagel addresses Europe’s economic outlook. Several Fed appearances concern banking or regulation, so monetary-policy guidance is not assured.
- Pre-open earnings: Richemont and Generali at 07:00; Bechtle at 07:30. Their releases provide broader European sector signals. No new DAX constituent earnings appear on the checked daily calendar.
3. Key Technical Levels
- Resistance 1 — 26,772: Thursday’s close; the first meaningful recovery test and potential opening-gap fill.
- Resistance 2 — 26,900–26,911: The round number and Thursday’s opening level.
- Resistance 3 — 27,000–27,002: The psychological barrier and record high; the principal upside hurdle.
- Support 1 — 26,663–26,671: Wednesday’s high/close and Thursday’s low. This is the immediate decision zone.
- Support 2 — 26,634: Tuesday’s high, a nearby former breakout level.
- Support 3 — 26,492–26,500: Wednesday’s low and the psychological 26,500 level.
- Daily trend context: At Thursday’s close, the 20-day SMA was 25,874, the 50-day 25,592 and the 200-day 24,940. Price remains above all three simple moving averages. They support the broader constructive assessment but sit too far away to serve as immediate opening levels.
4. Base Case vs. Alternative Scenario
- Base case — consolidation with a recovery bias: While 26,663 holds, the opening weakness fits a pullback within the broader advance. The first objective is 26,772. A completed 15-minute cash candle above that level strengthens the case for 26,911, followed by another test of 27,000.
- Exact invalidation — a 15-minute cash close below 26,663: This flips the near-term bias bearish, exposing 26,634 and then 26,492–26,500. A subsequent 15-minute close back above 26,772 cancels that bearish scenario. These confirmation rules are the analytical framework for this brief; a brief intrabar move does not qualify.
5. Beyond the DAX
- Microsoft outage: At 08:24, Microsoft had reported improving server stability but had not declared full recovery. Outlook access and email delivery, some Teams calendar functions and Copilot features remained affected. Core Teams calls and chats largely remained available. Microsoft reported no evidence of malicious activity.
- NVIDIA leadership shock: Jensen Huang resigned as CEO, president and director, with CFO Colette Kress becoming interim CEO. Shares closed 4.3% lower after falling almost 12% intraday. The next major test is earnings on 17 November at approximately 22:20 CET, when attention turns to guidance and execution under the new leadership.
Philip J Papageorgiou - Head of Investment Research
Follow me on X (ex Twitter) - PhilipForexCom

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 forecast: SPX struggles for direction ahead of PPI data
U.S. stocks are struggling for direction on Friday as investors continue to weigh up the fallout from Nvidia’s leadership change, rising Treasury yields and the upcoming U.S. producer price inflation data.
Bitcoin, Gold Outlook: Bullish Hold or Bearish Shift?
Bitcoin, Gold Outlook: The dollar’s surge to new 2026 highs and approach toward nine-month resistance are raising near-term reversal risks across precious metals and currency markets. This follows recent declines that pushed Bitcoin below $70,000 and gold below $3,870.

DAX Outlook: 27,000 Rejection Puts Key Support in Focus
The DAX faces a critical test after failing to sustain its breakout above 27,000. Opening weakness puts the 26,663 support zone in focus, while the broader uptrend remains intact. US producer inflation, European GDP data and Fed speakers could drive volatility throughout the session. Meanwhile, NVIDIA's reported leadership shake-up and a Microsoft service disruption add uncertainty to technology stocks.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.