

S&P 500 forecast: SPX struggles for direction ahead of PPI data
U.S. stocks are struggling for direction on Friday as investors continue to weigh up the fallout from Nvidia’s leadership change, rising Treasury yields and the upcoming U.S. producer price inflation data.
Share this:

U.S. futures
Dow futures: +0.09%, S&P 500 futures: +0.1%, Nasdaq futures: +0.3%
European futures
FTSE: +0.03%, DAX: -0.13%
- U.S. stocks struggle for direction ahead of PPI inflation data.
- Nvidia is stabilising but is still on track for its longest weekly losing streak since 2012.
- U.S. Treasury yields remain elevated, with the 10-year above 5.1%.
- Oil falls across the week.
U.S. stocks struggle for direction with Nvidia and inflation data in focus
U.S. stocks are struggling for direction on Friday as investors continue to weigh up the fallout from Nvidia’s leadership change, rising Treasury yields and the upcoming U.S. producer price inflation data.
U.S. stock indices are pointing to a muted open after closing in the red on Thursday, as the mood remains cautious, particularly surrounding technology stocks and the fallout from the Nvidia saga. Attention will start to turn to Nvidia’s earnings next week, as well as Anthropic’s IPO, for further cues on the AI trade.
Elsewhere, Treasury yields are rising ahead of U.S. Producer Price Index data later today. The 10-year yield has risen above 5.1%, while the 30-year yield has moved towards 5.5%.
The rise in yields this week comes after hotter-than-expected U.S. CPI inflation, hawkish Fed commentary and a jump in oil prices yesterday. However, oil has eased today and is set to decline on the week.
All eyes are on PPI inflation data, which is expected to show factory-gate inflation rising 6.6% year on year in October, up from 6.3%. On a monthly basis, it is expected to rise 0.4%, down from 1.3% in September. Hotter-than-expected PPI data could point to further rises in CPI inflation. This could lift Treasury yields and the U.S. dollar while weighing on stocks.
Corporate movers
The sell-off in Nvidia is stabilising today, but the AI chipmaker is still on track for its longest weekly losing streak since 2012, as its market value has fallen by US$1.6 trillion. CEO Jensen Huang resigned yesterday amid reports of numerous affairs, including an alleged relationship with a Chinese spy who reportedly has ties to China and Nvidia’s biggest Chinese competitor.
Nvidia’s turmoil has prompted a rotation across chip stocks, with investors reacting to uncertainty surrounding its leadership by rotating into sector peers such as AMD, which is trading 30% higher this week, Broadcom and even TSMC. This is also happening as investors consider whether competitors could have an opportunity to catch up.
Microsoft is in focus, as its workplace services, including Outlook, Teams and Copilot, experienced outages for several hours late on Thursday and into Friday, disrupting users across multiple regions. The firm has cited elevated server loads as the likely cause of connectivity issues and is working to redistribute traffic. Its share price is set to fall 2%.
Cisco reported better-than-expected Q1 results on Thursday and raised its full-year outlook. Its CEO said the industry was in the early stages of a networking supercycle, as revenue came in at $18.5 billion, beating analyst expectations of $18.14 billion.
S&P 500 forecast – technical analysis
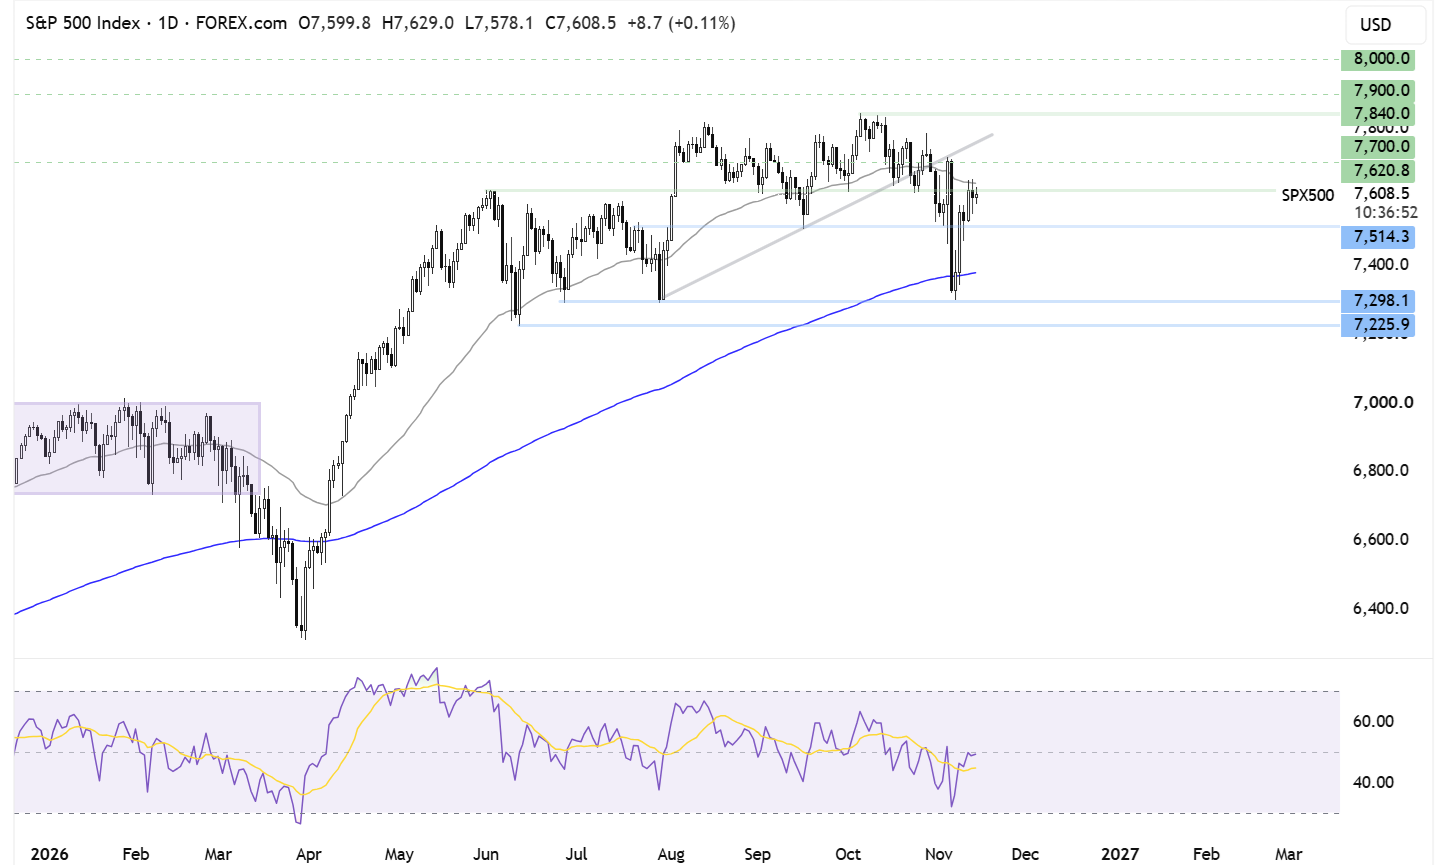
The S&P 500 recovered from the 7,300 low, rising back above the 200 EMA to 7,620, the horizontal resistance level, and the 50 EMA at 7,635. Buyers will look to extend the recovery above the 50 EMA at 7,645 to put the price on a firmer footing.
A rise above 7,700 opens the door to 7,840 and fresh record highs.
On the downside, immediate support is seen at 7,500, the September low. A break below here exposes the 200 EMA at 7,375, ahead of 7,300, the November low. Sellers would need to take out this level to create a lower low.
FX markets – USD rising, GBP/USD falls
The U.S. dollar is rising to fresh 19-month highs, building on recent momentum and driven by expectations of further rate hikes from the Federal Reserve. The market has cemented expectations for another rate hike in December and is also pricing in the possibility of an outsized 50-basis-point hike.
EUR/USD is consolidating below 1.11 after closing lower for three consecutive sessions and reaching its lowest level since April 2025, below 1.1050.
Data today showed Eurozone GDP rose 0.4% quarter on quarter in Q3, in line with the preliminary estimate. The euro has come under pressure against both the dollar and sterling, despite expectations that the ECB will hike rates again in December. However, with two hikes already under its belt, this could be one of the last in the current hiking cycle, increasing the policy divergence between a more hawkish Fed and the ECB.
GBP/USD is falling further on Friday and is on track to lose almost 1% this week, amid a stronger U.S. dollar and despite UK GDP data showing the strongest UK growth in 2.5 years. The data supports the Bank of England’s rate hike at the start of the month, and the market currently prices in a 75% chance of another rate hike in December.
Oil falls for a second week
Oil prices are edging lower on Friday and heading for a second straight weekly decline, amid concerns over whether supply from the Middle East will ease despite renewed direct attacks on shipping through the Strait of Hormuz.
Oil prices tumbled last week, with Brent down 16% and WTI down 13%. Both benchmarks are on track to decline a further 3% this week.
Investors continue to weigh up developments in the Middle East, where there appears to be little prospect of either a deal or increased military hostilities. These conditions could keep prices roughly range-bound from here without any further significant developments.
The weakness in oil prices over the past few weeks is largely driven by signs of softening U.S. demand, together with rising crude oil and fuel inventories. U.S. crude and fuel inventories rose last week.
However, risks remain for shipments out of the Strait of Hormuz. Yesterday, Iran’s military said four oil tankers had been hit.

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 forecast: SPX struggles for direction ahead of PPI data
U.S. stocks are struggling for direction on Friday as investors continue to weigh up the fallout from Nvidia’s leadership change, rising Treasury yields and the upcoming U.S. producer price inflation data.
DAX Outlook: 27,000 Rejection Puts Key Support in Focus
The DAX faces a critical test after failing to sustain its breakout above 27,000. Opening weakness puts the 26,663 support zone in focus, while the broader uptrend remains intact. US producer inflation, European GDP data and Fed speakers could drive volatility throughout the session. Meanwhile, NVIDIA's reported leadership shake-up and a Microsoft service disruption add uncertainty to technology stocks.
DAX Reaches 27,000 While Markets Watch Anthropic IPO
The DAX has pushed above the psychologically important 27,000 level as investors continue to reward strong earnings, improving industrial demand and renewed confidence in AI-related investment themes. Results from Siemens and Allianz, combined with growing anticipation surrounding the upcoming Anthropic IPO, are helping sustain risk appetite across European markets. The focus now shifts to whether earnings can continue supporting valuations as the index trades in record territory.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.