



Dow Jones Analysis: DJIA faces renewed bearish bias amid rising tensions
It has been a difficult session for the Dow Jones index, as price action shows a decline of more than 1.00%, marking a new short-term bearish bias. The selling pressure emerging in the index is driven by weakening confidence in risk assets following renewed tensions between Iran and the United States.
Share this:
It has been a difficult session for the Dow Jones index, as price action shows a decline of more than 1.00%, marking a new short-term bearish bias. The selling pressure emerging in the index is driven by weakening confidence in risk assets following renewed tensions between Iran and the United States, as well as the persistence of elevated interest rates from the Federal Reserve. Both factors have prevented stable demand from forming, which could lead to more sustained selling pressure in the coming sessions.


Are peace talks failing?
Nearly one month into the Middle East conflict, there have been attempts by the United States to promote a ceasefire aimed at stabilizing the region and reducing global risk perception. However, during today’s session, Iran rejected the proposal, stating it would not negotiate under pressure and that any agreement must be made under its own terms.
This highlights the lack of progress in negotiations and the absence of clear signs of de-escalation in the short term.
This situation has led to a renewed increase in oil prices, with WTI crude approaching the $95 level. It has also negatively impacted market confidence, as reflected in the Fear and Greed Index, which has dropped to around 18 points, remaining firmly in “extreme fear” territory.

Source: CNN
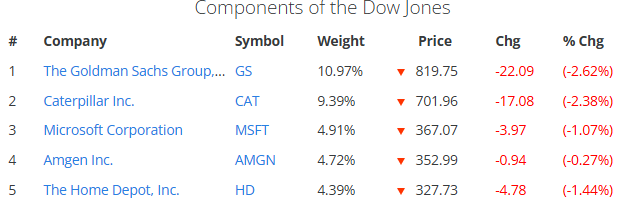
This deterioration in sentiment is also visible in the performance of the main Dow Jones components. In today’s session, the top five stocks are all in negative territory: Goldman Sachs (-2.62%), Caterpillar (-2.38%), Microsoft (-1.07%), Amgen (-0.27%), and Home Depot (-1.44%), highlighting broad-based weakness across the equity market.
Source: Slickcharts
In this environment, rising risk perception has weakened appetite for equities, reducing demand for U.S. stocks. Capital may be rotating toward safer assets, and as long as the conflict persists without resolution, this dynamic could continue to weigh on confidence and reinforce downside pressure on the Dow Jones.
The central bank remains strict
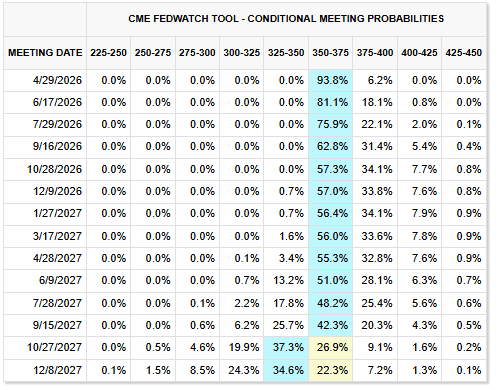
Another key factor is the stance of the Federal Reserve following its latest policy decision. The current outlook reinforces a no-change scenario, with a high probability that rates will remain at 3.75% at least through September 2027, according to the CME Group.
Additionally, starting from July 2026, there is a growing probability that rates could increase toward 4.00%, reflecting a shift toward a more restrictive stance, partly driven by inflation risks linked to the Middle East conflict.
Source: CMEGROUP
This environment is negative for equities, as higher rates for longer tend to pressure consumption and corporate margins. It has also pushed up U.S. 10-year Treasury yields, which are now near 4.4%, levels not seen since July 2025.
This increases the attractiveness of fixed income and may reduce demand for equities. In this context, restrictive monetary policy could continue to weigh on the Dow Jones in the short term.
Dow Jones Technical Outlook
Source: StoneX, Tradingview
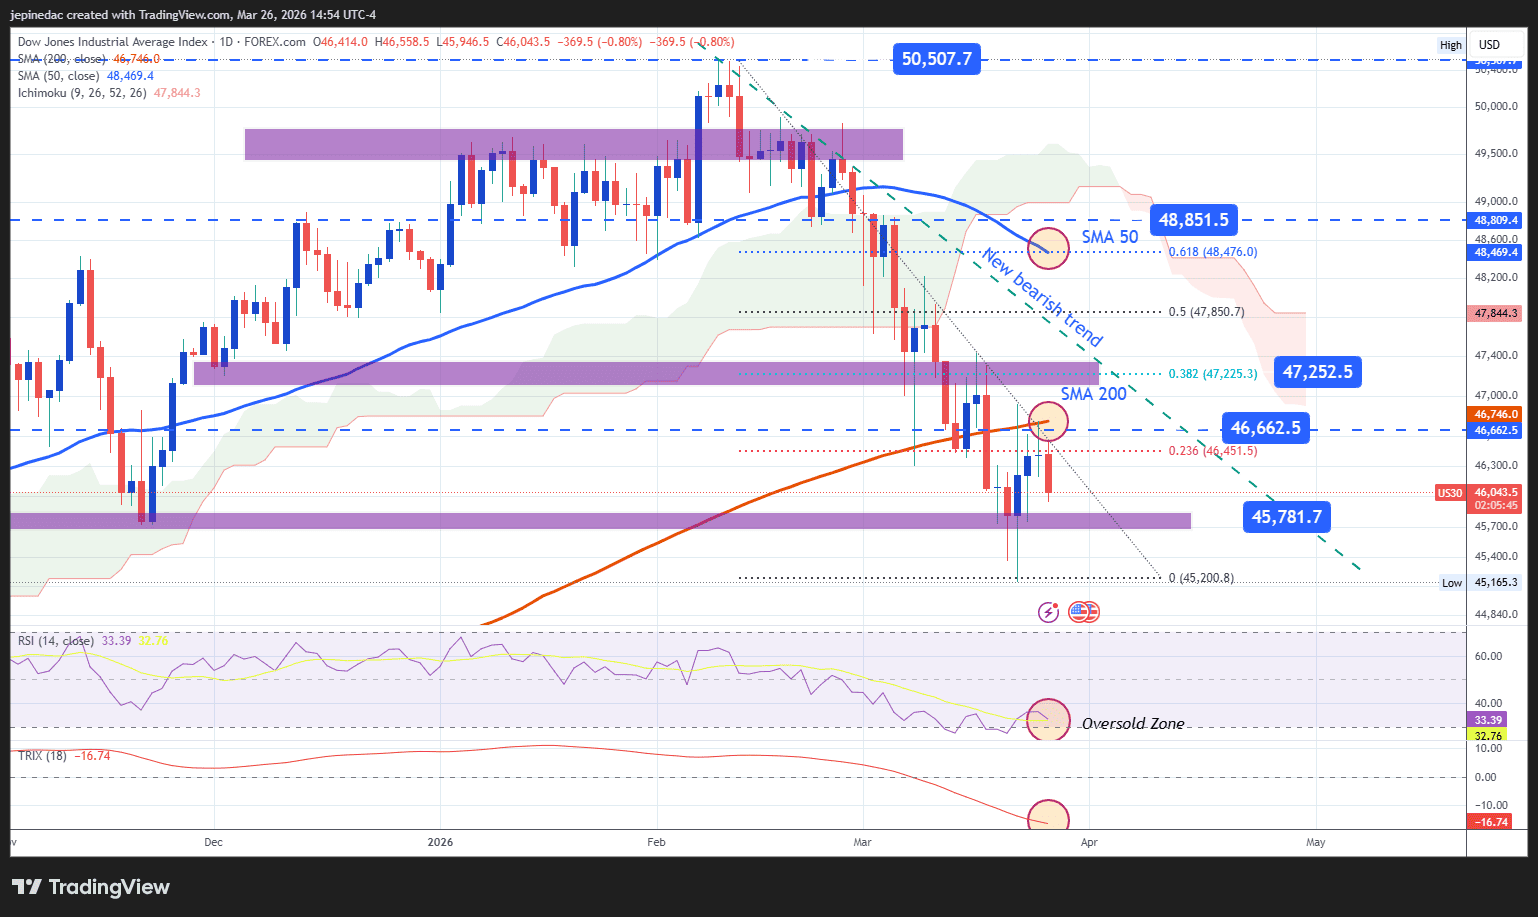
- Bearish trend gains traction: Recent price action in the Dow Jones has begun to form a downward trendline, which is becoming one of the most relevant structures on the chart. If selling pressure persists, this structure could strengthen and dominate price movements in the coming weeks. However, as price approaches key levels, there is still room for short-term corrective rebounds.
- RSI: The RSI remains below the 50 level, confirming the dominance of selling pressure over the past 14 sessions. However, it is approaching the oversold zone (30), which could signal potential technical rebounds as recent selling pressure becomes excessive.
- TRIX: The TRIX indicator continues to trade below the zero line, suggesting that long-term exponential moving average momentum remains bearish, and this bias could persist in price action over the coming weeks.
Key levels:
- 47,252 points – Key resistance: A zone of recent highs aligned with the newly formed downward trendline and the 38.2% Fibonacci retracement level. A move above this area could break the current bearish structure and trigger a more consistent bullish bias.
- 46,662 points – Near-term barrier: A neutrality zone aligned with the 200-period moving average. Price action around this level could reinforce short-term indecision and lead to the formation of a more consistent sideways range.
- 45,780 points – Key support: A level not seen since November 2025, acting as the main downside barrier. A break below this area could reinforce the current bearish bias and extend the downtrend as the dominant pattern in the short term.
Written by Julian Pineda, CFA, CMT – Market Analyst
Follow him on: @julianpineda25


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Why Crude Oil Slid While Middle East Tensions Kept Building
The crude oil pullback from monthly highs is running ahead of the headlines, as WTI and Brent ease while Middle East tensions stay unresolved.

Crude and dollar rebound as Trump says deal possible after the election
Donald Trump’s speech at the UN seems to have poured cold waters on any hopes of a deal. Crude oil, the US dollar and bond yields all bounced back from their lows, causing fresh pressure on foreign currencies, European indices and to a lesser degree precious metals.
USD/JPY and DXY Price Forecast: Bullish Rebound Faces Overbought Risks
Despite mounting geopolitical risks, crude oil prices have declined more than 10% from their monthly highs. Combined with overbought momentum readings on the DXY and dollar pairs, this increases the risk of a near-term reversal.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.