



Dow Jones Forecast: DJIA falls after hotter PPI & ahead of the FOMC rate decision
U.S. stocks are set for a weaker open as Treasury yields, PPI inflation and oil prices rise ahead of the Federal Reserve’s interest rate decision later today.
Share this:
US futures
Dow futures -0.40%, S&P futures -0.33% & Nasdaq futures -0.27%
In Europe
FTSE -0.65% & DAX -0.36%
- US stocks are falling as oil prices rise
- PPI jumps to 3.4% YoY, even ahead of the Iran war
- The Fed rate decision is due later, with no change in rates expected
- Oil rises to $105 after Israel hits energy infrastructure in Iran


Stocks drop as oil prices & PPI rise ahead of the Fed
U.S. stocks are set for a weaker open as Treasury yields, PPI inflaton and oil prices rise, ahead of the Federal Reserve’s interest rate decision later today.
Data released ahead of the meeting has dampened expectations for rate cuts this year. Producer price inflation (PPI) rose 3.4% year-on-year in February, well above the 2.9% expected, while monthly PPI increased 0.7%, more than double the 0.3% forecast. Notably, this hotter-than-expected factory gate inflation came even before the escalation of the Iran conflict.
The Federal Reserve is widely expected to leave rates unchanged at 3.5%–3.75%, shifting focus to updated growth and inflation projections and the dot plot.
With oil prices up around 40% since the start of the conflict, alongside rising wholesale inflation, the Fed may revise its inflation outlook higher. Markets are now pricing in just one rate cut this year, down from two, with the first move not expected until September at the earliest.
The key question is whether the Fed will validate this pricing. Given heightened uncertainty and the unpredictable duration of the conflict, policymakers may signal caution. While markets already expect a slightly more hawkish tone, a significantly hawkish shift could push yields higher and weigh on equities. Conversely, a measured and cautious stance could support stocks.
Treasury yields are advancing, lifting the USD and pushing Gold prices down more than 3%.
Corporate news
NVIDIA is up nearly 1% after reports it has received approval to sell its H200 chips in China, and is preparing a China-specific version of its next-generation AI chips.
Micron Technology is rising over 2% ahead of its fiscal Q2 earnings. The stock has rallied more than 60% this year, making it one of the top performers in the S&P 500.
Macy’s is up over 8% after beating expectations, reporting EPS of $1.67 on revenue of $7.64 billion, above forecasts of $1.53 and $7.62 billion, respectively.
Dow Jones forecast – technical analysis
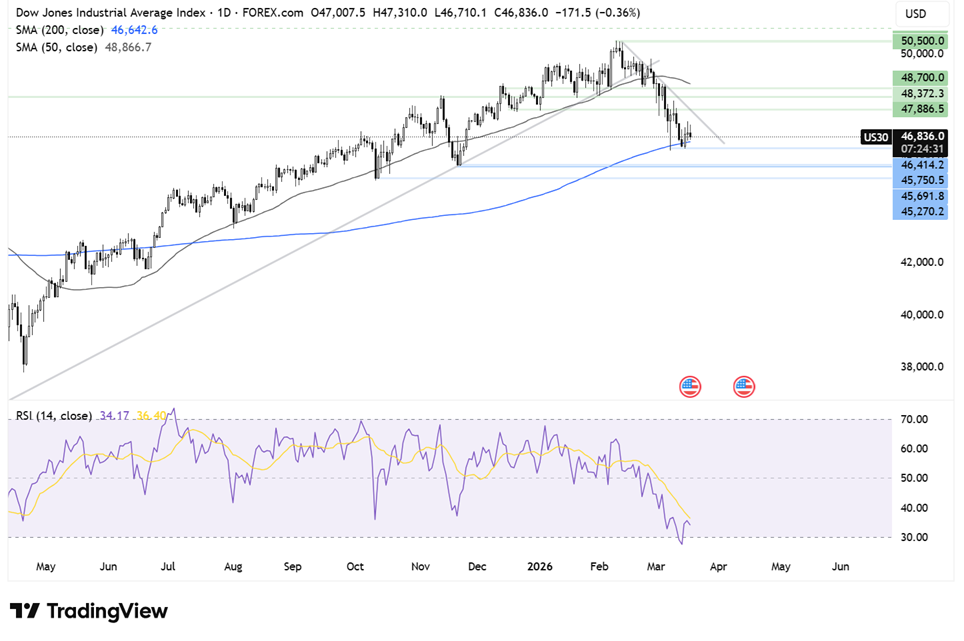
After running into resistance at the 50,500 record high, the Dow Jones pulled back, breaking below its 50-day SMA before finding support at the 200-day SMA around 46,600.
Prices have since recovered from this low, but the bearish bias remains intact, with the index still trading below its falling trendline and the RSI below 50.
Sellers will need to break below 46,600 to extend losses toward 45,700 (the November low) and 45,200 (the October low).
If the 200-day SMA support holds, buyers will look for a move above the falling trendline at 47,750, followed by resistance at 47,900.
FX markets – USD rises EUR/USD falls
The U.S. dollar is strengthening, paring earlier losses and tracking higher Treasury yields following stronger-than-expected PPI data and a rebound in oil prices.
EUR/USD is falling, pressured by USD strength despite data showing eurozone inflation rose to 1.9% YoY in February from 1.7%. Attention now turns to the ECB rate decision, where rates are expected to remain at 2%, with a continued emphasis on a data-dependent approach.
GBP/USD is also lower, weighed down by dollar strength and ahead of the Federal Reserve and Bank of England decisions. The BoE is expected to hold rates at 3.75%, but the pound remains vulnerable amid sticky inflation, weak growth, and strained public finances.
Oil rises to $105 as Iran’s oil energy infrastructure is hit
Oil prices are rising again after briefly easing, with Brent moving back above $100 a barrel to $105 amid renewed supply concerns.
Prices had dipped earlier after Iraq reached an agreement to resume exports via Turkey’s Ceyhan port, offering temporary relief. However, this was short-lived after reports that Iran’s largest gas processing facility was struck, reigniting supply fears.
With the Strait of Hormuz still effectively closed, oil production remains constrained as storage pressures build.
With no clear signs of de-escalation, oil markets remain highly headline-driven. The longer the disruption persists, the tighter supply conditions are likely to become, keeping upward pressure on energy prices.

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.

Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.

What Stretched 10-Year Yields Mean for Major Currency Pairs in Q4
U.S. 10-year Treasury yields are nearing a long-term resistance zone with overbought RSI readings, raising near-term pullback risk for the dollar.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.