
Dow Jones forecast: Stocks extend drop amid surging oil and elevated yields
The global equity markets remain under pressure and with oil surging higher again this week, we have even more reason to remain cautious. Already, the S&P and Nasdaq were running support from only a handful of hyperscalers and AI stocks. But even these indices have started to take notice of the deteriorating market breadth and global indices. Still, for me, the ongoing weakness is becoming more evident in the Dow and the small-cap Russell 2000 indices, and as such I will continuing watching these markets closely to provide a more accurate signal about the health of the stock markets.
Share this:
The global equity markets remain under pressure and with oil surging higher again this week, we have even more reason to remain cautious. Already, the S&P and Nasdaq were running support from only a handful of hyperscalers and AI stocks. But even these indices have started to take notice of the deteriorating market breadth and global indices. Still, for me, the ongoing weakness is becoming more evident in the Dow and the small-cap Russell 2000 indices, and as such I will continuing watching these markets closely to provide a more accurate signal about the health of the stock markets. Mounting economic and financial pressures are increasing the risks of a sharp correction, so our near-term Dow Jones forecast remains tilted to the downside.
Watch our analysis on Dow Jones forecast
Crude oil surge further fans inflation worries
Earlier this week, we saw oil prices fall sharply, and accordingly, the major indices were able to regains their poise and the likes of the Nasdaq and S&P 500 both hit new all-time highs. However, the gains for other global benchmarks were more measured as investors remained cautious. Their cautious stance paid off because oil then surged higher in the second half of Tuesday’s session, before consolidating yesterday and now continuing higher with another 3% rise. In the process, Brent oil has surged back above $100 a barrel.
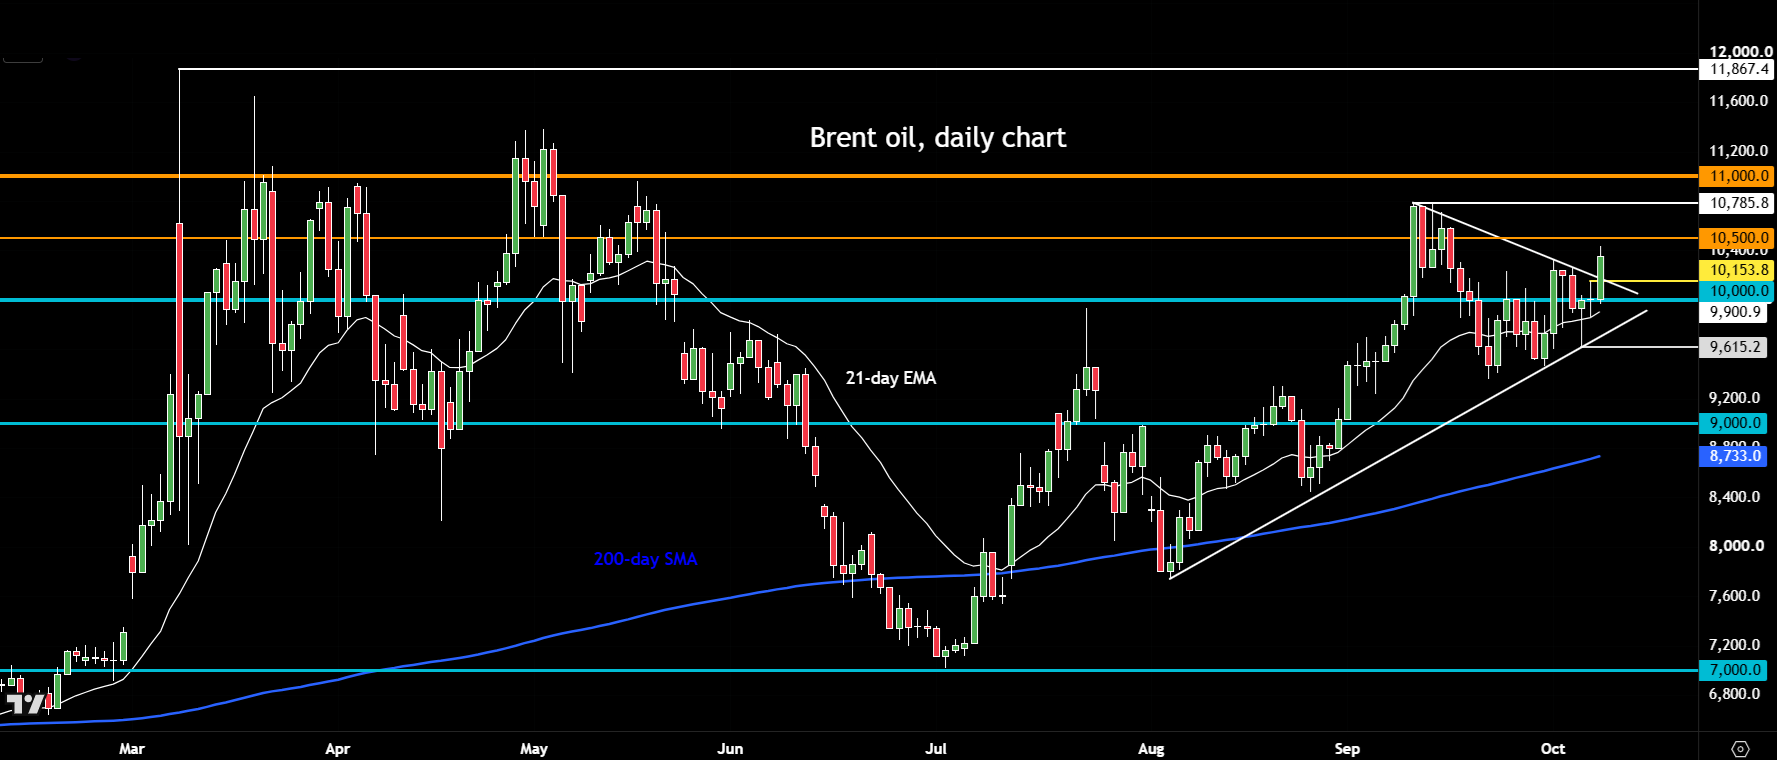
The renewed rise in oil prices is intensifying inflation concerns and adding to upward pressure on bond yields. With depleted inventories supporting the case for sustained replenishment demand, the long-term direction of oil prices will remain tilted to the upside. In the short-term, it would take some positive developments towards a potential US-Iran deal to bring some relief. However, judging by recent headlines, that seems unlikely and markets are now preparing for another potential US military action in Iran.
Bond markets remain under intense pressure
The rebound leaves oil applying renewed pressure to an already difficult inflation backdrop. Government bond yields are rising across markets as investors price in the possibility that interest rates could increase further. Higher crude prices are partly behind those concerns. Therefore, the oil recovery matters beyond the energy market itself, with the rise in yields also helping to undermine risk appetite.
With Treasury yields surging, mortgage rates climbing and expectations shifting towards further interest rate hikes, the prospect of a deeper equity market correction is becoming increasingly difficult to dismiss. With yields looking increasingly attractive, at some point investors will be tempted to move into bonds and away from equities, so long as they don’t think the government will default on its debt obligations. This could keep the stock market under some real pressure until valuations become attractive again as prices fall.
For now, equity investing is becoming challenging. The ongoing gains in bond yields are beginning to feed through to the real economy. The average interest rate on a 30-year US mortgage has recently climbed to its highest level since November 2023, as the 10-year Treasury yield reached its highest level since early 2000s. That trend is unlikely to reverse without a fundamental trigger.
With commodity prices surging. This is reinforcing concerns that inflation could prove more persistent than previously expected, just as borrowing costs are rising. For equity markets, the combination of higher yields, tighter financial conditions and mounting inflation risks presents an increasingly challenging backdrop.
Dow Technical analysis: Index eyes 50K
Looking at the Dow chart, it is difficult to remain bullish given the recent price action, with the index forming lower lows and lower highs. The market has been under pressure since early August, when the latest upswing failed to generate fresh buying momentum around record levels.
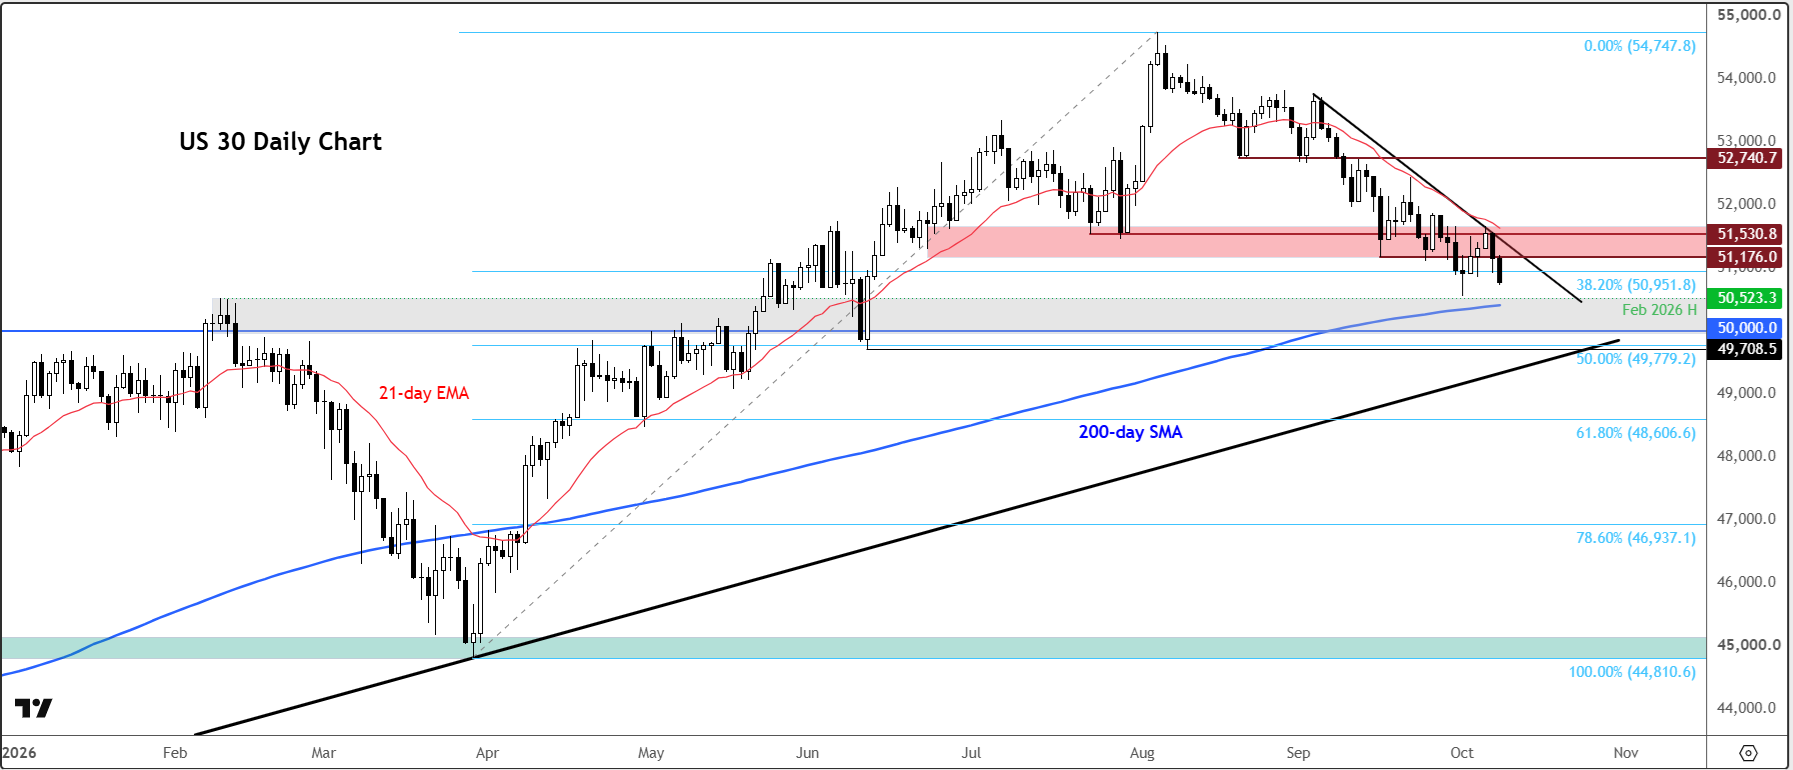
More recently, Dow Jones has fallen below its 21-day exponential moving average and has remained beneath it, suggesting that the bulls have lost control of the near-term price action. Several lower highs have subsequently formed, establishing a bearish trend line. The index has also broken a number of support levels, most notably around 51,500, which has since turned into resistance.
For me, the Dow needs to reclaim 51,500 to revive the bullish case. Until that happens, the path of least resistance remains to the downside, with the index potentially targeting the earlier-year low around 50,523.
Below that, the 200-day moving average comes into focus, followed by the psychologically important 50,000 level. Further down, the longer-term bullish trend line connecting the lows from April 2025 and March 2026 currently comes in around 49,000, although its exact position will depend on how quickly the market falls, should the decline continue.
The 50% Fibonacci retracement of the entire move from the March low to the August peak is also sitting just below 50,000, around 49,780. These are therefore the key short-term downside levels to watch if the Dow remains under pressure.

Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Dow Jones forecast: Stocks extend drop amid surging oil and elevated yields
The global equity markets remain under pressure and with oil surging higher again this week, we have even more reason to remain cautious. Already, the S&P and Nasdaq were running support from only a handful of hyperscalers and AI stocks. But even these indices have started to take notice of the deteriorating market breadth and global indices. Still, for me, the ongoing weakness is becoming more evident in the Dow and the small-cap Russell 2000 indices, and as such I will continuing watching these markets closely to provide a more accurate signal about the health of the stock markets.
Nasdaq 100 Forecast: NDX falls as oil jumps 5%, Treasury yields rise
U.S. stocks are set to open lower, with the Dow Jones leading the move south as U.S. oil prices jump 5% and Treasury yields rise, stoking inflation concerns.

BTC/USD Outlook: Bitcoin defies macro headwinds as volatility evaporates
Bitcoin has weathered the surge in the US dollar and Treasury yields remarkably well, but realised volatility has fallen towards historical lows. A study of nearly a decade of price history suggests larger swings may be coming.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.