



ECB Meeting Preview More Stimulus in December
The ECB is not expected to make any immediate to changes to monetary policy this week, although the Euro has been skidding lower across the week in anticipation of a dovish meeting.
Share this:
When:
Thursday 29th October, Decision announced 12:45 GMT, with a press conference 45 minutes later.
Thursday 29th October, Decision announced 12:45 GMT, with a press conference 45 minutes later.
The ECB is not expected to make any immediate to changes to monetary policy this week, with both the deposit and main refinancing rates expected to remain unchanged. The Euro has been skidding lower across the week in anticipation of a dovish meeting
Deteriorating scene
The picture has deteriorated since the last ECB meeting in September. Covid cases have continued to surge with France recording over 33,000 new daily infections and Germany a record 11,000. Both key economies in the eurozone are on the brink of announcing national lockdown measures after localised restrictions have failed to stem the spread of a second wave covid. Business activity in the bloc, is according to the latest PMI data, now in contraction territory, whilst the service sector has contracted further.
The picture has deteriorated since the last ECB meeting in September. Covid cases have continued to surge with France recording over 33,000 new daily infections and Germany a record 11,000. Both key economies in the eurozone are on the brink of announcing national lockdown measures after localised restrictions have failed to stem the spread of a second wave covid. Business activity in the bloc, is according to the latest PMI data, now in contraction territory, whilst the service sector has contracted further.
No change expected (yet)
The broad expectation that this week is too soon for the ECB to act. Instead the ECB are expected to open the door to additional stimulus in December’s meeting. The central bank are expected to highlight the very significant downside risk that the second wave poses and that policy will need to remain accommodative in order to cushion the bloc’s economy from this risk. Christine Lagarde could well then indicate to the market that the ECB is prepared to act as soon as the next meeting. Remember December’s meeting will also see the updated staff projections released. The ECB could well look to expand the PEPP beyond its current end date of mid-2021 and add a further €500 billion.
However, it is worth keeping in mind that new lockdowns by the Euro’s biggest economies are boosting that chances of a pre-emptive stimulus boost. Whilst there is no rush to act immediately is could certainly send a strong message.
Euro strength & inflation
Well it was never really an issue for Christine Lagarde anyway. Whilst Euro strength had been a focus in previous month for some policy maker we expect it to slip off agenda this month, as the Euro has lost ground versus the US Dollar.
Inflation and the lack thereof is likely to be a more pressing concern for the ECB. The ECB’s September projections indicated a mild downtrend to inflation. There is a good chance that the inflation forecast will need to be downwardly revised again in December adding yet more pressure on the central bank to act.
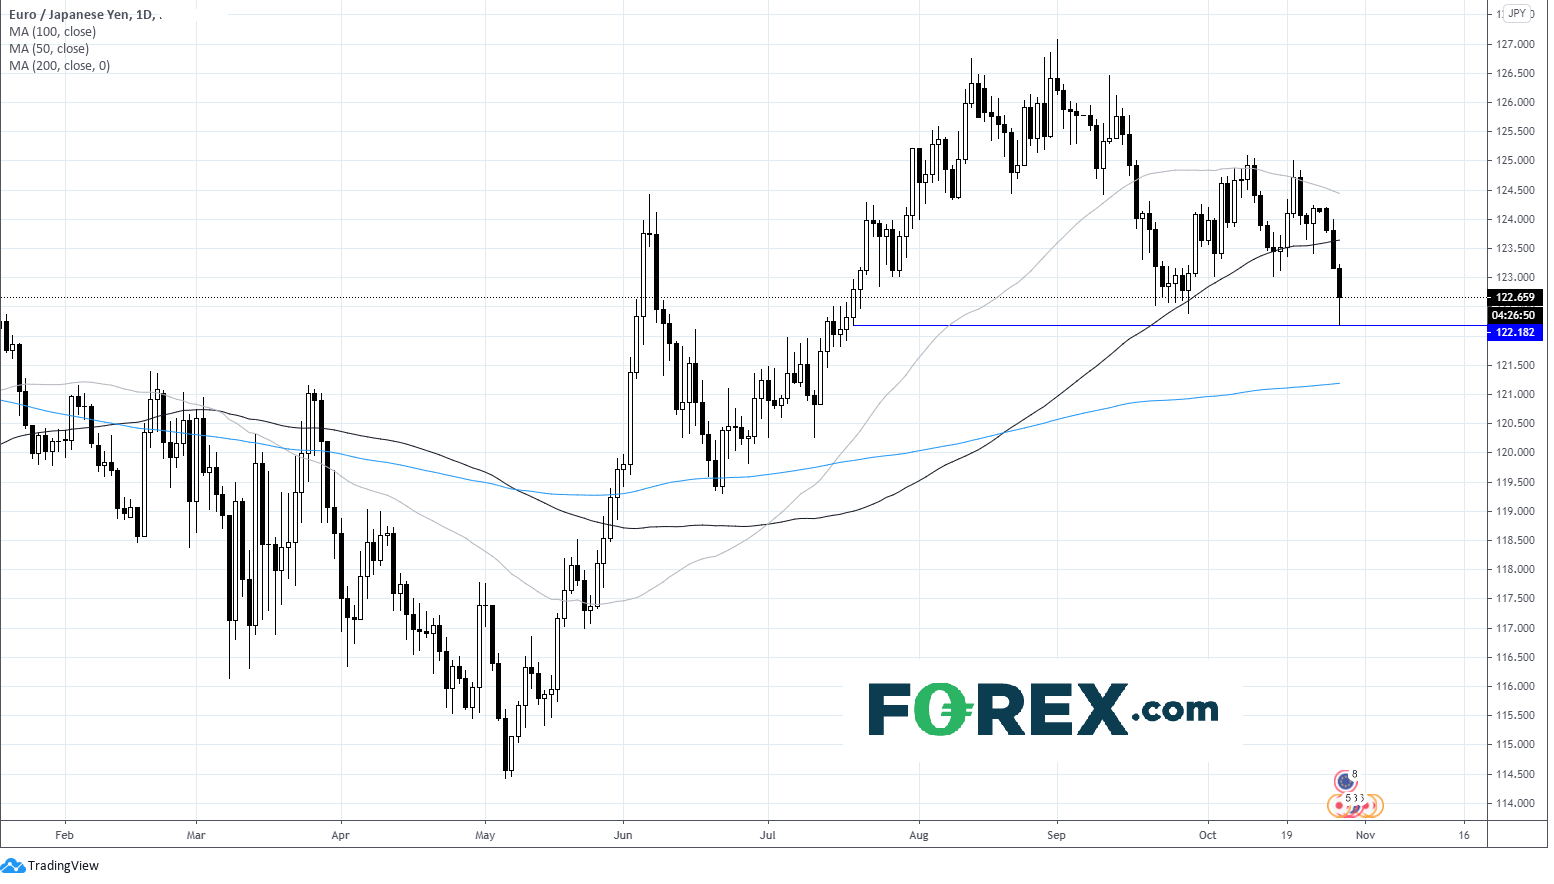
EUR/JPY hits 3 month low
The market will be disappointed if it doesn’t get a clear hint of more action coming. The Euro has been under significant pressure this week ahead of the ECB meeting. Meanwhile the safe haven Japanese Yen has been in favour in risk off trading, with the pair striking a multi month low of 122.18.
The pair trades below 50 & 100 sma on daily chart but remains above 200 which offers support at 121.17
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.

EUR/USD Update: Will Fed Expectations Keep Pressure on the Euro?
The week continues to present challenges for the euro's short-term strength. This is reflected in the recent performance of EUR/USD, which has declined by nearly 0.6% over the last three trading sessions
EUR/USD Forecast: Euro Extends Losses Ahead of Fed Rate Decision
The euro has started to face a more challenging period in the short term. The EUR/USD pair has already declined by nearly 0.81% over the last four trading sessions, a move that has begun to reinforce a meaningful bearish bias in favor of the U.S. dollar.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.