



EU stocks remain lower after hot Eurozone CPI
Core inflation rose to a fresh record high of 5.6%...
Share this:

- DAX and other indices off earlier lows, but pressure remains
- Eurozone core CPI hits fresh record high to further boost hawkish ECB bets
- More rate hikes and longer contractionary monetary policy should be bad for stocks
Following the release of hotter-than-expected inflation figures from Germany and Spain earlier this week, the market had already revised its expectations higher about the Eurozone CPI as a whole, which explains why the major Eurozone indices had already been struggling this week.
Lo and behold, Eurozone CPI came in hotter than expected this morning, but as expectations were already boosted by those CPI figures from Germany and Spain, the euro hardly reacted. Stock market investors found no reason to cheer the data by bidding up the indices, which meant that the likes of the DAX showed an immediate negative reaction to the numbers, before bouncing off their lows by mid-morning session.
Sentiment was actually already downbeat before the CPI data was released with the major European stock indices falling sharply at the open. The DAX was already down over 1% shortly after the bell and similar losses were seen for other eurozone indices, and for US index futures. It was a weak handover from Asia where Chinese equities gave back a chunk of their impressive gains made the day before on the back of strong PMI data.
How hot was Eurozone CPI and what will it mean for ECB?
Well, the headline inflation figure actually decreased to 8.5% from 8.6% year-over-year rate in the previous month. Even so, this was not as big a drop as 8.3% expected. More to the point, core inflation rose to a fresh record high of 5.6%, in a surprise move. The latter was expected to have risen to 5.3%, from last month’s 5.2% reading, which was also revised up to 5.3%, as it turned out. This should mean that the European Central Bank has no reason to stop hiking. For stock markets, this is bad news, as higher interest rates for longer, in theory anyway, should weigh on economic activity.
There’s still some hope that inflation will weaken more aggressively moving forward, though. Above all, due to base effects. Indeed, the March CPI should be much weaker as the big jump from March 2022 falls out of the year-on-year comparison. But this doesn’t mean inflation will quickly return to target as food and services inflation remain rather sticky.
It is not all about Eurozone CPI
Today’s stronger CPI data from the Eurozone is certainly not good news for those hoping that inflation would drop quickly.
Outside of Europe, we also had signs of sticky inflation in the US last week, with the Fed’s favourite measure of inflation – the Core PCE Price Index – coming in higher than anticipated. That – as well as some other above-forecast economic indicators – helped to raise market’s expectations about US interest rates. As a result, US 10-year Treasury yields crossed 4.00% on Wednesday for the first time since November. They have gone a bit further higher today.
Rising bond yields have come back to haunt investors on Wall Street.
Having outperformed Wall Street, Europe’s top indices were always going to stop rising at some point without the participation of US markets. But now, the bulls have even more reason (hot Eurozone CPI) to be cautious.
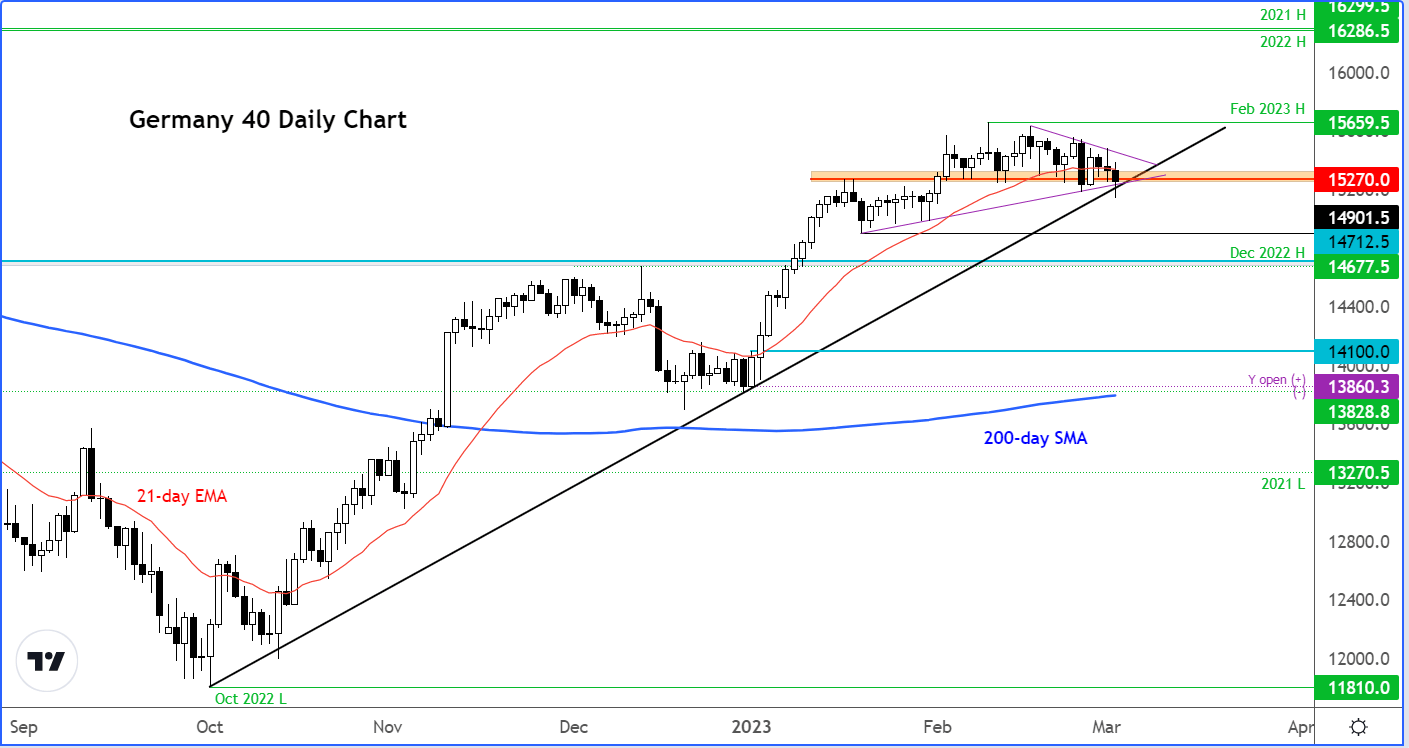
Will DAX break bull trend?
Following the CPI release, the DAX peaked below the bullish trend line that has been in place since the market bottomed in October (black line on the chart), before bouncing off the lows. The German index had also fallen below the support trend of its triangle pattern (purple line), and below support at 15270.
Given that there has not been an immediate follow-through to the downside, it may be best to wait how the market performs later when US investors come to the fray.
So, it is all about whether the index will now hold below those levels on a closing basis, with 15270 being key. If it does, then it would confirm the bearish reversal. Should that happen, the DAX could drop towards 15K next, possibly much lower in the days ahead.
However, if the bulls step back in and reclaim the above-mentioned levels on a closing basis, then this would keep the bull trend intact – at least for a little longer.
All told, the risks appear to be skewed to the downside for the DAX, both from a technical point of view and because of macro reasons.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

AUD/USD outlook: Aussie slips despite hawkish RBA ahead of key data
The AUD/USD was unable to benefit from the Reserve Bank of Australia’s 25-basis-point rate hike overnight. The RBA lifted the cash rate to 4.60%, in line with expectations. However, the Australian dollar weakened following the decision, with much of the Bank’s hawkish stance seemingly priced in ahead of the announcement. The US dollar has also remained largely supported following the recent turmoil in the bond markets.

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.


Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.