



EUR/USD outlook: Dollar strength may have further to run as Warsh reinforces the Fed’s message
The EUR/USD outlook remains modestly bearish, even if the US dollar has eased off its earlier highs following Kevin Warsh’s speech a few moments ago where he offered no major surprises. Investors will likely continue to favour the US dollar as investors digest a Federal Reserve that appears determined to keep inflation under control, even as financial markets continue to debate the timing of the next policy move.
Share this:
- EUR/USD outlook: The dollar remains underpinned as the Federal Reserve continues to prioritise inflation over GDP
- Kevin Warsh reinforces the Fed’s hawkish stance at Sintra
- While Eurozone inflation is easing, the ECB is unlikely to signal an imminent shift towards rate cuts
The EUR/USD outlook remains modestly bearish, even if the US dollar has eased off its earlier highs following Kevin Warsh’s speech a few moments ago where he offered no major surprises. Investors will likely continue to favour the US dollar as investors digest a Federal Reserve that appears determined to keep inflation under control, even as financial markets continue to debate the timing of the next policy move. Since last month’s FOMC meeting, the greenback has held onto most of its gains, suggesting investors remain comfortable with the Fed’s new hawkish rhetoric. But now it is up to US data to keep those hawkish Fed bets alive, making tomorrow’s NFP data a major market event.
Warsh refuses to soften the Fed’s inflation stance
Attention was on Federal Reserve Chair Kevin Warsh, whose remarks at the ECB’s annual Sintra conference could once again set the tone for currency markets. He once again refused to offer forward guidance and said they are “in price stability business”.
Given the lack of detailed forward guidance from the Fed since the June meeting, every public appearance from policymakers is carrying greater weight than usual. Warsh made an immediate impression at his first FOMC meeting, where markets interpreted both the streamlined policy statement and the updated Dot Plot as firmly hawkish. His emphasis on restoring price stability after years of inflation overshoots helped propel the dollar higher, and little has changed since then to justify a more cautious tone. And judging by his latest remarks, we haven’t seen any changes.
If anything, incoming US data have strengthened the Fed’s hand. Core PCE inflation remains elevated at 3.4% year-on-year, while another solid labour market report last month reinforced the view that the economy continues to withstand tighter financial conditions remarkably well.
Against that backdrop, it is hardly surprising to see Warsh make any attempts to dampen market expectations for further tightening. Markets continue to assign meaningful odds of a move as early as September.
US data could reinforce dollar momentum
Warsh’s speech is not the only event capable of moving markets. The latest ISM manufacturing survey, due for release shortly, will also provide investors with fresh insight into the health of the US economy, before the focus turns to the NFP data on Thursday. Another strong payroll reading then would reinforce confidence that businesses continue to hire despite elevated interest rates. Likewise, if manufacturing activity remains in expansion territory, it would add further evidence that economic momentum is proving more resilient than many had expected earlier this year.
ECB likely to maintain a hawkish tone despite easing inflation
While attention is firmly focused on the Fed, the ECB also faces an increasingly delicate balancing act.
Today’s inflation figures have provided some welcome relief. Headline Eurozone inflation slowed to 2.8% in June from 3.2%, while core inflation also eased. Lower energy prices continue to feed through into consumer prices, and unless oil prices stage another sharp rally, energy inflation is likely to remain a disinflationary force over the coming months.
However, policymakers are unlikely to declare victory just yet. The ECB has consistently argued that inflation risks remain elevated, particularly given concerns around wage growth and underlying price pressures. Even though markets are becoming increasingly confident that the insurance hike was a just a one off, officials appear reluctant to significantly alter their messaging while uncertainty surrounding global energy markets and geopolitical developments persists. Still, President Christine Lagarde has already hinted that the central bank no longer needs to be as aggressive as it was during the height of the inflation surge.
EUR/USD outlook: Bears remain in control
From a technical analysis point of view, the EUR/USD outlook remains bearish, particularly as the US-EU policy divergence still favours the dollar.
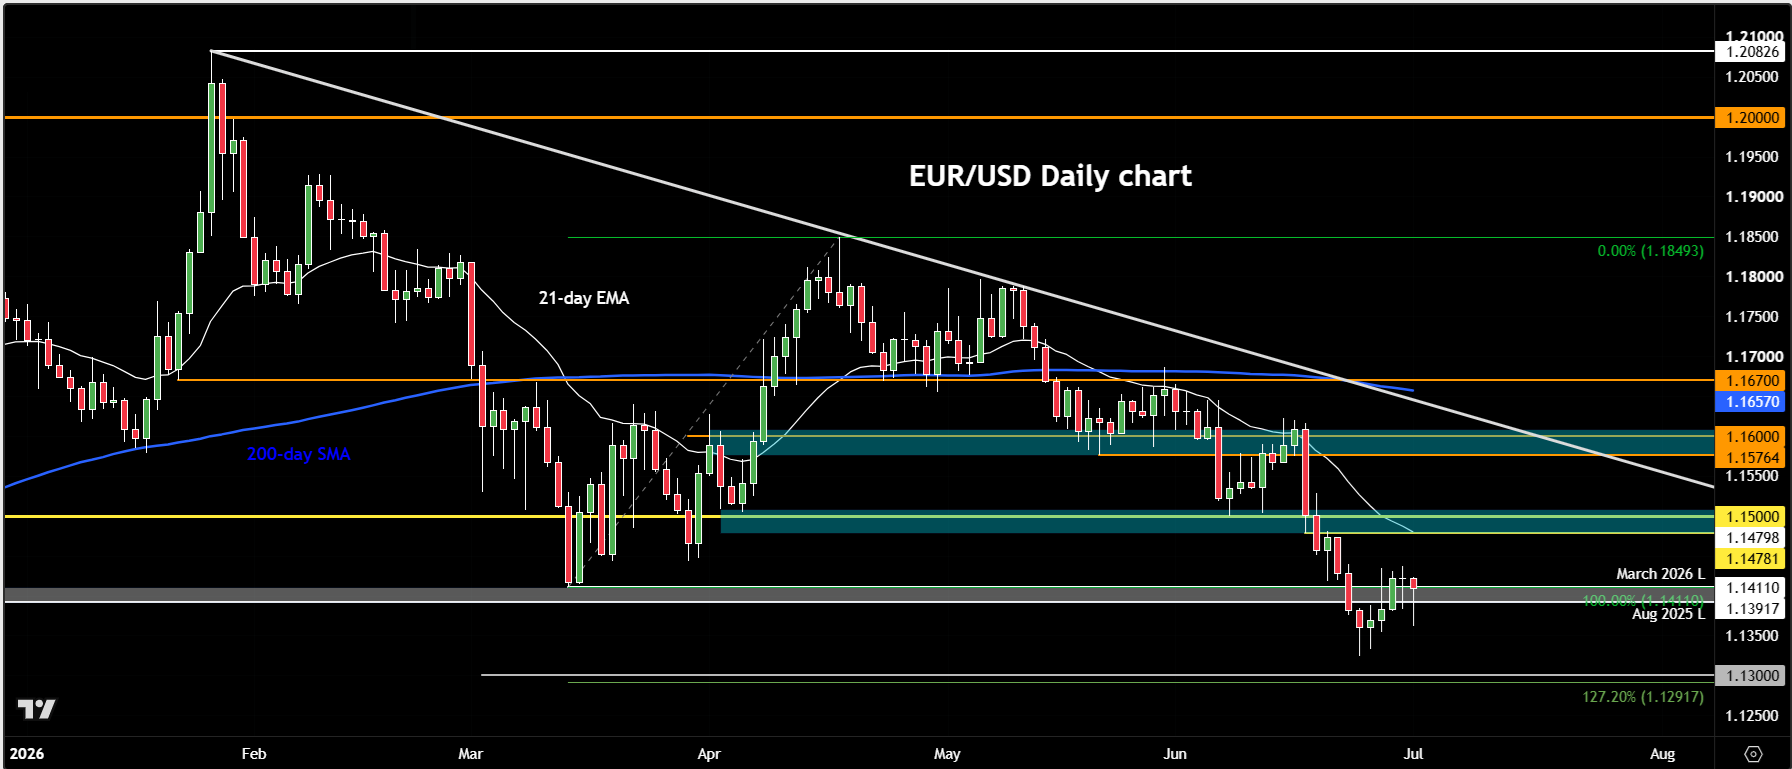
The EUR/USD remains vulnerable while trading below recent resistance levels, and renewed buying of the greenback could see the pair potentially drop to retest the 1.1300 handle.
Ok the upside, there is a strong resistance band between 1.1410 to 1.1470 area, then there is the psychological 1.15 handle above that. The bearish trend line comes in around the 1.1600 area.
Overall, the EUR/USD outlook remains modestly bearish in the near term. As long as the Fed continues to emphasise price stability and the US economy shows few signs of slowing materially, rallies in the EUR/USD may continue to attract sellers rather than mark the beginning of a sustained recovery.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
What Stretched 10-Year Yields Mean for Major Currency Pairs in Q4
U.S. 10-year Treasury yields are nearing a long-term resistance zone with overbought RSI readings, raising near-term pullback risk for the dollar.

USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.


USD/MXN Analysis: Is Super Peso Starting to Fade?
Over recent trading sessions, the Mexican peso has continued to show signs of weakness against the U.S. dollar. This can already be seen in USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting sustained buying pressure in favor of the dollar in the short term.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.