



European Open: EUR/GBP is Coiling Ahead of Key Inflation Data
With a host of inflation report scheduled for the Eurozone and UK shortly, EUR/GBP is on the radar for intraday traders.
Share this:


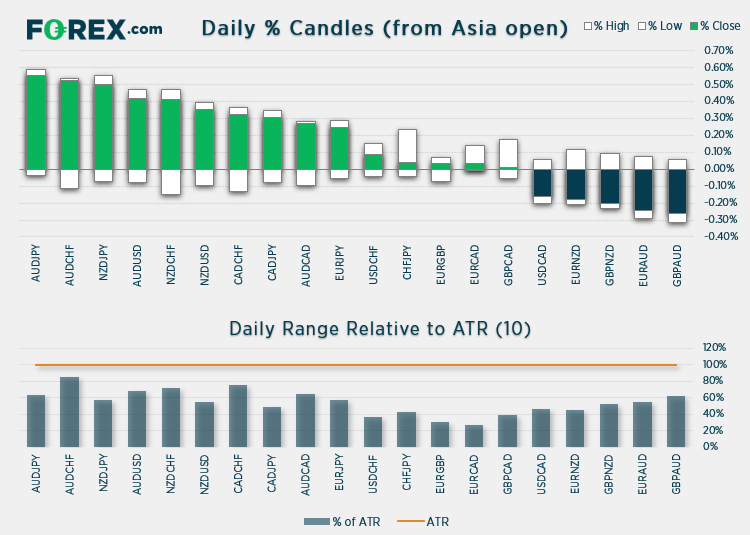
Asian Indices:
- Australia's ASX 200 index rose by 47.5 points (0.64%) and currently trades at 7,422.40
- Japan's Nikkei 225 index has risen by 101 points (0.35%) and currently trades at 29,317.44
- Hong Kong's Hang Seng index has risen by 338.75 points (1.31%) and currently trades at 26,125.96
UK and Europe:
- UK's FTSE 100 futures are currently up 6 points (0.08%), the cash market is currently estimated to open at 7,223.53
- Euro STOXX 50 futures are currently down -3.5 points (-0.08%), the cash market is currently estimated to open at 4,163.33
- Germany's DAX futures are currently down -9 points (-0.06%), the cash market is currently estimated to open at 15,506.83
US Futures:
- DJI futures are currently up 198.7 points (0.56%)
- S&P 500 futures are currently down -15.25 points (-0.1%)
- Nasdaq 100 futures are currently down -1.5 points (-0.03%)
Indices
Asian equity markets sustained the positive vibe from Wall Street as traders remained optimistic about the global recovery. Which is in stark contrast to the recent selloff which was caused by concerns of stagflation.
Japan’s exports slumped to a 7-month low of 13% y/y in September, down from 26.2% in August and its peak of 49.6% in May. Exports to the US fell -3% although rose to 1.3% for Asian, 10.3% of which was to China. With imports costs rising thanks to the spike in oil prices and weaker yen, it is metric which could weigh on BOJ’s outlook when they revise their inflation forecasts later this month. The Nikkei 225 gave back early gains and now trades just 01% higher for the session.
The FTSE 100 is coiling up near its recent highs on the four-hour chart. With sentiment remaining positive for equities overall we’re hopeful to see an upside break. Key support levels for bulls to defend include 7180 and 7160.
FTSE 350: Market Internals

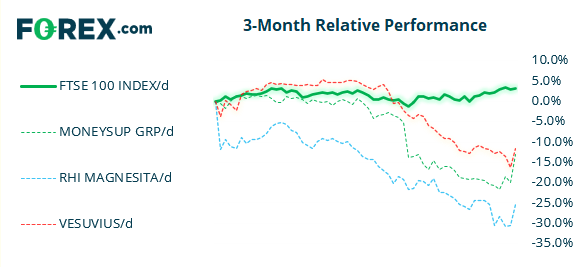
FTSE 350: 4136.42 (0.19%) 19 October 2021
- 217 (61.82%) stocks advanced and 116 (33.05%) declined
- 9 stocks rose to a new 52-week high, 3 fell to new lows
- 60.11% of stocks closed above their 200-day average
- 31.91% of stocks closed above their 50-day average
- 20.51% of stocks closed above their 20-day average
Outperformers:
- + 8.9%-Moneysupermarket.Com Group PLC(MONY.L)
- + 7.7%-RHI Magnesita NV(RHIM.VI)
- + 5.8%-Vesuvius PLC(VSVS.L)
Underperformers:
- -5.8%-International Consolidated Airlines Group SA(ICAG.L)
- -5.6%-TUI AG(TUIT.L)
- -5.4%-Harbour Energy PLC(HBR.L)
Forex:
As my colleague Joe Perry pointed out, Wednesday really is inflation day – with consumer and producer price reports being released across Europe, Africa and North America. UK CPI kicks it all off at 07:00 BST which puts GBP pairs into focus for news traders. Following hawkish comments from BOE Governor Andrew Bailer, traders have been pricing in a November hike. And that means any disappointment in today’s figured could see the pound under pressure.
CPI is expected to have dipped to 0.4% in September from 0.7%, remained steady at 3.2% y/y and for Core CPI to have slipping to 3% from 3.1% prior. Conversely, should we see some punchy numbers today it will only exacerbate calls for an early rate hike and support GBP.
And the relative performance between European an UK’s CPI reports places EUR/GBP firmly into focus. EUR/GBP has rallied over 300 pips since September low from the 200-day eMA. It closed above the August high on Friday, then produced a bullish engulfing candle yesterday and closed near the highs.
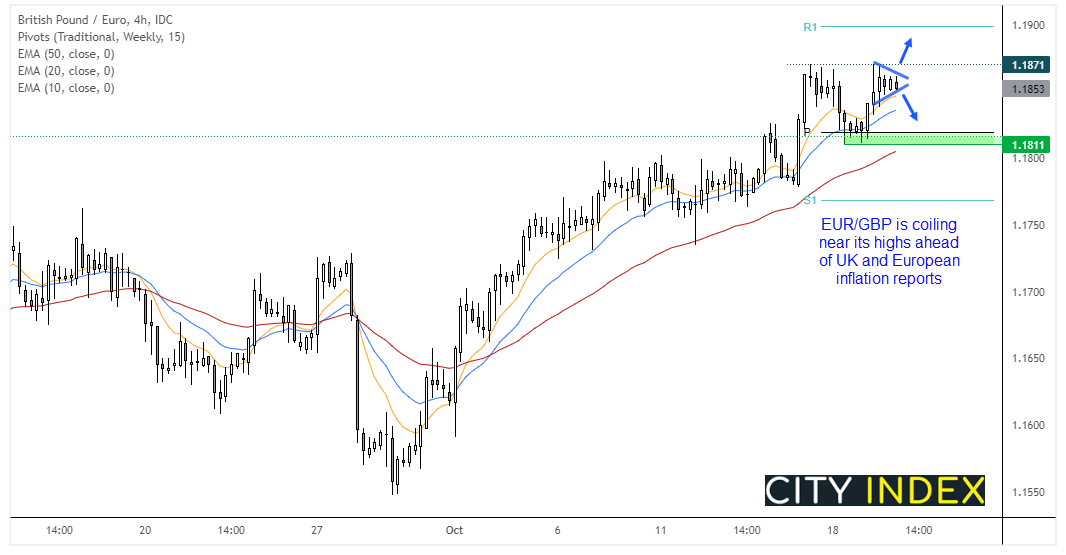

The four-hour chart has bounced its way along the 20-bar eMA and is now coiling within a tight range ahead of these inflation reports. Today we are simply waiting to see if momentum breaks the cross to new highs or break lower from the small consolidation as part of a minor countertrend move. If it moves lower, we could then seek bullish setups above 1.1800 near the recent swing low and weekly pivot point, as the trend remains bullish overall.
Commodities:
Copper futures dipped to a 4-day low which confirmed two bearish pinbars on the daily chart. It’s holding above the July high but it is apparent a cooling-off period is required after last week’s strong rally. For now, we remain bullish above 4.50 and await further evidence is current retracement has neared completion.
View today’s video: Silver Shines as Bulls Relinquish Control
Up Next (Times in BST)
How to trade with City Index
You can trade easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.
Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.