



FTSE 100 analysis: IDS shares rise as it appoints new CEO – Top UK stocks
Markets are digesting a flurry of results and updates out from the likes of easyJet, Dunelm, Babcock, IDS, Vistry Group, Alphawave and Premier Foods.
Share this:

FTSE 100 rises
The FTSE 100 is up 0.2% in early trade this morning, with the index at a one-month high.
Markets are digesting a flurry of earnings out this morning, with the economic calendar light today. The headline event is US initial jobless claims out this afternoon, alongside the Philadelphia Fed Manufacturing index and existing US home sales.
FTSE 100 analysis: Where next for the UK 100?
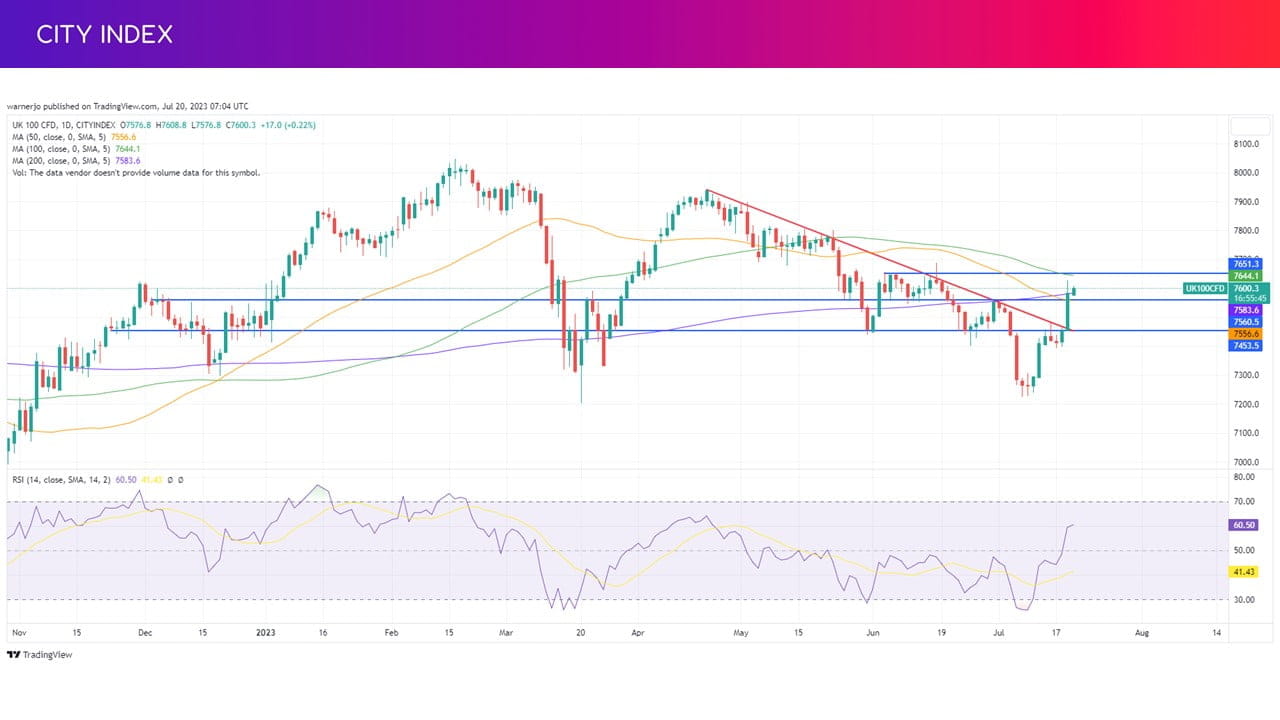
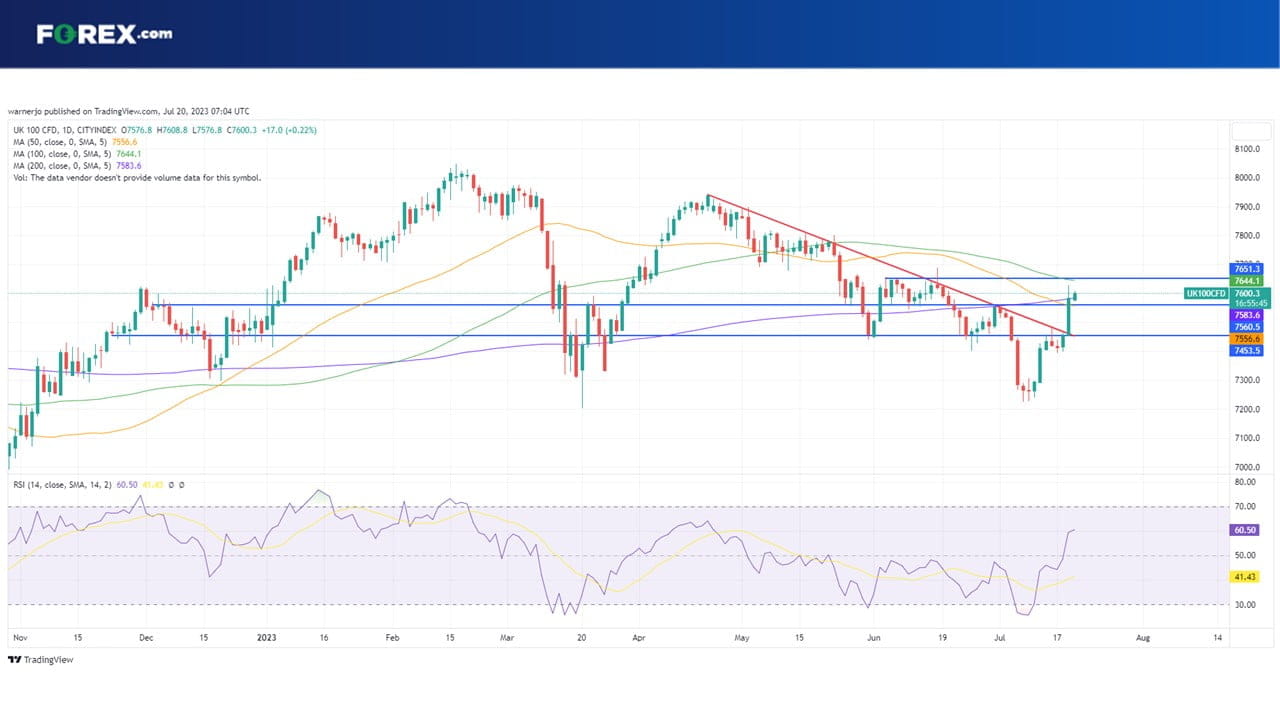
The UK 100, which tracks the FTSE 100, has soared over the past two weeks, having surged above the falling trendline that had provided a reliable ceiling over recent months and blowing past the 50-day moving average yesterday.
The next upside target is now 7,650, which was the ceiling we saw in the first half of June and in-line with the 100-day moving average. A sustained move above here could open the door to a larger jump to over 7,800! The RSI is in bullish territory and suggests there is further room for the index to rise, and the bullish candle we saw yesterday should also provide some confidence.
Investors will hope that the 7,550 will provide some support if it comes under renewed pressure, although there is a risk it could fall back toward 7,450 if it is severe.
Top UK stock news
International Distribution Systems is up 1.2% after it announced Martin Seidenberg will be its new chief executive as it reported first quarter results, revealing revenue edged up 0.3% from last year to £3.00 billion. A 4% drop in sales from Royal Mail was countered by 7.4% growth from GLS. It reiterated its outlook. Seidenberg will be charged with setting the company’s strategy and will appoint new CEOs for Royal Mail and GLS. He was part of the GLS team and has been CEO of the unit since June 2020. Before his time at the firm, he worked at Deutsche Post.
Airline easyJet is up 0.5% after it beat expectations as it delivered its highest pretax profit for any third quarter on record as the recovery from the pandemic continues. Passenger numbers were up 7% from last year but revenue soared 34% to £2.36 billion thanks to higher prices. That smashed the £2.3 billion forecast. Pretax profit of £203 million turned from a loss the year before and also blew the £161 million estimate out of the water. Its holiday arm continues to outperform and should contribute around £100 million in profits over the full year. The airline said the fourth quarter should be another record-setting period based on current bookings.
Dunelm is up 0.6% after sales rose 6% in the fourth quarter of its financial year to £381 million. That meant annual sales also rose 6% to £1.64 billion. The homeware retailer said pretax profit for the year should be ‘slightly ahead’ of expectations, which currently point toward a full year pretax profit of £188 million. Still, that is set to be down from the £212.8 million reported in the last financial year.
Babcock is down 1.8% this morning despite revealing revenue and margins improved in the year to the end of March and that cash generation improved significantly, as profits took a hit from exceptional items and losses on disposals. Sales rose to £4.43 billion from £4.10 billion. Operating profit slumped to just £45.5 million from over £226 million the year before, although increased on an underlying basis. It generated underlying free cashflow of £75.3 million compared to the outflow we saw the year before. It reiterated its guidance for the new financial year but said cashflow will be more weighted to the second half than previously expected. Importantly, it said revenue and margins should both improve and that it expects to reinstate its dividend!
QinetiQ Group is up 0.5% after the firm said it is on course to meet expectations this year after making a ‘positive’ start. It said the amount of revenue under contract has risen to £1.3 billion from £1.1 billion in April, giving it greater visibility going forward.
Vistry Group is down 0.4%. The housebuilder said it built 22% fewer houses in the first half of 2023 in response to more challenging conditions as higher interest rates weigh on demand for housing, although its average sales rate per week edged up to 0.86 from 0.84 the year before. However, it warned it has seen a slowdown since the latest rate hike and that it is cutting costs to try and counter the impact. It said 76% of units to be built this year have already been sold. Vistry is attempting to deliver adjusted pretax profit of at least £450 million over the full year. The integration of Countryside remains on track.
Premier Foods is up 2.9% after it said sales were up 21.1% in the first quarter and said trading profit should be at the ‘top end of market expectations’. Analysts currently estimate profits will come in the range of £162 million to £165.4 million over the full year.
Howden Joinery is down 0.3% after it said revenue growth stalled and profits fell in the first half as cost inflation continues to weigh on the bottom-line. The company said revenue was up 1.5% in the six-month period to £926.9 million, with 33% growth from overseas countering tepid 0.6% growth in the UK. Pretax profit was down 22.8% at £111.9 million as it struggled to counter inflationary pressures with efforts to improve efficiency. The interim dividend was raised 2.1% to 4.8p. Comparatives were tough following the record year it experienced in 2022. It reiterated its full year ambitions.
Alphawave is up over 3% this morning after reporting strong topline growth in the second quarter as it continued to win new contracts. The company, which specialises in high-speed connectivity for high-tech solutions, said new bookings jumped to $84.1 million from $28.4 million the year before. It said it secured eight new design contracts and won its first deal to supply its more advanced 3nm custom silicon design. It said China accounts for less than 10% of its business amid rising geopolitical tensions. ‘Customers' demand for our high-performance IP and products supports our strong pipeline. We are excited about the year ahead and the long-term continued growth potential of our business,’ said CEO Tony Pialis. It reiterated its full year outlook and is targeting annual revenue of $340 million to $360 million with adjusted Ebitda of around $87 million.
SSE is up 0.5% after the utility provider reaffirmed its full year guidance this morning after revealing renewable energy output was 5% short of expectations in the first quarter because of dry weather conditions and a lack of wind. SSE said the key months are still to come and that conditions have normalised in the second quarter, giving it confidence in its annual goal to deliver adjusted EPS of over 150p.
BHP Group is up 1.4% after it said production met its guidance targets in the year to the end of June, with several of its projects reporting record output. Copper production was up 9% over the year at 1.7 million tonnes, driven by growth at Escondida, Pampa Norte and a huge jump in contribution from Copper South Australia following the recent acquisition of Oz Minerals. Iron ore production was up 1% at 257 million tonnes as WAIO and Samarco both increased output. Metallurgical coal was flat, thermal coal edged up 3% and nickel production rose 4%. Commodity prices were, generally speaking, lower than the year before while inflation continued to pressure costs. ‘BHP finished the year with a strong fourth quarter, increasing annual production across the board and achieving annual records at WAIO, Olympic Dam and Spence,’ said CEO Mike Henry. It warned it will book an exceptional cost of $250 million to $300 million to reflect higher mining tax rates in Chile.
Anglo American is up 1.9% after it said it grew output of copper, iron ore and metallurgical coal in the second quarter. The mining giant said platinum group metal production was down 9% at 943,000 ounces because of operational challenges and planned closures. Nickel output was down 4% thanks to lower grades, while diamond output declined 5%. Copper rose 56% as its new Quellaveco mine ramps-up. Iron ore was up 9% thanks to a hike in throughput at Minas-Rio. ‘Our focus remains resolutely on safely achieving our full year production guidance through the seasonally stronger second half of the year,’ said CEO Duncan Wanblad.
How to trade the FTSE 100
You can trade the FTSE 100 with City Index in just four easy steps:
- Open a City Index account, or log-in if you’re already a customer.
- Search for ‘UK 100’ you want in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Or you can practice trading risk-free by signing up for our Demo Trading Account.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Short-term Outlook: AUD/USD 3% Plunge Puts Multi-Month Range at Risk 11 6 2026
A sharp equity-led selloff has driven AUD/USD toward critical June-low support, with strong NFP data adding pressure ahead of next week’s U.S. CPI.

Nasdaq 100 forecast: Tech stocks rebound but AI concerns linger
The Nasdaq 100 rebound has run into former support as fears over AI regulation and spending linger. Fawad Razaqzada explains why he maintains a cautious forecast and where the key levels sit.

Dollar forecast: NFP provides dollar, already supported amid tech sell-off, additional boost
The US dollar has found some mild amid the tech rout in recent days, most visibly against risk sensitive and commodity dollars. Today, we have so far seen a bit of a recovery in global indices from their overnight lows. Investors will be watching the markets to see whether fresh losses will be on the again once Wall Street gets going. Ahead of that, we have just seen the release of the October US non-farm payrolls report – and it was much stronger at 165K than expected.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.