



FTSE 100 analysis: Surprise acceleration in UK retail sales – Top UK stocks
UK retail sales picked-up more than expected in June, but we saw consumer confidence take its first knock in over six months to suggest thing are getting tougher for the British public.
Share this:

FTSE 100 hits 2-month high
The FTSE 100 is up 0.1% this morning and at its highest level in nearly two months.
The economic calendar is light today following early data out of the UK this morning as we discovered retail sales accelerated more than anticipated in June from May, although remained down from last year, while consumer confidence deteriorated for the first time in six months after falling to -30 in July from -24 in June, according to GfK.
Attention is on Canada this afternoon, when we have retail sales and the new housing price index due to be released.
FTSE 100 analysis: Where next for the UK 100?
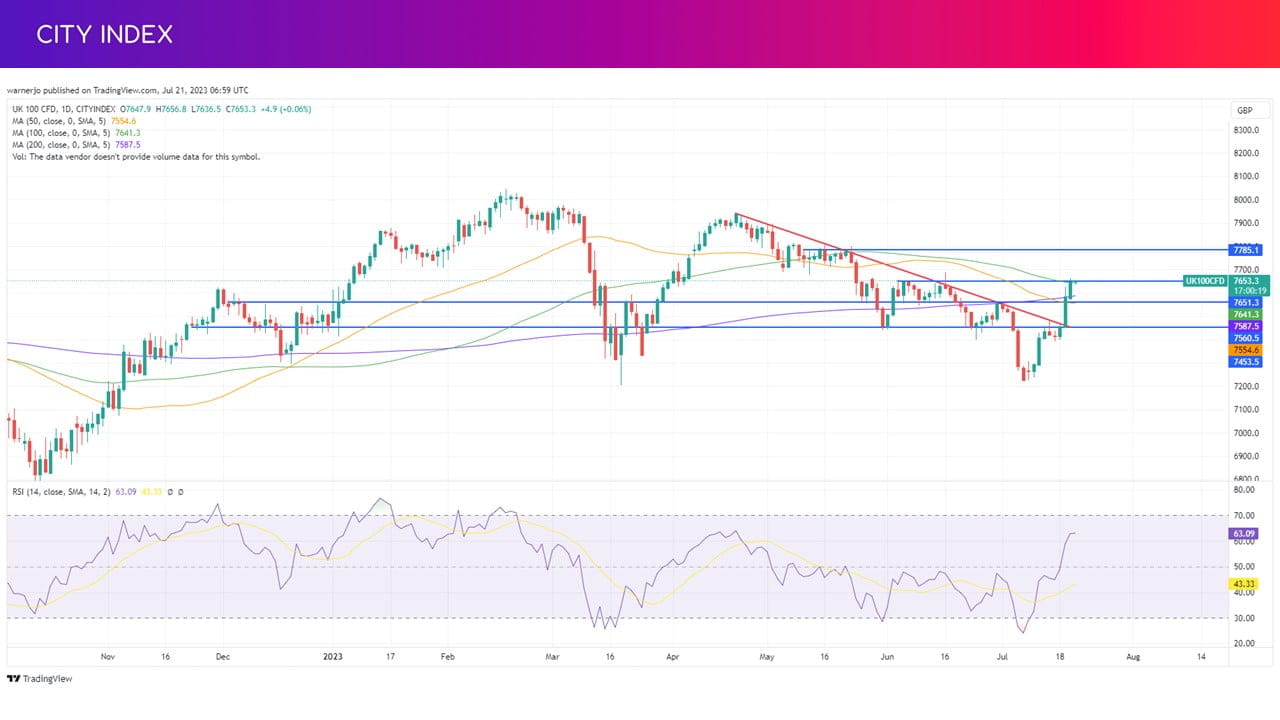
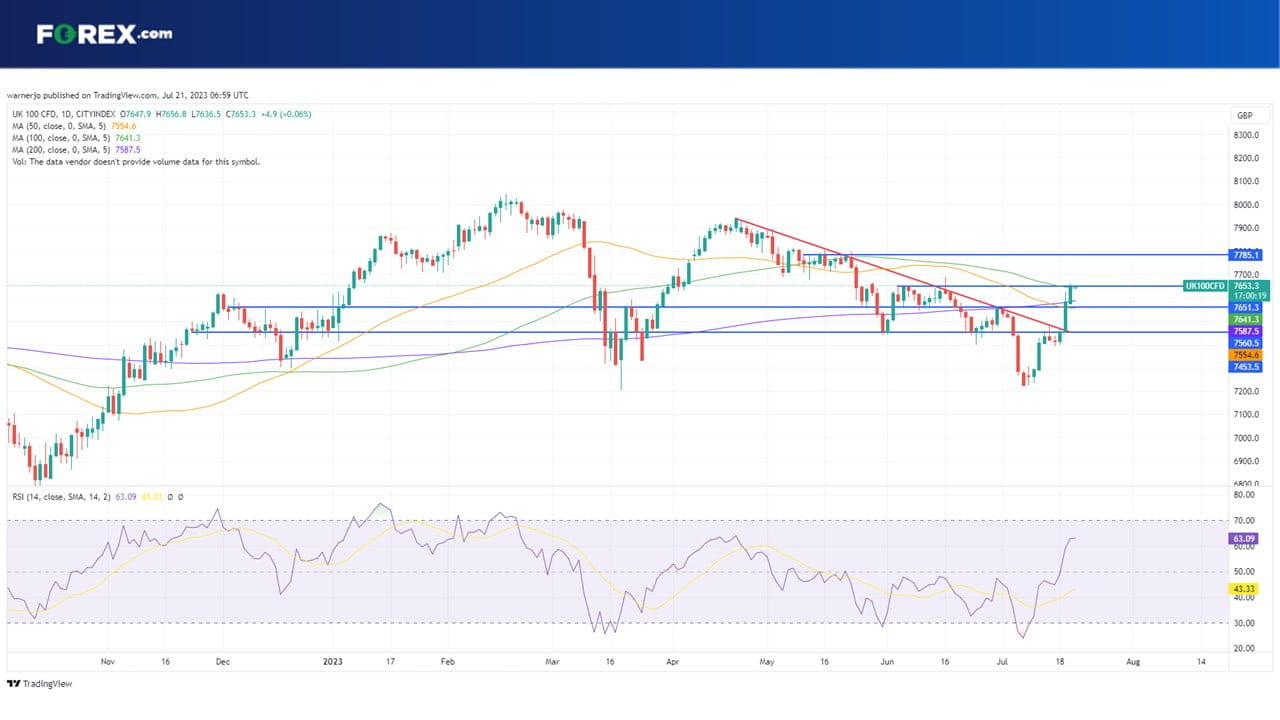
The UK 100, which tracks the FTSE 100, is at its highest level in almost two months after breaking above the falling trendline this week. The index is once again testing the 7,650 ceiling that was in play in late May and early June this morning, like it did yesterday, and this is aligned with the 100-day moving average. A close above here could install confidence that it can climb toward the next level of resistance at 7,780. The RSI remains in bullish territory and suggests the rally has further to go and the candles seen over the past three sessions have also been bullish.
The index is likely to slip back toward 7,550 if it comes under renewed pressure. Below here, we could see it fall back to 7,450.
Top UK stock news
Keep an eye on retailers such as Next, JD Sports, Frasers Group, Dunelm and Currys today after we discovered UK retail sales were up 0.7% month-on-month in June. That accelerated from the 0.3% lift we saw in May and was much stronger than the 0.2% forecast. Retail sales were still down 1% from the year before, but this also eased from the 2.1% drop the month before and was welcome versus the 1.5% drop forecast by economists.
THG is down 0.1% this morning after announcing plans to simplify its business by selling its OnDemand division. The trade and assets of the unit have been sold to its existing management with some financial assistance of advisory and investment firm Gordon Brothers. Notably, it said the business will remain a customer of its Ingenuity platform. THG has also sold ProBikeKit to London-listed Frasers Group for £4 million. Frasers is up 0.2% in early trade.
Glencore is down 0.3% after it revealed its huge Marketing arm that trades commodities around the world has seen its business normalise following the beneficial volatility we saw in 2022. Glencore said it expects annual adjusted Marketing Ebit to be around $3.5 billion to $4.0 billion this year, way above its long-term $2.3 billion to $3.2 billion target range. That came as it revealed production of most commodities was lower in the first half of 2023. Output of its key commodities fell, with copper production down 4%, coal output down 2% and zinc dropping by 10%. It reiterated its full year guidance and said volumes of its three key metals will be weighted to the second half.
Firstgroup is up 0.4% after it said it has traded in-line with expectations since the start of the new financial year ahead of its annual general meeting later today. The travel stock said it has returned £70.9 million of the £75 million share buyback programme launched in December. It will launch a new £115 million buyback once that is completed, so long as it secures shareholder support today. Firstgroup plans to release interim results on November 23.
Polymetal is down 4.4% today after it confirmed its last day of trading on the London Stock Exchange will be on August 1. Shares will be suspended when markets close on that day. That is part of its re-domicile plan that will see it move to Kazakhstan.
Liontrust Asset Management is down 1% after it said its takeover offer for GAM Holding is ‘a full and final offer and will not be increased’. The proposed acquisition first came to light in early May and Liontrust has now conducted its due diligence, which has given it confidence that its offer is ‘good and fair’. It said it will need to book significant restructuring costs to get GAM back to breakeven but believes the unit can compliment its existing business.
easyJet has been upgraded to Buy at Stifel this morning. The airline is up 1.6% this morning at 483p.
Babcock has been upgraded to Buy at Citi, which has a price target of 500p on the defence firm. The stock is up 2.8% at 371.53p this morning.
Treatt has been given an Overweight rating from Barclays and a 750p price target. The ingredient provider is trading flat at 628p in early trade.
How to trade the FTSE 100
You can trade the FTSE 100 with City Index in just four easy steps:
- Open a City Index account, or log-in if you’re already a customer.
- Search for ‘UK 100’ you want in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Or you can practice trading risk-free by signing up for our Demo Trading Account.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Short-term Outlook: AUD/USD 3% Plunge Puts Multi-Month Range at Risk 11 6 2026
A sharp equity-led selloff has driven AUD/USD toward critical June-low support, with strong NFP data adding pressure ahead of next week’s U.S. CPI.

Nasdaq 100 forecast: Tech stocks rebound but AI concerns linger
The Nasdaq 100 rebound has run into former support as fears over AI regulation and spending linger. Fawad Razaqzada explains why he maintains a cautious forecast and where the key levels sit.

Dollar forecast: NFP provides dollar, already supported amid tech sell-off, additional boost
The US dollar has found some mild amid the tech rout in recent days, most visibly against risk sensitive and commodity dollars. Today, we have so far seen a bit of a recovery in global indices from their overnight lows. Investors will be watching the markets to see whether fresh losses will be on the again once Wall Street gets going. Ahead of that, we have just seen the release of the October US non-farm payrolls report – and it was much stronger at 165K than expected.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.