


Gold weekly outlook: XAU/USD likely to remain under pressure
Gold managed to bounce a bit on Friday, although it was too little to prevent a weekly decline. On the week, the metal fell 2.5%, making its second consecutive weekly decline. Though gold again managed to hold its own above the key $4,000 level on a daily and weekly closing basis, the metal was now flat on the month.
Share this:
Gold managed to bounce a bit on Friday, although it was too little to prevent a weekly decline. On the week, the metal fell 2.5%, making its second consecutive weekly decline. Though gold again managed to hold its own above the key $4,000 level on a daily and weekly closing basis, the metal was now flat on the month. The struggles come as the dollar was looking to steady itself after suffering a double dose of inflation surprises last week with both CPI and PPI coming in weaker than expected. Meanwhile, we saw a bit of a risk off trade creeping into the stock markets with chipmakers under pressure on Wall Street, while Europe was again troubled by the escalation of tensions in the Middle East. We will maintain a modestly bearish view on the near-term gold outlook heading into the new week.
What factors have weighed on the gold outlook?
While the weaker inflation data from the US held back the dollar against certain currencies, it is worth remembering that one month’s worth of data is not going to impact the Fed’s thinking much and that’s something Chris Waller highlighted during the week. Waller, like most of his other FOMC colleagues, wants to see a clear disinflationary trend over the course of a few months. That’s not going to be the case if oil prices now remain elevated after making a comeback in recent days due to the re-escalation of tension between the US and Iran.
Even if some of the near-term economic data softens, persistently high energy prices would make it difficult for the Fed to adopt a more dovish stance. That is one of the reasons why we’re seeing the US dollar regained a bit of momentum towards the end of last week, particularly against currencies whose economies are heavily reliant on imported energy, or those where interest rates are low, such as the Swiss franc and the Japanese yen. For the same reason, investors are preferring the dollar over the zero-yielding gold.
On top of these macro factors, momentum has been completely lost in gold which is discouraging speculative traders wanting to ride the wave. While gold was flattish on the monthly time frame thanks to a small recovery on Friday, the yellow metal has been on a monthly losing streak. It fell more than 11% in June, which was its fourth consecutive losing month. Thus, the path of least resistance and the gold outlook remain modestly to the downside, and I am still expecting a breakdown below the $4,000 level soon.
Technical gold outlook and key levels to watch
From a technical analysis point of view, our gold outlook remains bearish. The metal has struggled in recent days to climb back above the $4,100 level, and instead it has remained below both the bearish trend line and the 21-day exponential average. The 50-day crossed below the 200-day average not so long ago and that further aids the bearish narrative.
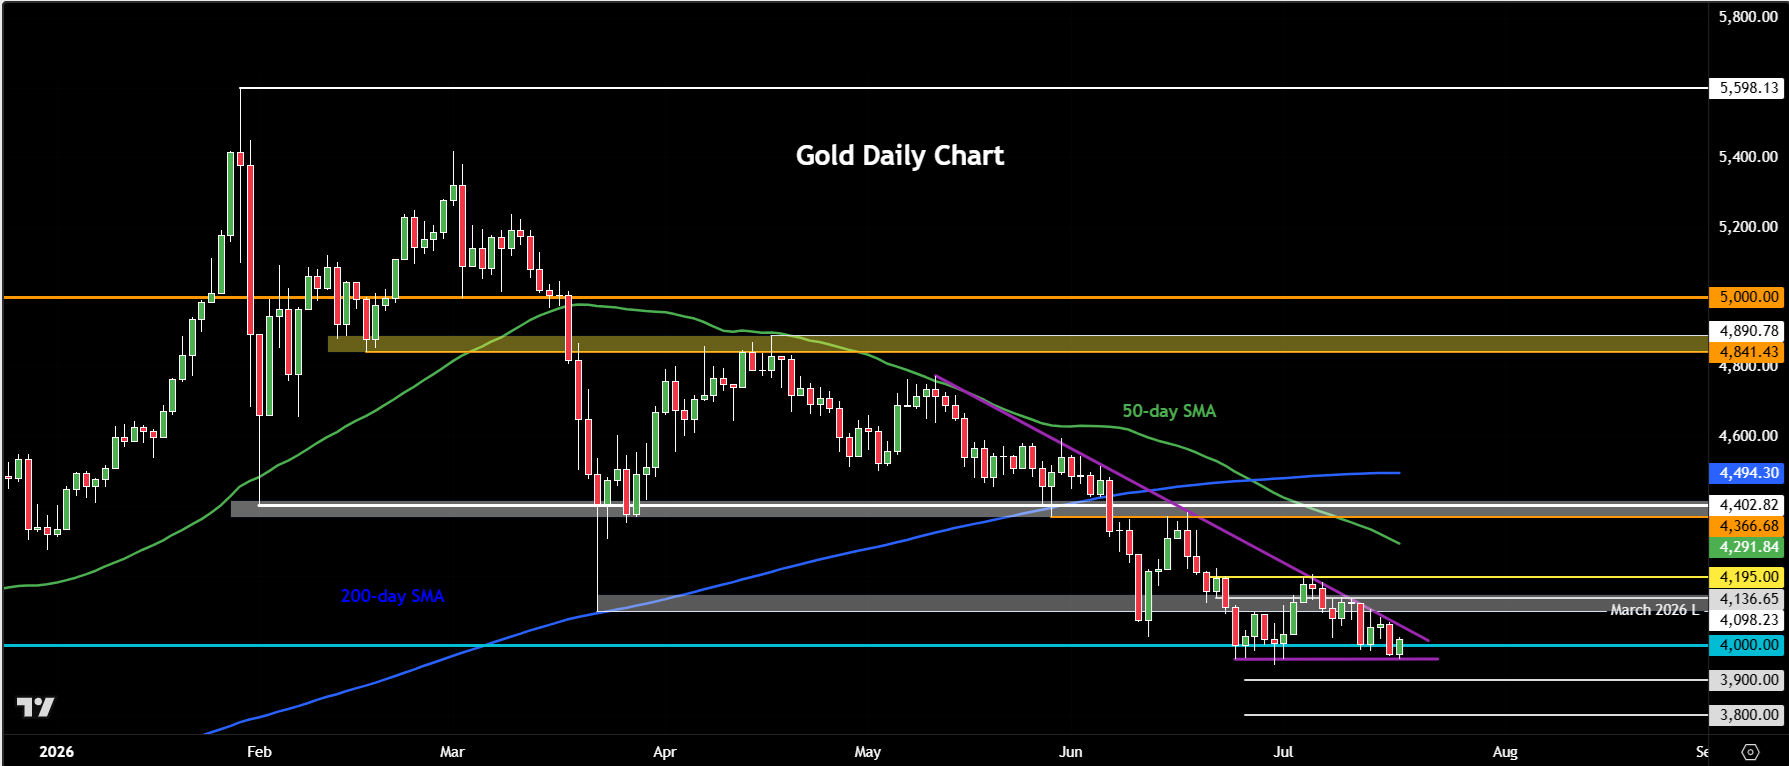
Thus, I’m looking for a break below the $4,000 level in the days ahead. If we get a daily close beneath it, then the next downside targets come in around $3,900, followed by $3,800.
Resistance above the $4100 area comes in around $4,136 initially, followed by $4,200 and then at $4275.
In short, with energy prices firming and little evidence that the US economy is slowing enough to offset inflation risks, the fundamental backdrop continues to favour the dollar. That leaves zero- and low-yielding assets like the yen, franc and gold particularly vulnerable.
Week ahead: UK CPI, ECB rate decision and global PMIs
The data calendar for the week ahead doesn’t look particularly important for the gold outlook, although the metal may still get some indirect reaction from the reaction of foreign currencies against the US dollar.
UK CPI is due on Wednesday, July 22. Uk inflation has been moderating in recent months, falling to 2.8% y/y in May and it is expected to fall further in June. Analysts expect a headline rate of 2.7%. Core CPI is also expected to fall to 2.5% from 2.6%. If inflation proves to be weaker, then this may provide some downward pressure on GBP. In any case, rising oil prices risk reviving stagflation concerns, which could keep pressure on GBP/USD.
ECB’s rate decision is on Thursday, July 23. Although ECB policymakers are widely expected to leave interest rates unchanged, rising energy prices have injected a degree of uncertainty into the outlook. Higher oil prices threaten to revive inflationary pressures while simultaneously weighing on economic growth, raising the spectre of stagflation. Some policymakers may therefore argue for maintaining a hawkish bias to preserve the ECB’s inflation-fighting credibility.
Global PMIs are due for release on Friday, July 24. The PMI surveys will offer a timely snapshot of business activity across the major economies and could shape expectations for both European growth and the direction of the euro over the coming weeks. Also worth keeping an eye on UK PMIs where the economy faces similar challenges (high oil and low growth).
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

GBP/USD forecast: BoE’s hawkish hike, NFP awaited and AI concerns linger
The GBP/USD was holding near the 1.35 handle after the Bank of England raised interest rates to 4% in a unanimous 9-0 vote, against expectations of a 7-2 split. The cable has also benefited from the US dollar's slide after the midterm elections, although Friday's non-farm payrolls report still lies ahead which could have a more meaningful impact.

Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?


Swiss Franc Short-term Outlook: USD/CHF Selloff Nears Critical Support Ahead of NFP 11 4 2026
USD/CHF bears are closing in on critical trend support, with the next reaction likely to determine whether the October decline has further to run.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.